Credit Score Changes 2026: What 700+ Means for Loan Approvals
The evolving credit landscape in 2026 will significantly impact loan approvals, making a credit score of 700 or higher increasingly crucial for favorable lending terms and access to diverse financial products.
By: Rafaela on September 23, 2026
The evolving credit landscape in 2026 will significantly impact loan approvals, making a credit score of 700 or higher increasingly crucial for favorable lending terms and access to diverse financial products.
As we approach 2026, understanding the impact of credit score changes on loan approvals: what 700+ means in 2026 becomes more critical than ever for individuals seeking financing. The financial world is in constant flux, with new regulations, technological advancements, and economic shifts continually reshaping how lenders assess risk and approve loans. This article delves into these anticipated changes, providing a comprehensive guide to navigating the future of credit.
The Evolving Landscape of Credit Scores in 2026
The year 2026 is poised to bring significant adjustments to how credit scores are calculated and interpreted by lenders. These changes are not arbitrary; they reflect a broader effort to make lending practices more robust, equitable, and responsive to evolving economic realities. Understanding these foundational shifts is the first step toward maintaining strong financial health and securing favorable loan terms.
One of the primary drivers behind these changes is the continuous refinement of algorithmic models used by credit bureaus. These models are becoming more sophisticated, incorporating a wider array of data points beyond traditional payment history and credit utilization. This can lead to a more nuanced view of a borrower’s financial reliability, but it also means that what constituted a ‘good’ score in the past might be re-evaluated.
New Data Points and Their Influence
Lenders are increasingly looking beyond the conventional data points to assess creditworthiness. This includes an exploration of alternative data, which can be both a challenge and an opportunity for consumers.
Rent Payment History: Many credit models are now incorporating on-time rent payments, offering a boost to those who consistently pay their housing expenses punctually.
Utility Bill Payments: Similarly, consistent, on-time utility payments (electricity, water, gas) are gaining traction as indicators of financial responsibility.
Banking Transaction Data: For some alternative lenders, analyzing banking transaction data for consistent savings, low overdraft rates, and regular income can provide valuable insights.
These new inclusions aim to create a more inclusive credit system, potentially benefiting individuals with limited traditional credit history. However, they also mean that a broader range of financial behaviors will directly influence your credit standing. The emphasis is shifting towards a holistic view of financial behavior, rather than solely focusing on credit accounts.
The evolving landscape also includes a greater focus on predictive analytics. Lenders are not just looking at past behavior, but actively trying to predict future financial stability. This means that consistent positive financial habits, even in non-traditional areas, will be more important than ever. The goal is to minimize risk for lenders while accurately identifying reliable borrowers.
Why a 700+ Credit Score Matters More Than Ever
In the upcoming financial climate of 2026, a credit score of 700 or higher is expected to solidify its position as a benchmark for prime borrowers. This threshold, often seen as ‘good’ to ‘excellent,’ will likely become even more critical for unlocking the most competitive interest rates and loan products. The increased sophistication of credit assessment models means that the distinction between a score just below 700 and one above it could widen significantly.
Lenders, facing economic uncertainties and a demand for more precise risk assessment, will likely gravitate towards borrowers who demonstrate exceptional financial discipline. A 700+ score signals a lower risk profile, translating directly into more favorable terms for mortgages, auto loans, personal loans, and credit cards. It’s not just about getting approved; it’s about getting the best approval.
Benefits of Maintaining a High Credit Score
The advantages of a credit score above 700 extend far beyond mere loan approval. They encompass a spectrum of financial benefits that can significantly impact your long-term economic well-being.
Lower Interest Rates: This is arguably the most significant benefit, leading to substantial savings over the life of a loan.
Better Loan Terms: Beyond interest rates, a high score can secure more flexible repayment schedules, lower fees, and higher loan amounts.
Easier Approval Process: Applications for credit typically proceed more smoothly and with fewer hurdles for individuals with strong credit.
Access to Premium Products: High-score borrowers often qualify for exclusive credit cards with superior rewards, higher credit limits, and enhanced benefits.
Improved Insurance Premiums: In many states, credit scores can influence auto and home insurance rates, with higher scores often leading to lower premiums.
The emphasis on a 700+ score in 2026 reflects a market that values stability and reliability. Lenders are seeking to mitigate potential defaults, and a strong credit history provides that assurance. Therefore, actively managing and improving your credit score will be an investment that yields considerable returns in the near future.
In summary, while a score below 700 might still grant access to some credit products, the distinction in terms and conditions will be more pronounced. Striving for and maintaining a 700+ credit score will be paramount for optimal financial flexibility and opportunity in 2026.
Key Factors Influencing Credit Scores in 2026
While the overall framework of credit scoring remains consistent, the weighting and interpretation of various factors are subject to change. In 2026, certain elements of your financial behavior are expected to carry more weight than others, making it essential to understand where to focus your efforts for credit improvement.
Payment history will undeniably remain the most significant factor, emphasizing the importance of paying all bills on time. However, the nuances of credit utilization and the types of credit you hold are also evolving, requiring a strategic approach to credit management. It’s not just about having credit, but how you responsibly use it.
Understanding the Weight of Each Component
Credit scoring models typically consider several key components, each contributing a different percentage to your overall score. While exact percentages can vary by model, the general hierarchy remains.
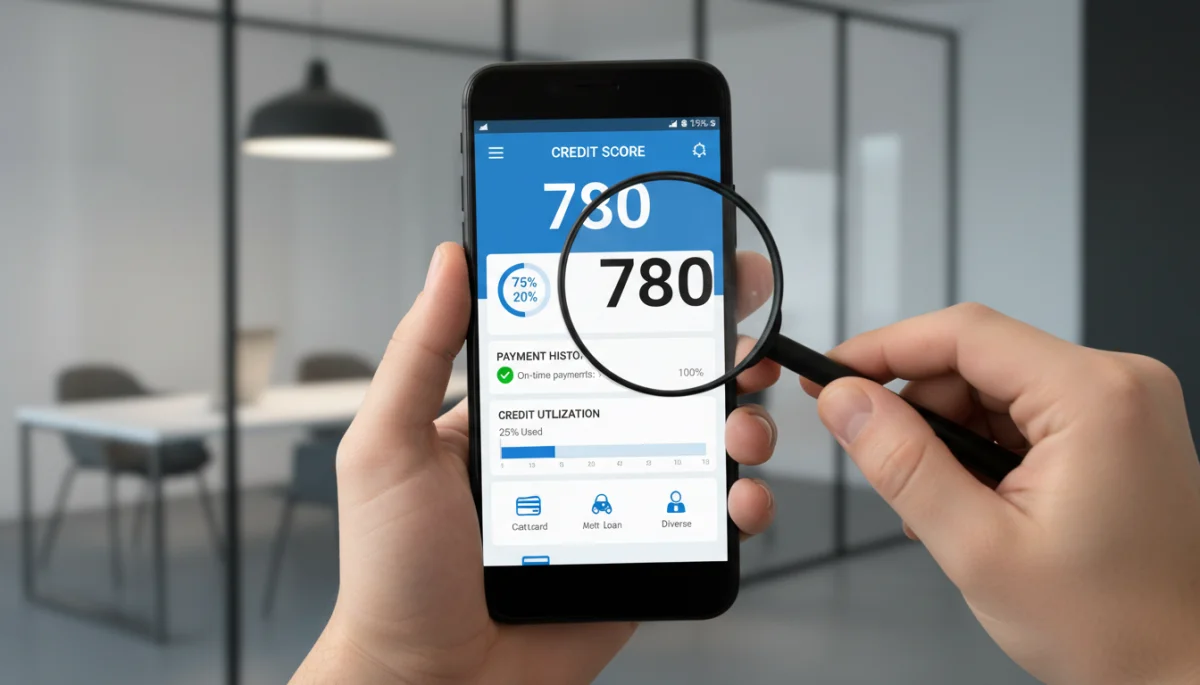
Payment History (approx. 35%): Consistently making on-time payments for all credit accounts is the single most important factor. Late payments, even a single one, can have a significant negative impact.
Amounts Owed/Credit Utilization (approx. 30%): This refers to the amount of credit you’re using compared to your total available credit. Keeping utilization below 30% is generally recommended for a healthy score.
Length of Credit History (approx. 15%): Longer credit histories with a good track record tend to result in higher scores. This demonstrates a sustained ability to manage credit responsibly.
New Credit (approx. 10%): Opening too many new credit accounts in a short period can be viewed as risky and may temporarily lower your score.
Credit Mix (approx. 10%): Having a healthy mix of different types of credit (e.g., installment loans like mortgages or auto loans, and revolving credit like credit cards) can positively influence your score.
The emphasis in 2026 will likely be on demonstrating consistent, long-term financial stability across all these factors. Lenders will be looking for patterns of responsible behavior rather than isolated instances of good credit management. This holistic view means that every financial decision contributes to your credit profile.
In essence, maintaining a high credit score in 2026 will require a proactive and disciplined approach to all aspects of your financial life. Understanding these key factors and their relative importance is crucial for strategizing your credit improvement efforts effectively.
Navigating Loan Approvals with Evolving Credit Standards
The anticipated credit score changes in 2026 will undoubtedly influence how lenders approach loan approvals. Borrowers need to be prepared for potentially stricter criteria and a more data-driven assessment process. This doesn’t mean obtaining a loan will be impossible, but it does mean that a strategic approach to your financial profile will be more beneficial than ever.
Lenders will leverage advanced analytics to assess risk, moving beyond a simple score to a more comprehensive understanding of a borrower’s financial health. This could involve deeper dives into banking behavior, employment stability, and even educational background for certain types of loans. Transparency and accuracy in your financial reporting will be paramount.
Strategies for Successful Loan Applications
To successfully navigate the loan approval landscape in 2026, borrowers should adopt several key strategies. These are designed to present the strongest possible financial profile to potential lenders.
Monitor Your Credit Regularly: Keep a close eye on your credit reports from all three major bureaus (Equifax, Experian, TransUnion) for inaccuracies and potential identity theft.
Reduce Credit Utilization: Aim to keep your credit card balances well below 30% of your available credit, ideally even lower, to signal responsible credit management.
Establish a Diverse Credit Mix: While not overdoing it, having a mix of revolving and installment credit can be beneficial.
Save for a Down Payment: A larger down payment on a mortgage or auto loan can significantly reduce the perceived risk for lenders, potentially compensating for other less-than-perfect aspects of your application.
Maintain Stable Employment: Lenders value consistent income and employment history as indicators of your ability to repay debt.
The emphasis in 2026 will be on demonstrating not just the ability, but also the willingness to repay debt. This means consistent positive financial actions across the board. Proactive management of your financial footprint will be the cornerstone of securing favorable loan approvals.
Ultimately, preparing for these changes involves a holistic approach to your personal finances. By understanding the evolving standards and proactively managing your credit, you can position yourself for success in the competitive lending environment of 2026.
Impact on Specific Loan Types: Mortgages, Auto, and Personal Loans
The changes in credit scoring and lending practices in 2026 will not affect all loan types equally. While the general principle of a higher credit score leading to better terms holds true, the specific implications for mortgages, auto loans, and personal loans will vary due to their inherent risk profiles and typical loan amounts.
For example, mortgages, being large, long-term commitments, will likely see the most stringent credit requirements. Auto loans, while significant, have the collateral of the vehicle, which can slightly alter the risk assessment. Personal loans, often unsecured, may become even more reliant on a strong credit score to mitigate lender risk.
Mortgage Lending in 2026
Mortgage lenders are expected to continue their cautious approach, with a 700+ credit score becoming an even stronger prerequisite for the best rates. Expect a greater emphasis on:
Debt-to-Income Ratio (DTI): Lenders will scrutinize DTI more closely, ensuring borrowers are not overextended.
Down Payment Size: A larger down payment will significantly improve your chances of approval and secure better terms.
Employment Stability: A consistent work history will be crucial, demonstrating reliable income.
Auto Loan Landscape
For auto loans, a 700+ score will be key to accessing the lowest interest rates offered by dealerships and banks. While less stringent than mortgages, lenders will still focus on:
Payment History: Any recent late payments can disproportionately affect auto loan eligibility.
Existing Debt Load: High existing debt can signal a higher risk, even with a good score.
Personal Loan Requirements
Personal loans, often unsecured, will likely see an increased premium placed on credit scores. A 700+ score will be essential for:
Competitive Rates: Without collateral, your credit score is the primary indicator of your repayment ability.
Higher Loan Amounts: Lenders will be more comfortable offering larger sums to borrowers with excellent credit.
Flexibility: Good credit can lead to more flexible repayment options and fewer fees.
In essence, while the specific impacts differ, the overarching theme for 2026 is that a credit score of 700+ will be a powerful asset across all major loan categories, ensuring access to the most favorable lending conditions.
Strategies for Boosting Your Credit Score to 700+ by 2026
Achieving and maintaining a credit score of 700+ by 2026 requires deliberate and consistent effort. It’s a marathon, not a sprint, and involves cultivating good financial habits that positively impact all aspects of your credit profile. Starting early and being diligent are the keys to success in this evolving credit environment.
The strategies outlined here are not quick fixes but rather foundational practices that will strengthen your creditworthiness over time. They address the core components of credit scoring models, ensuring a comprehensive approach to credit improvement. Remember, every positive action contributes to your overall financial health.
Actionable Steps to Improve Your Credit
Implementing these strategies consistently will pave the way for a robust credit score that meets or exceeds the 700+ benchmark.
Pay Bills on Time, Every Time: Set up automatic payments or reminders to ensure you never miss a due date. This is the single most impactful action you can take.
Keep Credit Utilization Low: Aim to use less than 30% of your available credit on credit cards. Ideally, keep it even lower, around 10-20%, for optimal results.
Review Credit Reports Annually: Obtain free copies of your credit reports from AnnualCreditReport.com and dispute any errors immediately.
Avoid Opening Too Many New Accounts: While a diverse credit mix is good, opening multiple new credit lines in a short period can signal risk to lenders.
Maintain Older Accounts: The length of your credit history matters. Keep older, well-managed accounts open, even if you don’t use them frequently.
Consider a Secured Credit Card or Credit Builder Loan: If you have limited credit history, these tools can help you establish a positive payment track record.
Consistently applying these strategies will not only help you reach a 700+ credit score but also build a solid foundation for long-term financial stability. The effort invested now will yield significant returns in the form of better loan terms and greater financial opportunities in 2026 and beyond.
The Future of Credit: Predictions Beyond 2026
While our immediate focus is on 2026, it’s prudent to consider the trajectory of credit scoring and loan approvals in the years that follow. The financial industry is dynamic, driven by technological innovation, regulatory shifts, and evolving consumer behaviors. Understanding these potential future trends can help individuals stay ahead of the curve and maintain optimal financial health.
Expect an even greater integration of artificial intelligence and machine learning into credit assessment. These technologies will enable lenders to analyze vast datasets with unprecedented speed and accuracy, potentially leading to more personalized credit offers but also more granular scrutiny of individual financial habits. The concept of a ‘universal’ credit score might also evolve, with different lenders prioritizing different aspects of your financial data based on their specific risk models and product offerings.
Emerging Trends in Credit Assessment
Several trends are on the horizon that could further redefine creditworthiness and loan approvals in the post-2026 era.
Hyper-Personalized Lending: AI will allow lenders to offer highly tailored loan products and interest rates based on an individual’s specific financial behavior and risk profile, moving beyond standardized tiers.
Behavioral Economics Integration: Credit models may increasingly incorporate insights from behavioral economics, understanding psychological factors that influence financial decisions.
Blockchain and Distributed Ledger Technology: While still nascent, blockchain could offer secure, transparent, and immutable records of financial transactions, potentially revolutionizing how credit history is stored and accessed.
Environmental, Social, and Governance (ESG) Factors: Some forward-thinking lenders might begin to consider a borrower’s ESG footprint, especially for business loans, reflecting a broader societal shift towards sustainable practices.
The future of credit will likely emphasize transparency, data security, and a more comprehensive view of an individual’s financial ecosystem. Borrowers who embrace proactive financial management, adapt to new technologies, and maintain a strong ethical financial footprint will be best positioned for success. The traditional credit score will remain a cornerstone, but its interpretation will be enriched by a multitude of other data points and analytical insights.
Key Aspect
Description in 2026
700+ Score Significance
Essential for prime rates and favorable loan terms across all categories (mortgages, auto, personal).
Credit Model Evolution
Incorporation of alternative data (rent, utilities) and advanced AI for holistic risk assessment.
Loan Approval Factors
Increased scrutiny on debt-to-income, stable employment, and overall financial behavior.
Frequently Asked Questions About Credit Scores in 2026
Will my rent payments affect my credit score in 2026?▼
Yes, increasingly so. Many credit models in 2026 are integrating on-time rent payment history. This can positively impact your score, especially if you have a limited traditional credit history, by demonstrating consistent financial responsibility to lenders.
What does a 700+ credit score specifically mean for mortgage rates?▼
A 700+ credit score in 2026 will likely qualify you for the most competitive mortgage interest rates. Lenders view scores in this range as indicative of low risk, translating to lower borrowing costs and potentially more favorable loan terms over the life of your mortgage.
How can I quickly improve my credit utilization ratio?▼
To quickly improve your credit utilization, focus on paying down credit card balances. If possible, make multiple payments throughout the month rather than just one. You could also consider requesting a credit limit increase, but only if you trust yourself not to increase your spending.
Are new credit scoring models more inclusive?▼
Yes, the trend in 2026 is towards more inclusive credit scoring models. By incorporating alternative data like rent and utility payments, these models aim to provide a more holistic view of financial reliability, potentially benefiting individuals who previously struggled to build traditional credit history.
Will my employment history become more important for loan approvals?▼
Yes, stable employment history is expected to gain even more prominence in 2026. Lenders increasingly view consistent employment as a strong indicator of a borrower’s ability to generate reliable income and, consequently, their capacity to repay debts on time.
Conclusion
The financial landscape of 2026 marks a significant evolution in how creditworthiness is assessed, making a credit score of 700 or higher an indispensable asset for anyone seeking favorable loan approvals. The integration of advanced analytics, alternative data points, and a deeper scrutiny of overall financial behavior means that proactive credit management is no longer optional but essential. By understanding these shifts and diligently applying strategies to maintain a robust credit profile, individuals can confidently navigate the future of lending, securing the best possible terms for their financial aspirations. Staying informed and financially disciplined will be the cornerstone of success in the years to come.