Discover the critical student loan forgiveness updates for 2026, analyzing the financial impact of new federal initiatives on US borrowers. This guide helps you navigate evolving policies and potential relief.
By: Rafaela on September 23, 2026
The 2026 student loan forgiveness updates significantly reshape the financial landscape for US borrowers, introducing new federal programs aimed at alleviating debt burdens and fostering economic stability.
As we navigate the complexities of personal finance, one area that consistently garners significant attention is student loan debt. The landscape of student loan forgiveness updates in 2026 is poised to bring substantial changes, offering both hope and new challenges for millions of US borrowers. Understanding these evolving federal programs and their potential financial impact is crucial for making informed decisions about your future.
Understanding the Evolving Student Loan Forgiveness Landscape
The year 2026 marks a pivotal moment for student loan borrowers in the United States, as new federal programs and adjustments to existing policies come into effect. These changes are designed to provide relief to individuals grappling with substantial educational debt, but navigating the intricacies of each program can be daunting. It’s essential for borrowers to stay informed about the specific criteria and benefits associated with these updates to maximize their chances of eligibility and financial relief.
Key Federal Initiatives for 2026
Several federal initiatives are at the forefront of the 2026 student loan forgiveness landscape. These programs often target specific groups of borrowers or types of loans, reflecting a broader government effort to address the multifaceted nature of student debt. Understanding the distinctions between these initiatives is the first step toward determining which opportunities might apply to your situation.
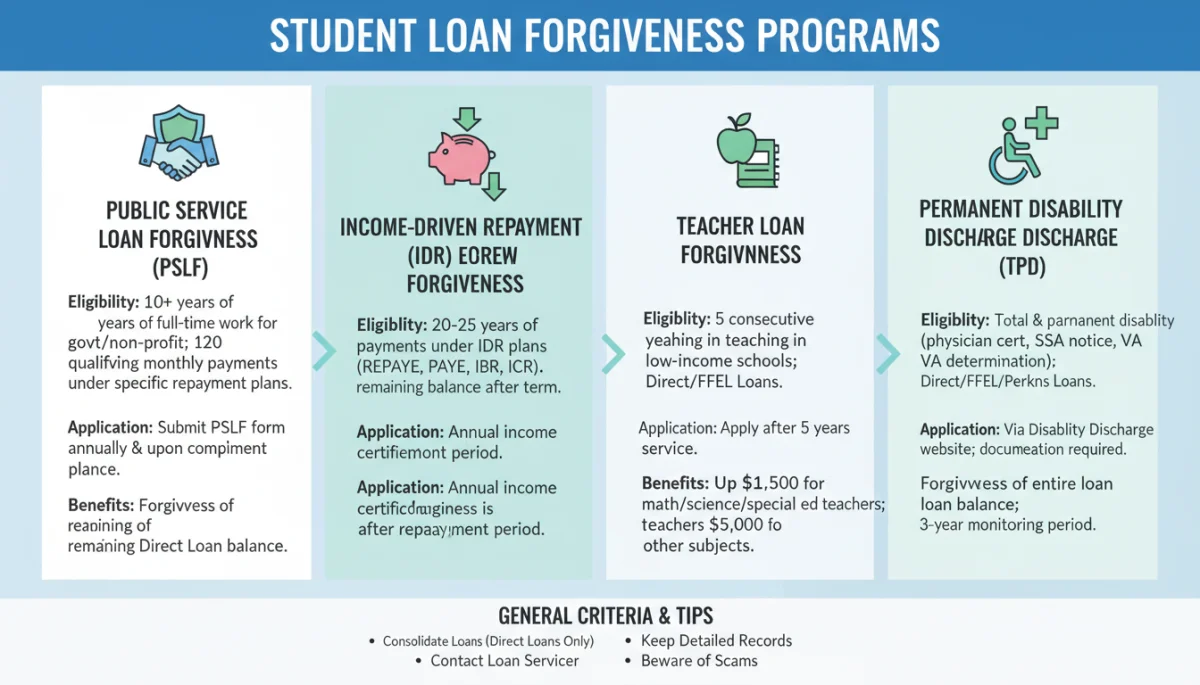
Income-Driven Repayment (IDR) Plan Enhancements: Expect further refinements to IDR plans, potentially lowering monthly payments and accelerating the timeline for forgiveness for many borrowers.
Public Service Loan Forgiveness (PSLF) Program Streamlining: Efforts continue to simplify the PSLF application process and expand eligibility, aiming to provide more accessible relief for those in public service.
Targeted Forgiveness Programs: New programs may emerge, focusing on specific professions, individuals with disabilities, or those who attended institutions that engaged in misconduct.
These initiatives represent a concerted effort to create a more equitable and manageable student loan system. However, the exact details of implementation and the long-term sustainability of these programs will continue to be subjects of discussion and potential adjustment.
The overarching goal of these federal programs is to reduce the burden of student debt, allowing borrowers to achieve greater financial stability and contribute more actively to the economy. By understanding the core principles and targeted relief mechanisms, borrowers can better prepare for the financial implications of these updates.
Eligibility Criteria for New Forgiveness Programs
Determining eligibility for the various student loan forgiveness programs in 2026 is a critical step for any borrower seeking relief. The criteria can vary significantly from one program to another, often depending on factors such as the type of loan, employment history, income level, and specific life circumstances. It’s imperative to meticulously review the requirements for each program to ensure you meet all necessary conditions.
Understanding Loan Types and Employment Requirements
Not all student loans are created equal when it comes to forgiveness. Federal loans typically have more pathways to forgiveness than private loans. Moreover, many programs, such as Public Service Loan Forgiveness (PSLF), hinge on specific employment types.
Federal vs. Private Loans: Most federal forgiveness programs are exclusively for federal student loans (Direct Loans, FFEL Program loans, Perkins Loans). Private loans generally do not qualify.
Qualifying Employment: For programs like PSLF, working full-time for a qualifying non-profit organization or government agency is a fundamental requirement. The definition of ‘full-time’ and ‘qualifying employment’ can be precise, so careful review is necessary.
Income-Driven Repayment (IDR) Eligibility: IDR plans base your monthly payment on your income and family size. Eligibility for forgiveness under IDR plans typically requires a certain number of years of qualifying payments, often 20 or 25 years, after which any remaining balance is forgiven.
Beyond these broad categories, certain targeted programs might have additional, very specific criteria. For instance, programs for teachers might require teaching in a low-income school, while others for healthcare professionals might demand service in underserved areas. Staying updated on these nuanced requirements is crucial.
The federal government continually refines these programs to address evolving needs and economic conditions. Therefore, what was true last year might have subtle but significant changes in 2026. Borrowers should regularly check official Department of Education resources for the most current and accurate eligibility information.
Financial Impact on US Borrowers: A Closer Look
The financial impact of student loan forgiveness updates in 2026 on US borrowers extends far beyond simply eliminating debt. It has the potential to reshape individual financial landscapes, influencing everything from credit scores and purchasing power to long-term investment strategies. Understanding these broader implications is key to maximizing the benefits of any forgiveness received.
Immediate and Long-Term Financial Benefits
For borrowers who qualify, the immediate benefit of loan forgiveness is the removal of a significant financial burden. This can free up disposable income, which can then be allocated to other financial goals. The long-term effects, however, are even more profound.
Improved Credit Scores: Reduced debt-to-income ratios can positively impact credit scores, opening doors to better rates on mortgages, car loans, and other forms of credit.
Increased Disposable Income: With lower or no student loan payments, borrowers can save more, invest, or address other financial obligations, leading to greater financial flexibility.
Stimulated Economic Activity: On a macroeconomic level, widespread forgiveness can boost consumer spending, support small businesses, and contribute to overall economic growth as individuals have more funds available.
However, it’s also important to consider potential tax implications. While some federal student loan forgiveness may be tax-free, others might be considered taxable income by the IRS. Borrowers should consult with a tax professional to understand their specific situation and plan accordingly.
The psychological relief associated with debt forgiveness should not be underestimated. The reduction of financial stress can lead to improved mental well-being, allowing individuals to focus on career advancement, family planning, and personal development without the constant pressure of student loan payments.
Navigating Application Processes and Documentation
Securing student loan forgiveness in 2026 requires more than just meeting eligibility criteria; it demands a meticulous approach to the application process and thorough documentation. Errors or omissions in paperwork can lead to delays or even outright rejection, making attention to detail paramount. Borrowers must understand the specific forms, deadlines, and supporting documents required for each program they are pursuing.
Essential Steps for a Successful Application
The application process for federal student loan forgiveness programs can be complex, often involving multiple steps and various agencies. Being prepared with all necessary information and documents can significantly streamline the process.
Gathering Documentation: This includes proof of income, employment history, tax returns, and records of past student loan payments. For PSLF, specific employment certification forms are crucial.
Understanding Deadlines: Many programs have specific application windows or annual recertification requirements. Missing these deadlines can jeopardize your eligibility.
Utilizing Official Resources: Always refer to the official websites of the Department of Education or your loan servicer for forms and instructions. Avoid third-party services that charge for assistance that is available for free.
For Income-Driven Repayment (IDR) plans, annual recertification of income and family size is a continuous requirement. Failure to recertify can lead to increased monthly payments and even capitalization of interest, which adds to your principal balance. Therefore, staying organized and proactive is not just about initial application but also ongoing compliance.
Seeking guidance from a certified financial advisor or a non-profit credit counseling agency can also be beneficial, especially for complex cases. These professionals can help you understand the nuances of the application process and ensure all your documentation is in order before submission.
Comparing Federal and State-Specific Forgiveness Options
While federal programs dominate the conversation around student loan forgiveness updates in 2026, it’s crucial for US borrowers to also be aware of state-specific forgiveness options. These programs, often designed to address local needs or attract professionals to critical sectors, can offer additional avenues for debt relief. A comprehensive financial strategy involves exploring both federal and state-level opportunities.
Leveraging All Available Avenues for Relief
State-specific programs often complement federal initiatives, targeting areas where the state has a particular need. These can include programs for healthcare professionals, teachers, lawyers, and even individuals working in certain high-demand industries within the state.
Healthcare Professionals: Many states offer loan repayment assistance to doctors, nurses, and other medical personnel who agree to work in underserved rural or urban areas for a specified period.
Educators: Similar to federal programs, states often have their own teacher loan forgiveness programs, especially for those who teach in high-needs subjects or schools.
Public Defenders/Prosecutors: Some states provide loan assistance to attorneys who choose to work in public service roles, addressing a critical need for legal aid.
The eligibility requirements and benefits for state programs vary widely. Some might offer a one-time lump sum payment, while others provide annual awards over several years. It’s essential to research the specific programs available in your state of residence or the state where you intend to work. Often, these programs have residency requirements or mandates to practice within the state for a certain duration.
Combining federal and state programs can significantly accelerate debt relief. For example, a borrower might be pursuing Public Service Loan Forgiveness (PSLF) at the federal level while simultaneously receiving state-level assistance for their public service work. This layered approach can provide a more robust safety net and faster path to financial freedom.
Future Outlook and Potential Policy Shifts
The landscape of student loan forgiveness is dynamic, with potential policy shifts always on the horizon. As we look towards and beyond 2026, understanding the factors that could influence future programs and the political climate surrounding student debt relief is vital for borrowers. These changes can impact eligibility, program availability, and the overall financial benefits.
Anticipating Legislative Changes and Economic Factors
Policy decisions regarding student loan forgiveness are often driven by a combination of economic conditions, political priorities, and public sentiment. Borrowers should remain vigilant for legislative proposals and economic indicators that could signal upcoming changes.
Economic Conditions: Periods of economic downturn or high unemployment may prompt policymakers to expand forgiveness programs to stimulate the economy.
Political Climate: Changes in administration or congressional control can lead to significant shifts in student loan policy, potentially introducing new programs or altering existing ones.
Public Advocacy: Ongoing efforts by advocacy groups and public pressure can also influence the direction of student loan reform.
One area of continuous discussion is the taxability of forgiven debt. While some forms of federal forgiveness are currently tax-exempt, this status could change in the future. It’s crucial for borrowers to consult with tax professionals to understand the implications of any forgiveness received, both now and in the future.
Furthermore, the long-term sustainability of existing and proposed forgiveness programs is a subject of ongoing debate. Policymakers must balance the need for borrower relief with the fiscal responsibility of the federal budget. These considerations will undoubtedly shape the future trajectory of student loan forgiveness, making it essential for borrowers to stay informed and adaptable.
Key Aspect
Brief Description
New Federal Programs
Expansions and refinements to IDR and PSLF, plus new targeted initiatives for specific borrower groups.
Eligibility Criteria
Varies by loan type, employment, income, and specific program requirements; federal loans are primary focus.
Requires meticulous documentation, adherence to deadlines, and utilization of official government resources.
Frequently Asked Questions About Student Loan Forgiveness in 2026
What are the main student loan forgiveness updates for 2026?▼
The main updates for 2026 include enhancements to Income-Driven Repayment (IDR) plans, streamlining of the Public Service Loan Forgiveness (PSLF) program, and potential introduction of new targeted forgiveness initiatives. These aim to broaden eligibility and simplify access to relief for US borrowers struggling with educational debt.
Who is eligible for student loan forgiveness in 2026?▼
Eligibility varies significantly by program. Generally, federal student loan borrowers may qualify based on factors like income, employment in public service, or specific life circumstances. Private loans are typically not eligible for federal forgiveness programs. It’s crucial to check specific program criteria.
How will these updates financially impact US borrowers?▼
The financial impact includes improved credit scores due to reduced debt, increased disposable income for savings or other investments, and reduced stress. However, some forgiven debt might be considered taxable income, so consulting a tax professional is recommended to understand individual implications.
What steps should I take to apply for forgiveness?▼
To apply, gather all necessary documentation such as income proof, employment history, and loan records. Pay close attention to deadlines and utilize official government websites or your loan servicer for forms and instructions. Consider consulting a financial advisor for complex situations.
Are there state-specific student loan forgiveness options available?▼
Yes, many states offer their own student loan forgiveness or repayment assistance programs. These often target professionals in high-need areas like healthcare or education within the state. Researching programs in your state of residence or intended employment can provide additional avenues for relief beyond federal options.
Conclusion
The student loan forgiveness updates in 2026 represent a significant evolution in federal efforts to address the widespread challenge of educational debt for US borrowers. These new programs and refinements to existing policies offer substantial opportunities for financial relief, potentially improving credit scores, increasing disposable income, and fostering greater economic stability. However, navigating the intricate eligibility requirements, application processes, and potential tax implications demands careful attention and proactive engagement from borrowers. By staying informed, meticulously preparing documentation, and exploring both federal and state-specific options, individuals can effectively leverage these updates to achieve a more secure financial future.