2026 Credit Score Changes: 15-Point Shift & Borrowing Power
The impending 2026 credit score changes, potentially introducing a 15-point shift, will significantly redefine lending criteria and impact individual borrowing power across the United States.
By: Rafaela on September 23, 2026
The impending 2026 credit score changes, potentially introducing a 15-point shift, will significantly redefine lending criteria and impact individual borrowing power across the United States.
Are you ready for the seismic shift coming to your financial landscape? In 2026, significant alterations to credit scoring models are set to redefine how lenders assess your creditworthiness, with a potential 2026 credit score changes leading to a 15-point fluctuation for many. This isn’t just a minor tweak; it’s a fundamental recalibration that could dramatically influence your ability to secure loans, mortgages, and even apartment rentals. Understanding these changes now is crucial for safeguarding your financial future and maintaining your borrowing power.
Understanding the Upcoming 2026 Credit Score Changes
The financial world is constantly evolving, and credit scoring models are no exception. The 2026 credit score changes represent a proactive effort to make these models more accurate and reflective of modern consumer financial behavior. These adjustments are designed to provide a clearer picture of risk for lenders while ideally offering more opportunities for responsible borrowers.
Historically, credit scores have been a cornerstone of financial access, dictating everything from interest rates to insurance premiums. The impending modifications aim to refine this system, potentially incorporating new data points or re-weighting existing ones. For consumers, this means a need to re-evaluate their financial habits and proactively prepare for how these shifts might manifest in their personal credit profiles.
The rationale behind the reforms
The primary drivers for these reforms include a desire to reduce bias, enhance predictive accuracy, and adapt to changes in how people manage their finances, such as the rise of alternative data. Regulators and credit bureaus are seeking to create a more equitable system.
Reducing reliance on traditional data: Exploring alternative data sources.
Adapting to economic shifts: Reflecting current financial realities.
Ultimately, these foundational changes are not arbitrary; they are a response to a continually shifting economic landscape and a push for more inclusive and precise financial assessments. Being informed about the underlying reasons can help individuals anticipate and strategize for the impact on their own credit standing.
The 15-Point Shift: What Does it Truly Mean?
The widely discussed 15-point shift isn’t a guaranteed increase or decrease for everyone; rather, it signifies the potential for a significant movement in either direction for a substantial portion of the population. This magnitude of change can have tangible effects on a borrower’s financial opportunities. A 15-point swing can be the difference between qualifying for a prime interest rate or being relegated to a subprime category.
For some, this shift could mean improved access to credit and lower borrowing costs, while for others, it might lead to higher interest rates or even outright denial for certain financial products. The impact will largely depend on individual credit profiles and how specific behaviors are re-weighted within the new models. It’s crucial not to view this as a universal adjustment but as a highly personalized outcome.
Potential scenarios for credit score changes
Imagine your score is currently 700. A 15-point increase puts you at 715, potentially opening doors to better mortgage rates. Conversely, a 15-point decrease to 685 might push you into a less favorable lending tier. These seemingly small changes can translate to thousands of dollars over the life of a loan.
Marginal impact: For those with very high or very low scores, the relative impact might be less pronounced.
Understanding these potential scenarios is the first step in preparing for the 2026 credit score changes. It underscores the importance of proactive credit management rather than a reactive approach once the changes are in full effect.
Impact on Your Borrowing Power: Loans, Mortgages, and More
Your credit score is a numerical representation of your financial reliability, and as such, it directly dictates your borrowing power across a spectrum of financial products. With the 2026 credit score changes and the potential 15-point shift, the landscape for obtaining loans, mortgages, auto financing, and even rental agreements could be significantly altered. Lenders rely heavily on these scores to assess risk, and any fluctuation can trigger different lending tiers and associated terms.
For instance, a higher score often translates to lower interest rates on mortgages, saving homeowners tens of thousands over the loan’s lifetime. A lower score, even by just a few points, could mean a higher interest rate, increasing monthly payments and total cost. Similarly, auto loans and personal loans will see similar effects, with better scores unlocking more favorable terms. Even landlords often check credit scores as part of their tenant screening process, making a strong score vital for housing access.
Specific financial products affected
The reach of credit scores is extensive, touching almost every aspect of financial life where borrowing is involved. Preparing for these changes means understanding which areas will feel the most significant impact.
Mortgages: Interest rates, loan approval, down payment requirements.
Auto Loans: APRs, loan terms, and eligibility for specific vehicles.
Personal Loans & Credit Cards: Available credit limits, interest rates, and reward programs.
Rental Applications: Landlord approval and security deposit amounts.
Ultimately, a robust credit score is a powerful financial tool. The 2026 modifications highlight the ongoing need for vigilance and strategic credit management to maintain and enhance your borrowing power.
Key Factors Influencing Credit Scores in the New Era
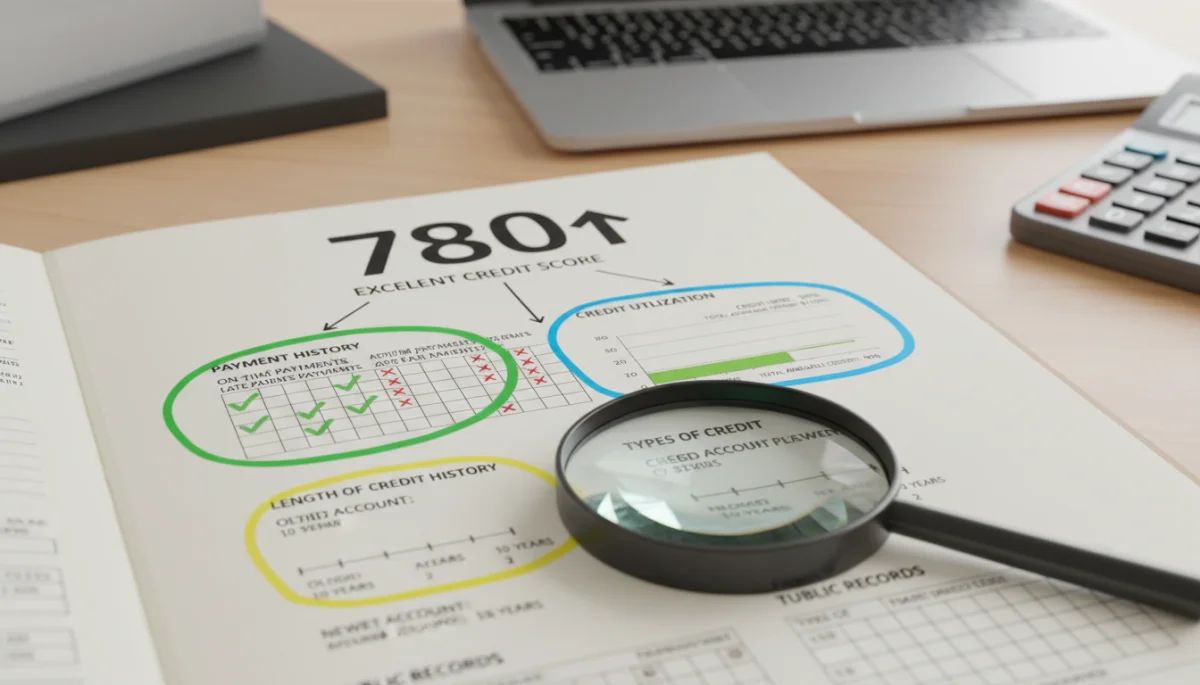
While the exact methodology of the 2026 credit score changes is still being finalized, core principles of credit scoring are likely to remain, albeit with potential re-weighting. Understanding these fundamental factors is paramount for anyone looking to optimize their score. Payment history, credit utilization, length of credit history, types of credit used, and new credit are the traditional pillars. However, the new models might place different emphasis on these, or even introduce new elements.
For example, some discussions revolve around incorporating rent payment history or utility payments more prominently, which could benefit individuals who consistently pay these bills on time but have limited traditional credit. Conversely, certain types of debt or financial behaviors might be penalized more heavily. Staying informed about these evolving priorities will be key to adapting your financial strategy effectively.
Strategies for optimizing your score
To proactively manage your credit score in anticipation of the 2026 changes, focus on these time-tested strategies, keeping an eye on any new guidelines:
Payment History: Always pay your bills on time. This remains the most critical factor.
Credit Utilization: Keep your credit card balances low relative to your credit limits, ideally below 30%.
Length of Credit History: Don’t close old accounts, as this can shorten your average credit age.
Mix of Credit: A healthy mix of revolving credit (credit cards) and installment loans (mortgages, auto loans) can be beneficial.
New Credit: Avoid opening too many new credit accounts in a short period, as this can signal higher risk.
By diligently managing these factors, you can position yourself favorably for the upcoming changes, ensuring your credit score reflects your financial responsibility.
Preparing for 2026: Actionable Steps for Consumers
The impending 2026 credit score changes aren’t a cause for panic, but rather an urgent call to action. Proactive preparation is the best defense against any potential negative impacts and the best offense for leveraging positive shifts. Starting now, consumers should take concrete steps to review their credit health, understand their current financial standing, and implement strategies that align with potential new scoring methodologies.
This preparation involves more than just a cursory glance at your credit report; it requires a deep dive into your financial habits and a commitment to improvement. The goal is to build a resilient credit profile that can withstand changes and continue to open doors to financial opportunities. Don’t wait until 2026 to start; the time to act is now, allowing ample time for any improvements to reflect on your report.
Essential steps to take now
Empower yourself by taking these practical steps to prepare for the credit score reforms:
Obtain and review your credit reports: Get free reports from AnnualCreditReport.com and check for errors. Dispute any inaccuracies immediately.
Monitor your credit score regularly: Utilize free credit monitoring services offered by many banks or credit card companies.
Reduce existing debt: Focus on paying down high-interest debt, especially credit card balances.
Establish a strong payment history: Set up automatic payments to ensure all bills are paid on time, every time.
Build an emergency fund: A financial cushion can prevent reliance on credit for unexpected expenses.
By consistently applying these strategies, you can build a strong foundation that will serve you well, regardless of how the credit scoring models evolve.
Expert Insights and Future Outlook
Financial experts widely agree that the 2026 credit score changes are part of a broader trend towards more nuanced and inclusive credit assessments. While the exact details of the new algorithms are still unfolding, the overarching goal appears to be a system that better differentiates between high and low-risk borrowers, potentially opening up credit access to a wider demographic while maintaining prudent lending standards. The focus is shifting from solely traditional data points to a more comprehensive view of financial behavior.
The future outlook suggests that adaptability will be key for consumers. Those who proactively manage their finances, understand the evolving criteria, and maintain healthy financial habits will be best positioned to thrive. The credit landscape is not static, and these changes underscore the importance of continuous financial literacy and engagement with one’s credit health.
What financial professionals are saying
Leading financial analysts emphasize the need for consumers to stay informed and proactive. They highlight that while some scores may fluctuate, the fundamental principles of responsible credit management will remain essential.
Emphasis on financial education: Understanding how scores are calculated.
Proactive credit monitoring: Regularly checking reports for accuracy.
Diversification of financial behavior: Not relying on just one aspect of credit.
The collective wisdom points towards a future where a holistic view of financial responsibility will be increasingly valued. The 2026 changes are not an end point, but rather a significant milestone in the ongoing evolution of credit scoring.
Key Aspect
Description of Impact
15-Point Shift
Potential increase or decrease in credit scores for many, influencing loan eligibility and rates.
Borrowing Power
Directly affects access to mortgages, auto loans, personal loans, and credit card terms.
Key Score Factors
Payment history, credit utilization, and length of credit will remain crucial, with potential re-weighting.
Frequently Asked Questions About 2026 Credit Score Changes
What are the main reasons for the 2026 credit score changes?▼
The changes aim to create more accurate and inclusive credit assessments. They seek to reduce bias, incorporate new data, and adapt to evolving consumer financial behaviors, reflecting a more modern view of creditworthiness for lenders.
Will my credit score definitely change by 15 points in 2026?▼
No, the 15-point shift represents a potential movement in either direction for many individuals. It’s not a guaranteed change for everyone, but rather an indication of the magnitude of fluctuation some consumers might experience based on their unique credit profiles.
How can I prepare my credit for the upcoming changes?▼
You can prepare by regularly checking your credit reports for errors, prioritizing on-time payments, keeping credit utilization low, and reducing existing debt. These fundamental practices will strengthen your credit profile for the new models.
What impact will these changes have on mortgage applications?▼
For mortgage applicants, the changes could affect interest rates, loan eligibility, and down payment requirements. A higher score might secure better terms, while a lower score could lead to less favorable conditions or even denial.
Are alternative data sources being considered in the new models?▼
Yes, there’s ongoing discussion and potential for alternative data sources, such as rent and utility payment histories, to be more prominently incorporated. This could benefit individuals with limited traditional credit but strong payment records in these areas.
Conclusion
The impending 2026 credit score changes represent a significant evolution in how financial institutions assess creditworthiness. With a potential 15-point shift affecting many, understanding and preparing for these modifications is not just advisable, but essential. By focusing on diligent credit management, monitoring your reports, and adapting to potential new scoring criteria, you can ensure your borrowing power remains strong. These changes underscore the dynamic nature of personal finance and the continuous need for financial literacy to navigate an ever-evolving economic landscape. Proactive engagement with your credit health today will undoubtedly pay dividends in the years to come.