FICO 10 T Updates: Optimize Your Credit Profile for 2026
Understanding and adapting to the latest FICO 10 T updates in early 2026 is crucial for optimizing your credit profile, ensuring better loan terms, and maintaining robust financial health in an evolving credit landscape.
By: Rafaela on September 23, 2026
Understanding and adapting to the latest FICO 10 T updates in early 2026 is crucial for optimizing your credit profile, ensuring better loan terms, and maintaining robust financial health in an evolving credit landscape.
As we approach early 2026, the financial landscape continues to evolve, with significant shifts in how creditworthiness is assessed. One of the most impactful changes on the horizon revolves around The Latest FICO 10 T Updates: How to Optimize Your Credit Profile in Early 2026. These updates are not merely minor tweaks; they represent a more sophisticated approach to evaluating consumer credit behavior, demanding a proactive strategy from anyone looking to secure favorable lending terms.
Understanding FICO 10 T: The Evolution of Credit Scoring
The introduction of FICO 10 T marks a pivotal moment in credit scoring, bringing with it a more granular and forward-looking assessment of consumer financial behavior. This new model is designed to provide lenders with a more accurate prediction of risk, incorporating trended data that offers a deeper insight into how individuals manage their credit over time, rather than just a snapshot.
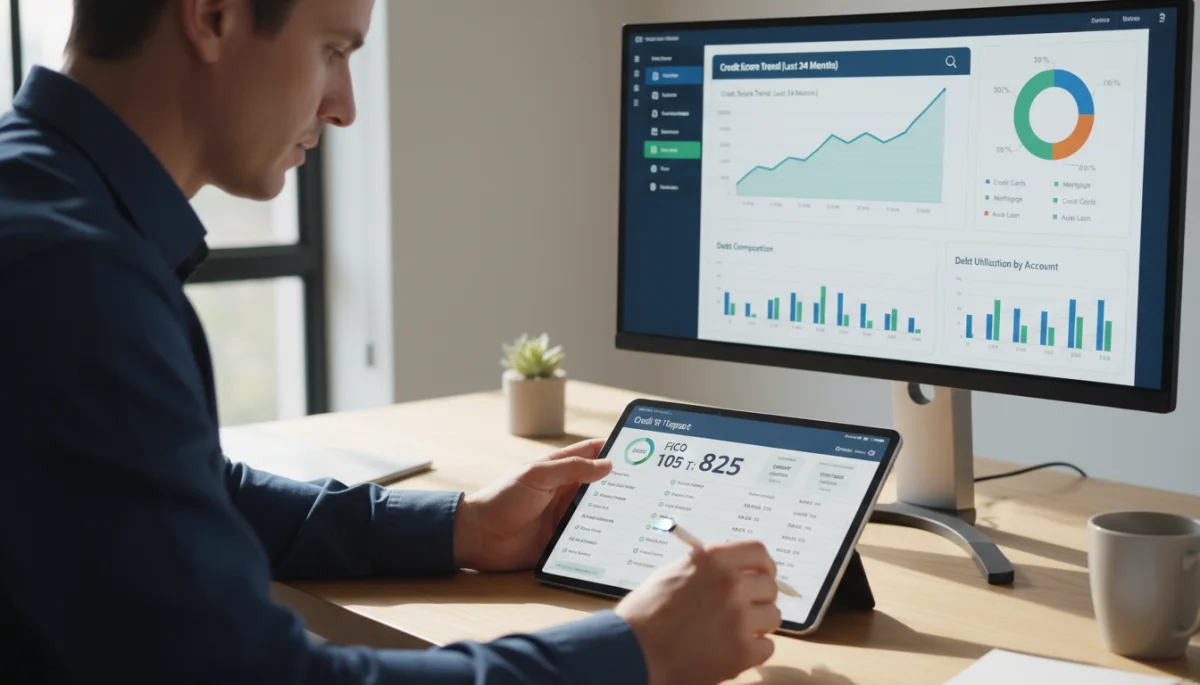
Unlike previous FICO models that primarily focused on current account status, FICO 10 T integrates up to 24 months of historical credit data. This ‘trended data’ includes information such as how much you’ve paid down on your credit card balances each month, your average utilization, and whether your balances generally increase or decrease. Lenders are particularly interested in this long-term view because it paints a clearer picture of financial habits and stability.
What is Trended Data and Why Does it Matter?
Trended data offers a dynamic perspective on your financial management. Instead of just seeing your current credit card balance, lenders can now observe if you consistently pay off your balance in full, make minimum payments, or let your balances accumulate. This information is crucial for assessing risk more precisely.
Payment History: Demonstrates consistent on-time payments or patterns of late payments over time.
Credit Utilization: Reveals whether you regularly carry high balances or effectively manage your credit limits.
Balance Trends: Shows if your debt is generally increasing, decreasing, or remaining stable.
Credit Mix: Evaluates your ability to manage different types of credit accounts responsibly.
Ultimately, FICO 10 T aims to differentiate between consumers who manage their credit effectively and those who might appear similar under older models but possess different underlying risk profiles. This means that even if you have a good current score, your long-term habits will now play a more significant role in your overall FICO 10 T score.
The shift to FICO 10 T is a significant development that demands attention from consumers. Understanding the underlying principles of trended data and how it impacts your score is the first step toward optimizing your credit profile for the coming changes. This model promises a more equitable, yet more demanding, evaluation of creditworthiness.
Key Changes in FICO 10 T: What to Expect
FICO 10 T is not just an incremental update; it introduces fundamental changes in how your credit score is calculated, with a particular emphasis on long-term financial behavior. These changes are designed to provide lenders with a more nuanced understanding of your credit risk, moving beyond simple snapshots to a comprehensive view of your financial journey.
One of the most notable aspects of FICO 10 T is its enhanced predictive power. By incorporating trended data, the model can better distinguish between high-risk and low-risk borrowers, potentially leading to more accurate lending decisions. This can benefit consumers with strong, consistent credit management, while those with volatile financial habits may see a negative impact.
Impact on Credit Utilization and Payment History
Under FICO 10 T, your credit utilization ratio—the amount of credit you use compared to your total available credit—will be scrutinized more closely over time. Consistently high utilization, even if paid off eventually, could be viewed less favorably than a consistent pattern of low utilization. Similarly, your payment history will be analyzed for trends, rewarding those who consistently pay on time and penalizing repeated late payments.
Revolving Credit Utilization: Frequent high balances, even if paid, could lower your score.
Installment Loan Payments: Consistent on-time payments on loans like mortgages and auto loans are highly valued.
Public Records: While still impactful, FICO 10 T aims to differentiate between one-off issues and ongoing financial distress.
New Credit Inquiries: The impact of new credit applications will still be considered, but the overall trend of your credit-seeking behavior will be more relevant.
Another area of focus for FICO 10 T is its ability to better handle adverse events. For instance, a single missed payment or a collection account might have a different weight under FICO 10 T if your overall trended data shows a strong recovery and consistent positive behavior afterward, compared to a pattern of ongoing financial struggles.
These changes mean that simply having a good score today might not be enough to maintain it under FICO 10 T. A sustained effort to manage your credit responsibly, focusing on consistent, positive financial habits, will be paramount. Understanding these nuances is key to adapting your strategy effectively.
Strategies for Optimizing Your Credit Profile
Optimizing your credit profile in anticipation of FICO 10 T updates requires a strategic and consistent approach. Given the model’s emphasis on trended data, short-term fixes will be less effective than establishing and maintaining healthy financial habits over an extended period. The goal is to demonstrate a consistent pattern of responsible credit management.
The foundation of a strong credit profile under FICO 10 T remains timely payments and responsible credit utilization. However, the ‘trended’ aspect means that merely avoiding late payments is not enough; you should aim for a pattern of paying on time, every time, and keeping your credit card balances low consistently.
Proactive Credit Management Techniques
To truly optimize your credit profile, consider these proactive steps that align with FICO 10 T’s focus on trended data:
Maintain Low Credit Utilization: Aim to keep your credit card balances below 10-20% of your available credit, not just at the statement closing date, but throughout the month.
Pay More Than the Minimum: Consistently paying more than the minimum due on your credit cards demonstrates strong financial discipline and a commitment to reducing debt.
Regularly Review Your Credit Reports: Check your credit reports from all three major bureaus (Equifax, Experian, TransUnion) for errors. Disputing inaccuracies can significantly impact your score.
Avoid Unnecessary New Credit: While new credit can sometimes be beneficial for your credit mix, avoid opening too many accounts in a short period, as this can signal higher risk.
Furthermore, managing your debt effectively is crucial. If you have multiple credit cards, consider focusing on paying down the card with the highest interest rate first, or the one with the highest balance, while making at least minimum payments on the others. This systematic approach can help reduce your overall debt burden and improve your utilization trends.
Optimizing your credit profile for FICO 10 T is an ongoing process that requires diligence and consistency. By focusing on responsible payment behaviors, low utilization, and regular monitoring, you can position yourself for a stronger credit standing in the evolving lending environment.
The Role of Payment History and Credit Utilization
In the world of FICO 10 T, payment history and credit utilization continue to be paramount, but their interpretation has gained a new layer of sophistication. Lenders will not just look at whether you paid on time last month; they will analyze the consistency and trends of your payments and usage over a significant period. This means a single late payment or a temporary spike in utilization might be less damaging if your overall trend is positive and quickly recovers.
This shift emphasizes the importance of sustained financial discipline. A sporadic approach to credit management, where good months are followed by poor ones, will likely be viewed less favorably than a steady, responsible pattern. This is particularly true for revolving credit accounts, where the month-to-month balance and payment behavior are now under the microscope.
Deep Dive into Payment Behavior
FICO 10 T will analyze whether you consistently make full payments, pay more than the minimum, or just pay the minimum. Consistently paying off your credit card balances in full or significantly reducing them each month will be a strong indicator of low risk. Conversely, consistently carrying high balances, even if you make minimum payments, could be detrimental.
Consistent On-Time Payments: The bedrock of a strong score; aim for a flawless record.
Reducing Balances Over Time: Demonstrates financial prudence and a commitment to debt reduction.
Avoidance of Collections/Charge-offs: These negative marks will still have a significant impact, especially if they are recent or part of a pattern.
Managing Revolving Debt: Actively working to keep revolving credit utilization low and balances manageable is key.
The model also considers how quickly you recover from any financial setbacks. If you miss a payment but quickly bring your account current and maintain good standing thereafter, the negative impact might be mitigated compared to someone who falls behind and stays behind for an extended period. This provides a degree of flexibility but still prioritizes overall consistency.
Ultimately, FICO 10 T reinforces the long-held wisdom that consistent, responsible credit behavior is the most effective way to build and maintain a strong credit score. The model’s focus on trends simply makes this truth more explicit and impactful.
Navigating New Lending Opportunities in 2026
As FICO 10 T becomes more widely adopted by lenders in early 2026, understanding its implications will be crucial for navigating new lending opportunities. Lenders will possess a more comprehensive and predictive tool, which means their criteria for approving loans and setting interest rates could become more precise, potentially benefiting well-qualified borrowers and challenging those with less consistent credit histories.
The enhanced predictive power of FICO 10 T may lead to more competitive interest rates for consumers who demonstrate excellent, consistent credit management. Conversely, those with fluctuating or less disciplined financial behavior might face higher rates or more stringent approval processes. This underscores the importance of proactive credit optimization.
How Lenders Will Utilize FICO 10 T
Lenders are expected to leverage FICO 10 T to gain a clearer picture of an applicant’s long-term risk profile. This could influence various lending decisions:
Mortgage Approvals: Lenders will look for stable, long-term credit behavior, making consistent payments and low utilization more critical.
Auto Loans: Similarly, a steady history of responsible credit use will likely lead to better terms.
Credit Card Offers: Issuers may tailor offers more precisely based on an applicant’s trended data, providing better rewards or lower APRs to those with superior long-term habits.
Personal Loans: The ability to demonstrate a consistent pattern of debt repayment will be a significant factor in approval and rate setting.
It’s important to remember that while FICO 10 T provides a more detailed view, it’s just one tool lenders use. Other factors, such as income, debt-to-income ratio, and overall financial stability, will still play a significant role. However, a strong FICO 10 T score will undoubtedly give you a considerable advantage in securing the best possible lending terms.
Preparing for FICO 10 T means focusing on sustainable financial practices. By consistently demonstrating responsible credit management, you can position yourself to take full advantage of the most favorable lending opportunities available in 2026 and beyond.
Common Misconceptions About FICO 10 T
With any significant update to a widely used financial tool like FICO, misconceptions are bound to arise. Understanding these can help consumers avoid pitfalls and focus on what truly matters for optimizing their credit profile under FICO 10 T. One common misunderstanding is that a single negative event will permanently tank your score, which isn’t necessarily true with the trended data approach.
Another frequent misconception is that FICO 10 T completely replaces all previous FICO models. While it is certainly a major advancement and will be adopted by many lenders, older FICO versions may still be in use for some time by various financial institutions. This means a good credit strategy should aim for overall financial health, not just optimizing for one specific model.
Debunking FICO 10 T Myths
Let’s clarify some common misunderstandings:
Myth: FICO 10 T only focuses on debt. Reality: While debt management is crucial, the model also considers positive trends like consistent payments and low utilization, rewarding responsible behavior.
Myth: All lenders will immediately switch to FICO 10 T. Reality: Adoption will be gradual. Some lenders may continue to use older models, making a holistic approach to credit health essential.
Myth: Closing old accounts will instantly improve your score. Reality: Closing old, paid-off accounts can sometimes negatively impact your credit utilization ratio and average age of accounts, potentially lowering your score.
Myth: Checking your credit score frequently will lower it. Reality: Checking your own score (a ‘soft inquiry’) does not affect your credit score. Hard inquiries, usually from loan applications, do.
It’s also a misconception that if you have a perfect credit history, you don’t need to pay attention to FICO 10 T. Even those with excellent credit can benefit from understanding how their trended data is viewed, ensuring they maintain their top-tier status. Small adjustments in spending or payment habits could further solidify their position.
By dispelling these myths, consumers can approach FICO 10 T with a clearer understanding of its mechanics and focus their efforts on genuine credit optimization strategies rather than misinformed tactics.
Future-Proofing Your Credit for 2026 and Beyond
Future-proofing your credit profile in the context of FICO 10 T and beyond involves more than just reacting to current changes; it requires a forward-thinking approach to personal finance. The emphasis on trended data means that consistent, positive financial habits established now will yield significant benefits in the long run, extending well past early 2026.
This proactive mindset includes continuous monitoring of your credit health, understanding how new financial products or behaviors might impact your score, and adapting your strategies as the credit landscape continues to evolve. It’s about building a resilient financial foundation that can withstand future changes.
Long-Term Credit Health Strategies
To ensure your credit profile remains strong and adaptable, consider these long-term strategies:
Automate Payments: Set up automatic payments for all your bills to ensure you never miss a due date, reinforcing a positive payment history trend.
Create and Stick to a Budget: A well-managed budget helps control spending, prevent over-indebtedness, and maintain low credit utilization.
Build an Emergency Fund: Having savings to cover unexpected expenses reduces the likelihood of relying on credit cards and accumulating high balances during crises.
Diversify Your Credit Mix Responsibly: While not a primary factor, a healthy mix of revolving and installment credit, managed well, can contribute positively to your overall profile.
Seek Professional Advice: If you’re struggling with debt or credit management, consider consulting with a certified financial advisor or credit counselor.
Remember that your credit score is a reflection of your overall financial health and discipline. By focusing on fundamental principles of sound money management, you not only improve your FICO 10 T score but also build a more secure financial future. The journey to an optimized credit profile is continuous, requiring dedication and informed decision-making.
Embracing these long-term strategies will not only prepare you for FICO 10 T but will also empower you to confidently navigate any future changes in credit scoring models, ensuring your financial readiness for years to come.
Key Aspect
Brief Description
Trended Data Focus
FICO 10 T analyzes up to 24 months of credit history, not just current snapshots.
Credit Utilization
Consistent low utilization and balance reduction are highly rewarded.
Payment History
Consistent on-time payments over time are crucial for a strong score.
Lending Decisions
Lenders will have a more precise risk assessment, impacting rates and approvals.
Frequently Asked Questions About FICO 10 T
What exactly is FICO 10 T and how does it differ from older FICO versions?▼
FICO 10 T is the latest credit scoring model that incorporates “trended data,” meaning it looks at your credit behavior over the past 24 months, not just a snapshot. This differs from older models by analyzing patterns in your credit utilization and payment history, offering lenders a more dynamic view of your financial habits.
Will FICO 10 T immediately replace all existing FICO scores?▼
No, FICO 10 T will not immediately replace all older FICO versions. While many lenders are expected to adopt it, especially for mortgages and auto loans, some may continue using older models for a transitional period. It’s best to maintain good credit habits across the board.
How can I improve my credit utilization under the FICO 10 T model?▼
To improve credit utilization for FICO 10 T, focus on consistently keeping your credit card balances low, ideally below 10-20% of your credit limit, throughout the month. Paying more than the minimum and reducing balances over time will demonstrate positive trends.
Does FICO 10 T penalize me for opening new credit accounts?▼
Opening new credit accounts still results in a hard inquiry, which can temporarily lower your score. FICO 10 T will analyze the trend of your new credit applications. Opening multiple accounts in a short period might signal higher risk, impacting your score more significantly than isolated inquiries.
What is the most important factor for a good FICO 10 T score?▼
The most important factor for a strong FICO 10 T score is consistent and responsible payment history combined with low credit utilization trends. Demonstrating a long-term pattern of on-time payments and effectively managing your debt over time will have the most significant positive impact on your score.
Conclusion
The advent of FICO 10 T in early 2026 marks a significant evolution in credit scoring, moving towards a more dynamic and trend-focused assessment of consumer creditworthiness. For individuals and businesses alike, understanding and adapting to these changes is not merely advantageous but essential for optimizing financial health and securing favorable lending terms. By prioritizing consistent, responsible credit management, maintaining low credit utilization, and diligently monitoring your credit profile, you can navigate this new landscape with confidence. The future of credit scoring demands proactive engagement, ensuring your financial habits align with the sophisticated evaluations of FICO 10 T and beyond.