Best Robo-Advisors for US Investors 2026: Fees & Performance
The best robo-advisors for US investors in 2026 offer automated investment management, balancing competitive fees with strong performance and personalized financial planning to meet diverse financial goals.
Navigating the complex world of investments can be daunting, but the rise of automated platforms has simplified the process for millions. For US investors looking to optimize their portfolios without the hefty fees of traditional advisors, understanding the best robo-advisors for US investors in 2026: a comparison of fees and performance is crucial. These digital platforms leverage advanced algorithms to manage your money, offering a streamlined path to financial growth.
Understanding the Robo-Advisor Landscape in 2026
The robo-advisor market has matured significantly, evolving from simple automated portfolios to sophisticated platforms offering personalized financial planning and advanced tax strategies. In 2026, these services are no longer just for beginners; they cater to a wide spectrum of investors, from those just starting their savings journey to high-net-worth individuals seeking efficient wealth management.
Technological advancements have allowed robo-advisors to integrate more seamlessly with other financial tools, providing a holistic view of one’s financial health. This integration helps investors make more informed decisions across their entire financial ecosystem, from budgeting to retirement planning.
Key Features of Modern Robo-Advisors
- Automated portfolio rebalancing to maintain target asset allocation.
- Tax-loss harvesting to minimize capital gains taxes.
- Goal-based planning for retirement, homeownership, or education.
- Access to human financial advisors for complex situations.
In essence, the modern robo-advisor in 2026 blends the efficiency of technology with the strategic insights that were once exclusive to traditional financial advisors. This hybrid approach offers a compelling value proposition for US investors seeking both convenience and expert guidance.
Evaluating Fees: What US Investors Can Expect
Fees are a critical factor when choosing a robo-advisor, directly impacting your net returns over time. In 2026, the fee structures have become increasingly transparent and competitive, with most platforms charging a percentage of assets under management (AUM).
While some robo-advisors offer commission-free trading for certain assets, the primary fee is typically an advisory fee. It’s essential to scrutinize not only this fee but also the expense ratios of the underlying exchange-traded funds (ETFs) or mutual funds within the portfolio. A seemingly low advisory fee can be offset by higher fund expenses.
Typical Fee Structures
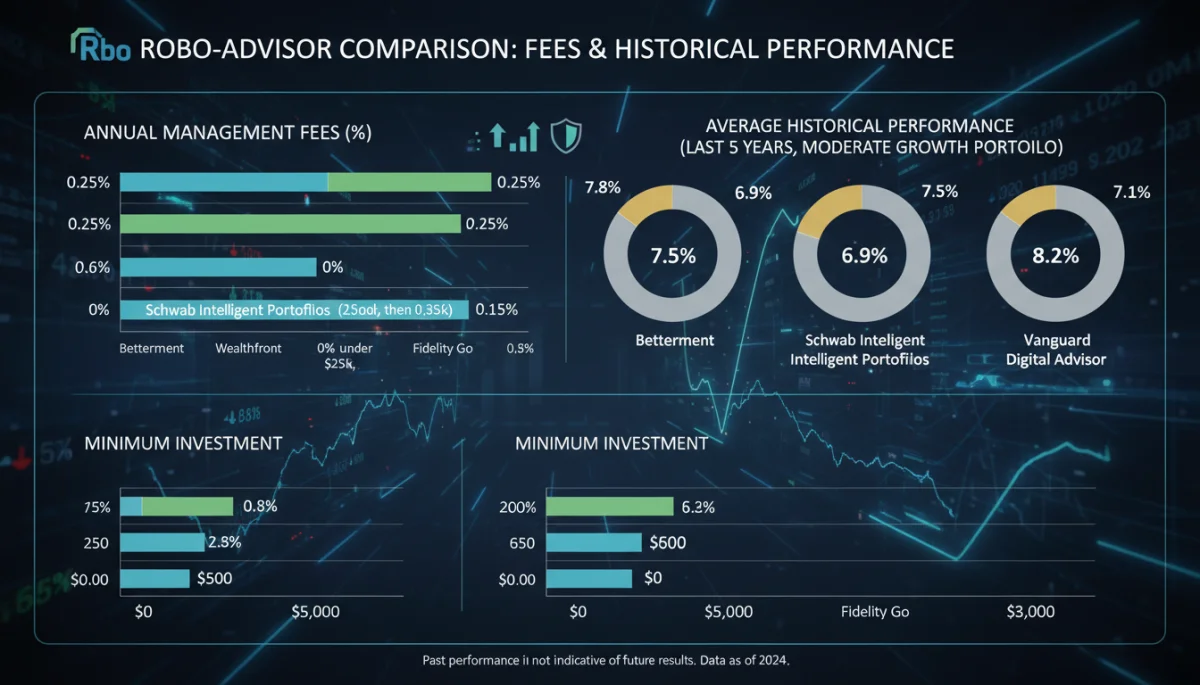
- Percentage of AUM: Ranging from 0.25% to 0.50% annually, often tiered based on asset size.
- Flat Fees: Less common but some platforms offer a fixed monthly or annual fee for specific services.
- Premium Services: Higher fees for access to human advisors, advanced planning, or specialized investment options.
It is crucial for US investors to compare these costs diligently. Even a small difference in fees can translate to tens of thousands of dollars over a lifetime of investing, especially with compounding returns. Understanding the total cost of ownership is paramount.
Performance Metrics and Investment Strategies
Assessing performance can be more nuanced than simply looking at past returns, as historical performance is not indicative of future results. However, understanding the investment philosophies and strategies employed by robo-advisors is key to evaluating their potential.
Most robo-advisors utilize modern portfolio theory (MPT), constructing diversified portfolios designed to maximize returns for a given level of risk. They typically invest in a mix of low-cost ETFs covering various asset classes, such as US equities, international equities, bonds, and real estate.
Some platforms differentiate themselves by offering socially responsible investing (SRI) options, cryptocurrency exposure, or access to alternative investments. These specialized options can cater to investors with specific values or those seeking further diversification beyond traditional assets.
Factors Influencing Performance
- Asset Allocation: The mix of stocks, bonds, and other assets based on your risk tolerance.
- Rebalancing Frequency: How often the portfolio is adjusted back to its target allocation.
- Tax-Loss Harvesting Efficiency: The ability to minimize taxes by selling investments at a loss.
- Underlying Fund Selection: The quality and expense ratios of the ETFs or mutual funds used.
Ultimately, the best-performing robo-advisor for you will depend on your individual risk profile, investment horizon, and financial goals. A thorough review of their methodologies and historical risk-adjusted returns, rather than just raw returns, provides a more comprehensive picture.
Top Robo-Advisors for US Investors in 2026: A Detailed Look
The competitive landscape of robo-advisors in 2026 features several strong contenders, each with unique strengths. We’ll delve into some of the leading platforms, highlighting their key features, fee structures, and typical investment approaches.
While some platforms are ideal for beginners due to their low minimums and intuitive interfaces, others cater to more experienced investors seeking advanced features or personalized human advice. The choice often comes down to balancing cost with the level of service and customization required.
Wealthfront: A Tech-Forward Approach
Wealthfront continues to be a favorite for tech-savvy investors. Known for its sophisticated automated tax-loss harvesting and diversified portfolios, it offers a compelling blend of performance optimization and low fees. Its Path financial planning tool provides a comprehensive overview of your financial future, integrating various accounts.
Fees are competitive, typically around 0.25% of AUM, making it an attractive option for those seeking robust automated management without excessive costs. Wealthfront’s focus on automation extends to its comprehensive suite of services, including cash accounts and portfolio lines of credit.
Betterment: Personalized and Flexible
Betterment stands out for its goal-based investing and flexible approach. Investors can set multiple financial goals, and Betterment tailors portfolios and advice to each specific objective. It offers both digital-only and premium plans with access to human advisors, providing scalability as your needs evolve.
Their fee structure generally ranges from 0.25% to 0.40% of AUM, depending on the service tier. Betterment’s commitment to personalized advice and its user-friendly interface make it a strong choice for investors who appreciate guidance alongside automation.
Fidelity Go: Integrated and Accessible
For investors already utilizing Fidelity’s ecosystem, Fidelity Go offers a seamless integration of automated investing. With a low minimum to start and no advisory fees for balances under a certain threshold, it’s highly accessible for new investors or those with smaller portfolios.
Above the minimum, advisory fees are competitive, often around 0.35% of AUM. Fidelity Go leverages Fidelity’s extensive research capabilities and diverse investment options, providing a reliable and well-supported robo-advisory experience.
Vanguard Digital Advisor: Low-Cost Indexing
Vanguard, a pioneer in low-cost indexing, extends its philosophy to its Digital Advisor service. It combines automated portfolio management with access to Vanguard’s renowned low-cost ETFs. This platform is particularly appealing to cost-conscious investors who value broad market exposure and passive investing.
Fees are among the lowest in the industry, often around 0.15% of AUM, making it an excellent option for long-term investors focused on minimizing costs. Vanguard Digital Advisor is ideal for those who prefer a straightforward, efficient, and cost-effective approach to automated investing.
Each of these platforms offers a distinct value proposition, and the best choice will ultimately align with an individual investor’s financial situation, risk tolerance, and service preferences.
The Role of Human Advice in an Automated World
While robo-advisors excel at automating portfolio management, the demand for human financial advice remains strong. In 2026, many leading platforms have adopted a hybrid model, combining the efficiency of algorithms with the personalized touch of human experts.
This hybrid approach is particularly beneficial for investors facing complex financial situations, such as estate planning, significant life changes, or intricate tax scenarios. A human advisor can provide nuanced guidance that goes beyond algorithmic recommendations.
Benefits of Hybrid Models
- Personalized Planning: Tailored advice for unique financial goals and life events.
- Emotional Support: Guidance during market volatility or personal financial crises.
- Comprehensive Strategies: Integration of investing with broader financial planning, including insurance and debt management.
The availability of human advisors, even if on an as-needed basis, adds a layer of comfort and expertise that purely automated platforms cannot replicate. Investors should consider whether they value this access and if the additional cost associated with hybrid models is justified for their needs.
Choosing the Right Robo-Advisor: Key Considerations
Selecting the ideal robo-advisor involves more than just comparing fees and performance. It requires a thoughtful evaluation of your personal financial situation, investment goals, and desired level of involvement. The right platform should align with your long-term objectives and provide the tools you need to succeed.
Consider your investment horizon: are you saving for retirement decades away, or a down payment in a few years? Your time horizon will influence the risk tolerance and asset allocation recommended by the robo-advisor. Moreover, assess your comfort level with technology and automated decision-making.
Factors to Consider
- Minimum Investment: Some platforms require higher initial deposits than others.
- Account Types: Ensure the platform supports the types of accounts you need (e.g., IRA, taxable brokerage, 529).
- Customer Support: Availability and quality of support channels (phone, chat, email).
- Educational Resources: The breadth and clarity of financial education materials provided.
- Security Measures: Robust security protocols and insurance (e.g., SIPC) to protect your assets.
Ultimately, the best robo-advisor for you in 2026 will be one that not only meets your financial objectives but also offers a user experience that you find intuitive and trustworthy. Take the time to research each option thoroughly, perhaps even trying out demo accounts if available, before committing your funds.
| Key Aspect | Description for US Investors |
|---|---|
| Fee Structures | Primarily AUM-based (0.15%-0.50%), with some flat fees or premium tiers. |
| Investment Strategies | Modern Portfolio Theory, low-cost ETFs, tax-loss harvesting, and goal-based planning. |
| Hybrid Models | Combination of automation and human advisor access for complex financial needs. |
| Selection Criteria | Minimums, account types, customer support, educational resources, and security. |
Frequently Asked Questions About Robo-Advisors
A robo-advisor is a digital platform that provides automated, algorithm-driven financial planning services with little to no human supervision. It works by collecting information about your financial situation and risk tolerance to create and manage a diversified investment portfolio, typically using low-cost ETFs.
Robo-advisors are suitable for many, especially those who are cost-conscious, comfortable with technology, and prefer a hands-off approach to investing. However, investors with highly complex financial situations or those who strongly prefer face-to-face interaction might benefit more from traditional or hybrid advisory services.
Robo-advisor fees are generally much lower, typically ranging from 0.15% to 0.50% of assets under management. Traditional financial advisors often charge 1% or more, plus potential commissions. The lower fees of robo-advisors can significantly impact long-term returns due to compounding.
Many advanced robo-advisors offer tax-loss harvesting, a strategy that sells investments at a loss to offset capital gains and potentially reduce taxable income. This feature can be a significant benefit for taxable accounts, helping to improve after-tax returns for investors.
Ensure the robo-advisor is regulated by the SEC and that your investments are protected by the SIPC (Securities Investor Protection Corporation) for up to $500,000. Look for strong encryption, two-factor authentication, and clear privacy policies to safeguard your personal and financial information.
Conclusion
The landscape of the best robo-advisors for US investors in 2026: a comparison of fees and performance reveals a dynamic and increasingly sophisticated market. These platforms offer an accessible, efficient, and often cost-effective way for individuals to manage their investments and work towards their financial goals. By carefully evaluating fee structures, understanding investment methodologies, and considering the availability of human advice, US investors can make an informed decision that aligns with their unique needs and aspirations. As technology continues to evolve, robo-advisors will undoubtedly play an even greater role in shaping the future of personal finance.
Related Posts: