2026 Auto Loan Rates: 0.75% Fluctuation Expected This Quarter
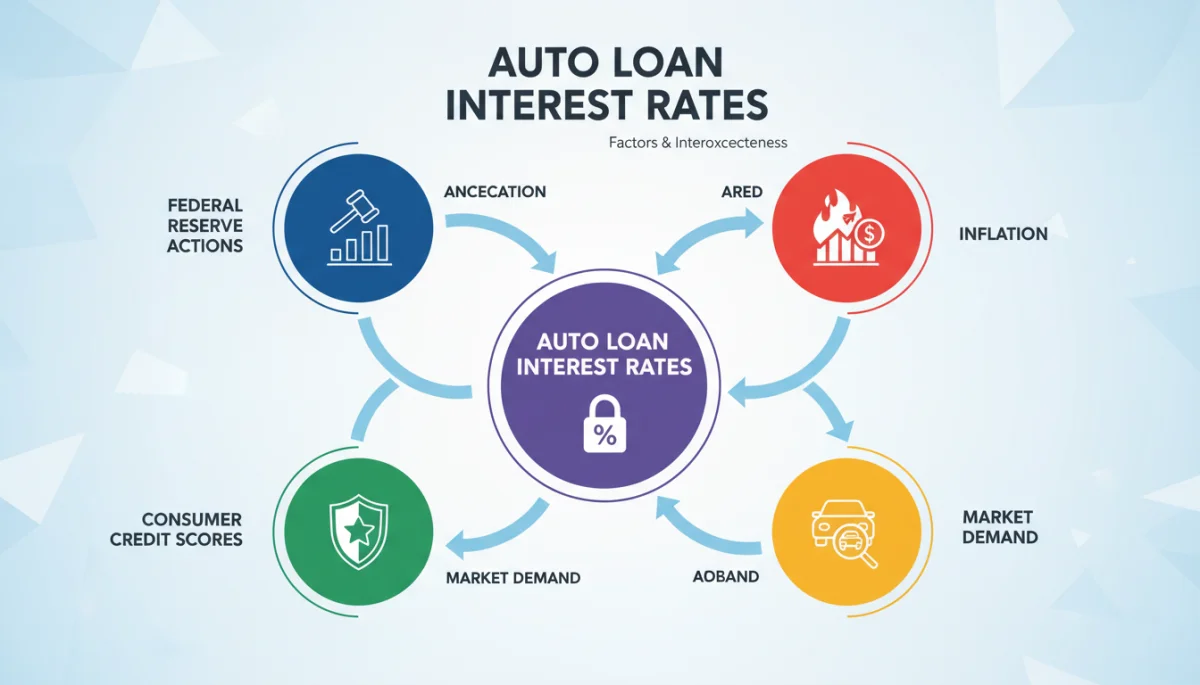
The 2026 outlook for auto loan interest rates anticipates a significant 0.75% fluctuation this quarter, influenced by Federal Reserve policies, inflation trends, and consumer demand, impacting prospective car buyers and the automotive market.
By: Rafaela on September 23, 2026
The 2026 outlook for auto loan interest rates anticipates a significant 0.75% fluctuation this quarter, influenced by Federal Reserve policies, inflation trends, and consumer demand, impacting prospective car buyers and the automotive market.
As we navigate the complexities of the financial landscape, understanding the 2026 outlook for auto loan interest rates: expecting a 0.75% fluctuation this quarter becomes crucial for anyone considering a vehicle purchase. This dynamic environment demands careful consideration, as even minor shifts can significantly impact the overall cost of car ownership. Prospective buyers and financial planners alike are closely monitoring these trends to make informed decisions.
Understanding the Current Economic Climate
The economic climate in early 2026 is a complex tapestry woven from various global and domestic threads. Inflationary pressures, although showing signs of moderation, remain a key concern for central banks, including the Federal Reserve. This ongoing battle against rising prices directly influences monetary policy, which in turn dictates the trajectory of borrowing costs across the board, including auto loans.
Geopolitical events continue to cast a shadow, creating uncertainty in supply chains and energy markets. These external factors can have ripple effects, impacting everything from manufacturing costs to consumer confidence. Domestically, employment figures and wage growth are closely watched indicators, providing insights into the health of consumer spending and their ability to take on new debt.
The Federal Reserve’s Stance
The Federal Reserve’s role as the primary architect of monetary policy is paramount in shaping interest rate expectations. Their decisions on the federal funds rate directly influence the prime rate, which banks use as a benchmark for various lending products, including auto loans. Analysts are scrutinizing every statement and economic projection from the Fed for clues regarding future rate adjustments.
Inflation Targeting: The Fed’s primary mandate is to maintain price stability, meaning they will continue to adjust rates to bring inflation back to their target levels.
Employment Data: Strong employment figures might give the Fed more leeway to maintain higher rates, while a weakening labor market could prompt a more dovish stance.
Economic Projections: The Fed’s quarterly economic projections, including GDP growth and inflation forecasts, offer valuable insights into their future policy direction.
In essence, the current economic climate is characterized by a delicate balance. The Fed aims to curb inflation without triggering a recession, making their policy decisions particularly impactful on auto loan rates. Consumers need to be aware of these overarching economic forces to anticipate potential changes.
Forecasting the 0.75% Fluctuation This Quarter
The prediction of a 0.75% fluctuation in auto loan interest rates this quarter is a significant development that warrants close attention. This forecast isn’t a random guess but rather an informed assessment based on a confluence of economic indicators and expert analysis. Such a shift, whether upward or downward, can have tangible consequences for both individual buyers and the broader automotive industry.
Several factors contribute to this anticipated volatility. Market sentiment, often influenced by daily news cycles and geopolitical events, plays a role. Investor confidence in the economy can impact bond yields, which in turn affect the cost of funds for lenders. Additionally, the actions of major financial institutions, as they adjust their lending strategies, can amplify or mitigate these fluctuations.
Key Drivers of Rate Volatility
Understanding the specific drivers behind this projected fluctuation is key to interpreting its potential impact. These aren’t isolated events but rather interconnected forces that collectively shape the lending landscape.
Federal Funds Rate Changes: Direct adjustments by the Federal Reserve to the federal funds rate are the most immediate and impactful driver of changes in auto loan rates.
Inflation Expectations: If inflation is expected to rise, lenders will demand higher interest rates to compensate for the erosion of purchasing power over time. Conversely, falling inflation could lead to lower rates.
Consumer Demand: A surge in demand for new vehicles could give lenders more leverage to charge higher rates, while a slowdown in demand might lead to more competitive offers.
Lender Competition: The competitive landscape among banks and credit unions can also influence rates. Fierce competition might drive rates down, even if other economic indicators suggest an increase.
The interplay of these factors creates a dynamic environment where rates can shift rapidly. For consumers, this means that the timing of a vehicle purchase could significantly affect the total cost of their loan. Staying informed about these drivers is crucial for making financially sound decisions in the current market.
Impact on Consumers and Car Buyers
The anticipated 0.75% fluctuation in auto loan interest rates in 2026 will undoubtedly have a direct and measurable impact on consumers and prospective car buyers. For many, financing a vehicle represents a substantial financial commitment, and even a seemingly small change in interest rates can translate into hundreds or even thousands of dollars over the life of a loan. This makes understanding the implications of these fluctuations paramount.
Higher interest rates mean a more expensive loan, leading to larger monthly payments and a greater total amount paid over time. This can reduce a buyer’s purchasing power, forcing them to consider less expensive vehicles or extend their loan terms, both of which have their own financial ramifications. Conversely, a decrease in rates could make car ownership more accessible and affordable, stimulating demand in the automotive market.
Strategies for Navigating Rate Changes
In a fluctuating interest rate environment, consumers need to adopt proactive strategies to secure the best possible financing terms. Preparedness and informed decision-making can significantly mitigate the negative effects of rising rates or maximize the benefits of falling rates.
Monitor Rates Closely: Stay updated on economic news and Federal Reserve announcements. Many financial websites and news outlets provide real-time updates on interest rate trends.
Improve Your Credit Score: A higher credit score consistently translates to lower interest rates. Paying bills on time and reducing existing debt can significantly improve your creditworthiness.
Shop Around for Lenders: Don’t settle for the first offer. Compare rates from multiple banks, credit unions, and online lenders to find the most competitive terms.
Consider Shorter Loan Terms: While monthly payments might be higher, shorter loan terms generally result in less interest paid over the life of the loan, especially in a rising rate environment.
Ultimately, the impact on consumers will vary based on their financial health, credit score, and how diligently they prepare for these rate changes. Those who are well-informed and proactive will be better positioned to navigate the evolving auto loan landscape in 2026.
The Role of Credit Scores in Auto Loan Rates
While macroeconomic factors like Federal Reserve policies and inflation undoubtedly shape the overall landscape of auto loan interest rates, an individual’s credit score remains a profoundly influential determinant of the rate they will ultimately receive. A strong credit history signals reliability to lenders, translating into more favorable terms, whereas a weaker score can lead to significantly higher borrowing costs.
Lenders use credit scores to assess the risk associated with lending money. A higher score indicates a lower risk of default, making the borrower more attractive. This allows lenders to offer lower interest rates, as they are more confident in the borrower’s ability to repay the loan. Conversely, a lower credit score suggests a higher risk, prompting lenders to charge higher rates to compensate for that increased risk.
Understanding Credit Score Tiers and Rates
Auto loan rates are often tiered based on credit scores, with different ranges qualifying for different rate brackets. It’s not uncommon for there to be several percentage points difference between the best rates offered to those with excellent credit and the rates for those with poor credit. This disparity can drastically alter the total cost of a vehicle.
Excellent Credit (780+): Typically qualifies for the lowest available interest rates, often advertised by dealerships and lenders.
Good Credit (670-779): Still receives competitive rates, though slightly higher than excellent credit. Offers good flexibility in loan terms.
Fair Credit (580-669): May face higher interest rates and potentially fewer loan options. Improving credit before applying is advisable.
Poor Credit (Below 580): Expect significantly higher interest rates and stricter loan conditions. Subprime lenders might be the only option, often with very high APRs.
Therefore, even with a general fluctuation of 0.75% in the market, the specific rate an individual receives will largely be tailored to their credit profile. Investing time in improving one’s credit score before applying for an auto loan can yield substantial long-term savings, regardless of broader market movements.
Alternative Financing Options and Strategies
In an environment where auto loan interest rates are expected to fluctuate by 0.75% this quarter, exploring alternative financing options and smart strategies becomes more important than ever. Relying solely on traditional dealership financing might not always yield the most favorable terms, especially for those sensitive to rate changes or with less-than-perfect credit. Diversifying your approach can lead to significant savings and greater financial flexibility.
One key strategy involves pre-approval from multiple lenders before even stepping onto a dealership lot. This not only gives you a clear understanding of the rates you qualify for but also provides leverage during negotiations. Dealerships often offer financing, but having an external offer in hand ensures you have a benchmark to compare against, preventing you from accepting an inflated rate.
Beyond Traditional Bank Loans
While banks are a common source for auto loans, several other avenues can offer competitive rates or more flexible terms, especially for specific situations.
Credit Unions: Often known for offering lower interest rates and more personalized service to their members, credit unions can be an excellent alternative for auto financing.
Online Lenders: A growing number of online platforms specialize in auto loans, providing quick application processes and competitive rates due to lower overheads.
Personal Loans: In some cases, a personal loan with a favorable interest rate might be an option, particularly for those with excellent credit and who prefer a more flexible repayment structure, though these are typically unsecured.
Additionally, considering a shorter loan term, if financially feasible, can dramatically reduce the total interest paid, even if the monthly payments are higher. Another strategy involves making a larger down payment, which reduces the amount borrowed and, consequently, the total interest accrued. By exploring these alternatives and implementing smart financial strategies, consumers can better navigate the anticipated fluctuations in 2026 auto loan rates.
Preparing for the Future: Tips for Prospective Buyers
With the 2026 outlook for auto loan interest rates expecting a 0.75% fluctuation this quarter, prospective car buyers need a robust strategy to navigate this dynamic market. Proactive planning can make a substantial difference in securing favorable financing and ultimately, in the total cost of vehicle ownership. Waiting until the last minute to consider financing options often puts buyers at a disadvantage.
One of the most critical steps is to thoroughly assess your personal financial situation. This involves understanding your budget, determining how much you can comfortably afford for a monthly car payment, and evaluating your current debt-to-income ratio. A clear picture of your finances will guide your car shopping and financing decisions, preventing you from overextending yourself.
Actionable Steps for Smart Car Financing
To effectively prepare for the evolving auto loan landscape, consider these actionable steps that can improve your position as a borrower.
Set a Realistic Budget: Factor in not just the car payment, but also insurance, maintenance, fuel, and potential registration fees. A holistic budget prevents financial strain later on.
Save for a Down Payment: A larger down payment reduces the loan amount, lowers your monthly payments, and can help you secure a better interest rate. Aim for at least 20% if possible.
Get Pre-Approved: Obtain pre-approvals from several lenders (banks, credit unions, online lenders) before visiting a dealership. This provides a benchmark rate and strengthens your negotiating power.
Understand Loan Terms: Pay close attention to the Annual Percentage Rate (APR), loan term (e.g., 36, 48, 60 months), and any hidden fees. A lower monthly payment over a longer term often means paying significantly more interest overall.
By taking these preparatory steps, prospective buyers can transform uncertainty into opportunity, ensuring they are well-equipped to make intelligent financing decisions in the face of fluctuating auto loan rates in 2026. Informed consumers are empowered consumers.
Key Point
Brief Description
0.75% Fluctuation
Experts anticipate auto loan rates will move by up to 0.75% this quarter in 2026, impacting borrowing costs.
Economic Drivers
Federal Reserve policy, inflation, and consumer demand are primary forces behind rate changes.
Consumer Impact
Fluctuating rates affect monthly payments, total loan cost, and purchasing power for car buyers.
Preparation is Key
Improving credit, budgeting, and comparing lenders are crucial strategies for navigating rate changes.
Frequently asked questions about 2026 auto loan rates
What is driving the anticipated 0.75% fluctuation in 2026 auto loan rates?▼
The projected fluctuation is primarily driven by the Federal Reserve’s monetary policy decisions, specifically their adjustments to the federal funds rate in response to inflation and economic growth. Global supply chain issues and changing consumer demand also play significant roles in shaping these interest rate movements.
How will a 0.75% rate change affect my monthly car payment?▼
A 0.75% change can significantly impact your monthly payment and total loan cost. For example, on a $30,000 loan over five years, a 0.75% increase could add roughly $10-15 to your monthly payment and hundreds of dollars over the loan term. The exact impact depends on the loan amount and duration.
Can my credit score mitigate the effects of rising auto loan rates?▼
Absolutely. A strong credit score is one of the most effective ways to secure lower interest rates, even in a fluctuating market. Lenders offer their best rates to borrowers with excellent credit, which can help offset any general market increases. Improving your credit can save you substantial money.
What steps should I take to prepare for these rate fluctuations?▼
Prospective buyers should focus on improving their credit score, saving for a larger down payment, and getting pre-approved for a loan from multiple lenders. Understanding your budget and comparing loan offers diligently are also crucial steps to navigate the changing rate environment effectively.
Are there alternatives to traditional bank auto loans?▼
Yes, credit unions often offer competitive rates to their members, and online lenders can provide quick approvals and favorable terms. Exploring personal loans as an option, particularly for those with excellent credit, might also be beneficial, though these are typically unsecured and may have different terms.
Conclusion
The anticipated 0.75% fluctuation in auto loan interest rates for 2026 underscores the dynamic nature of the financial market. While influenced by broad economic indicators such as Federal Reserve policy and inflation, individual preparedness through credit score improvement and diligent lender comparison remains paramount. Prospective car buyers who stay informed and employ proactive financial strategies will be best positioned to navigate these changes, ensuring optimal financing terms and a more affordable vehicle purchase. Understanding these trends isn’t just about saving money; it’s about making empowered decisions in a constantly evolving economic landscape.