Digital-Only Banks: Reshaping Your Banking Experience by 2026
Digital-only banks are rapidly transforming the financial landscape, promising a more streamlined, personalized, and technology-driven banking experience for consumers in the United States by 2026, challenging traditional models with innovative services.
By: Rafaela on September 23, 2026
Digital-only banks are poised to fundamentally reshape the banking experience by 2026, offering unprecedented convenience, innovative financial products, and highly personalized services directly through mobile platforms.
The financial world is undergoing a seismic shift, and at its epicenter is the rapid ascent of digital-only banks. By 2026, the question won’t be if you’ll encounter these innovative institutions, but how deeply they’ll integrate into and redefine your daily financial interactions. Get ready to explore how digital-only banks future will impact your banking experience.
The Evolution of Digital-Only Banking
Digital-only banks, often referred to as neobanks or challenger banks, operate entirely online, without the traditional brick-and-mortar branches that have long defined the banking industry. This model allows them to offer a leaner, more agile, and often more cost-effective service to their customers. Their rise is not a sudden phenomenon but the culmination of years of technological advancement and shifting consumer expectations.
The journey from traditional banking to fully digital platforms has been gradual, with internet banking and mobile apps paving the way. However, digital-only banks take this a step further, building their entire infrastructure from the ground up with technology at its core. This fundamental difference allows for unparalleled innovation and responsiveness to customer needs, setting them apart from the digital offerings of incumbent banks.
From Niche to Mainstream Adoption
Initially, digital-only banks were seen as niche players, appealing primarily to tech-savvy early adopters. However, their appeal has broadened considerably. Factors such as the COVID-19 pandemic, which accelerated the adoption of digital services across all demographics, have played a significant role in their mainstream acceptance.
Increased convenience: Banking from anywhere, anytime, without physical branch visits.
Lower fees: Reduced overhead often translates to fewer or no monthly maintenance fees.
Innovative features: Advanced budgeting tools, instant notifications, and personalized insights.
Accessibility: Catering to underserved populations with easy account setup and flexible options.
The evolution of digital-only banking signifies a paradigm shift in how consumers manage their money. It’s a move towards greater autonomy, transparency, and a more integrated financial experience that aligns with modern digital lifestyles. As we approach 2026, this trend is only set to intensify, making these banks a central pillar of the financial ecosystem.
Enhanced Convenience and Accessibility
One of the most compelling advantages offered by digital-only banks is the unparalleled level of convenience and accessibility they provide. Imagine managing all your financial needs from the palm of your hand, without ever needing to step foot into a physical branch or wait in line. This vision is not a distant future; it is the present reality for millions of users, and it will be even more prevalent by 2026.
These banks are designed with the mobile-first consumer in mind. Their applications are intuitive, user-friendly, and packed with features that simplify complex banking tasks. From opening an account in minutes to making instant transfers, paying bills, and even applying for loans, every service is optimized for digital interaction.
24/7 Access and Global Reach
The absence of physical branches means that digital-only banks can offer 24/7 access to services, regardless of time zones or geographical location. This is particularly beneficial for individuals with busy schedules, those who travel frequently, or expatriates needing to manage finances across borders. The global reach of these platforms is transforming how people interact with their money on an international scale.
Instant account setup: Open an account in minutes with just a smartphone and ID verification.
Real-time transactions: Send and receive money instantly, often without fees.
Global money transfers: Facilitate international payments with competitive exchange rates.
Personalized alerts: Receive instant notifications for all account activities.
The convenience extends beyond mere transactions. Many digital-only banks integrate with other financial tools and services, creating a holistic financial management ecosystem. This seamless integration means users can have a comprehensive view of their financial health, from budgeting to investments, all within a single app. This level of accessibility and control is fundamentally reshaping consumer expectations for banking services.
Innovative Services and Features
Beyond convenience, digital-only banks distinguish themselves through a relentless pursuit of innovation, offering a suite of services and features that often surpass those of traditional banks. These innovations are not just about making existing services digital; they are about reimagining what banking can be, leveraging cutting-edge technology to create entirely new value propositions for customers.
By 2026, expect these banks to be at the forefront of financial technology, integrating artificial intelligence (AI), machine learning (ML), and advanced data analytics to deliver highly personalized and proactive financial guidance. This means moving beyond simple transaction processing to offering predictive insights and tailored recommendations that genuinely help customers achieve their financial goals.
Personalized Financial Management Tools
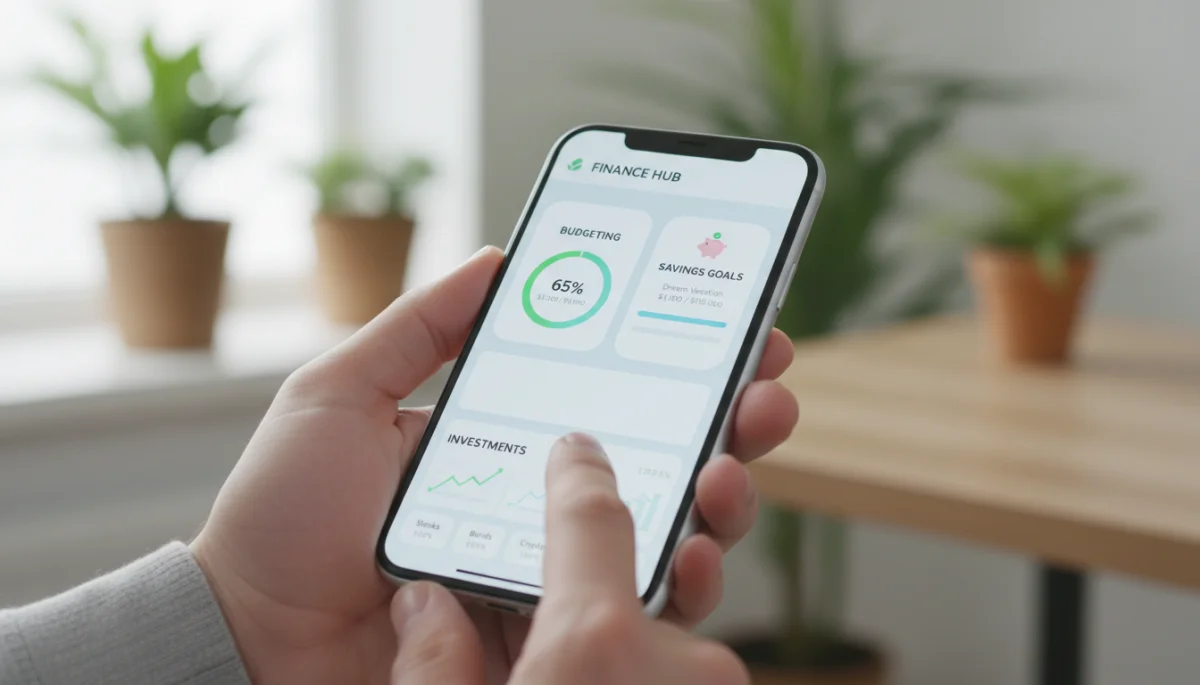
Many digital-only banks excel in providing sophisticated financial management tools that are often lacking in traditional banking platforms. These tools empower users to take greater control of their money, offering clear visibility into spending habits, savings progress, and investment performance.
Advanced budgeting: Categorize spending automatically and set custom budgets.
Savings goals: Create and track progress towards multiple savings targets with automated transfers.
Investment integration: Seamlessly link banking accounts with investment platforms for a unified view.
Credit building programs: Offer innovative solutions to help users improve their credit scores.
Furthermore, digital-only banks are pioneering new approaches to lending and credit. They often use alternative data points for credit assessments, making financial products accessible to a broader range of individuals who might be overlooked by traditional lenders. This focus on inclusivity, combined with personalized services, positions them as key players in democratizing financial access and fostering financial well-being.
Security and Trust in a Digital World
While the benefits of digital-only banks are clear, concerns about security and trust in a purely digital environment are naturally paramount for many consumers. By 2026, digital-only banks will have further solidified their security protocols, employing state-of-the-art encryption, multi-factor authentication, and advanced fraud detection systems to protect customer assets and data. These institutions understand that trust is their most valuable currency.
Many digital-only banks are federally insured, typically through the FDIC in the United States, providing the same level of protection for deposits as traditional banks. This regulatory oversight, combined with their technological prowess, aims to instill confidence in their users. They often invest heavily in cybersecurity, sometimes exceeding the capabilities of older, more complex traditional banking infrastructures.
Addressing Data Privacy Concerns
Data privacy is another critical aspect that digital-only banks are actively addressing. With the amount of personal and financial data they handle, ensuring its protection is non-negotiable. By 2026, expect even more robust data governance frameworks and transparent privacy policies from these institutions.
Advanced encryption: Protecting all data in transit and at rest.
Multi-factor authentication (MFA): Adding layers of security for account access.
Biometric login: Utilizing fingerprint and facial recognition for secure access.
Real-time fraud monitoring: Proactive systems to detect and prevent unauthorized activity.
The emphasis on security is not just about preventing breaches; it’s also about building a relationship of trust with their customers. Digital-only banks often have highly responsive customer support channels, including in-app chat and dedicated phone lines, to quickly address any security concerns or issues. This proactive and transparent approach to security and privacy is essential for their continued growth and acceptance in the financial landscape.
Impact on Traditional Banks and the Future Landscape
The rapid growth of digital-only banks is undeniably having a profound impact on traditional banking institutions. This competitive pressure is forcing established banks to accelerate their digital transformation efforts, invest heavily in technology, and rethink their customer engagement strategies. By 2026, the distinction between traditional and digital-only banks may become increasingly blurred as incumbents adopt more of the innovative features pioneered by their digital counterparts.
Traditional banks are responding by enhancing their mobile apps, streamlining online services, and sometimes even launching their own digital-first brands to compete directly. However, their legacy systems and extensive branch networks can sometimes hinder their agility compared to the unencumbered digital-only players. This dynamic is creating a more competitive and consumer-centric banking environment.
Collaboration and Coexistence
The future financial landscape is unlikely to be a zero-sum game. Instead, 2026 will likely see a blend of competition and collaboration between digital-only banks and traditional institutions. Partnerships could emerge where neobanks leverage the established infrastructure of traditional banks for certain services, while traditional banks adopt the innovative technologies and customer-centric approaches of digital challengers.
Increased digital offerings: Traditional banks will continue to improve their online and mobile platforms.
Hybrid models: Some traditional banks may offer distinct digital-only brands.
Strategic partnerships: Collaborations for technology sharing or specialized services.
Focus on niche markets: Banks, both digital and traditional, may specialize to cater to specific customer segments.
Ultimately, the impact of digital-only banks is pushing the entire industry towards greater efficiency, innovation, and customer focus. This evolution benefits consumers most, as they gain access to a wider array of banking options that are more tailored to their individual needs and preferences. The banking landscape of 2026 will be defined by this ongoing transformation, offering more dynamic and responsive financial services than ever before.
Choosing the Right Digital-Only Bank for You
With the proliferation of digital-only banks, selecting the right one can seem like a daunting task. By 2026, the market will offer an even wider array of choices, each with its unique strengths and target audience. The key to making an informed decision lies in understanding your personal financial needs and aligning them with the features and philosophy of a particular digital bank. Consider what matters most to you: low fees, high-yield savings, advanced budgeting tools, or specific lending options.
Begin by evaluating your typical banking activities. Do you primarily use your bank for everyday transactions, or are you looking for more sophisticated investment and savings tools? Your answers will help narrow down the field. Researching customer reviews and independent financial analyses can also provide valuable insights into a bank’s reliability and user experience.
Key Factors to Consider
When exploring digital-only banking options, a few critical factors should guide your decision-making process. These considerations ensure that the bank you choose not only meets your current needs but also supports your future financial aspirations.
Fees and charges: Look for transparency regarding monthly fees, ATM charges, and foreign transaction fees.
Interest rates: Compare interest rates on savings accounts and any lending products.
Features and tools: Evaluate budgeting apps, savings goals, investment integrations, and other unique offerings.
Customer support: Assess the availability and quality of support channels (chat, phone, email).
Security and insurance: Confirm FDIC insurance and robust security measures.
Ultimately, the best digital-only bank for you is one that simplifies your financial life, helps you achieve your goals, and provides a secure and reliable platform. Don’t hesitate to try out different options, as many digital banks offer easy account setup and no long-term commitments, allowing you to find the perfect fit for your evolving banking experience in 2026.
Key Aspect
Impact by 2026
Convenience
24/7 mobile access, instant transactions, global reach.
Forced to innovate, adopt digital features, potential for partnerships.
Frequently Asked Questions About Digital-Only Banks
What is a digital-only bank?▼
A digital-only bank, also known as a neobank or challenger bank, operates entirely online without physical branches. All services, from account opening to transactions and customer support, are conducted digitally, primarily through mobile apps and websites. They leverage technology to offer innovative financial products and services.
Are digital-only banks safe and secure?▼
Yes, most reputable digital-only banks are as safe and secure as traditional banks. Many are FDIC-insured, protecting your deposits up to the legal limit. They employ advanced security measures like encryption, multi-factor authentication, and real-time fraud detection to safeguard your accounts and personal information.
What are the main advantages of using a digital-only bank?▼
The primary advantages include enhanced convenience with 24/7 mobile access, often lower fees due to reduced overhead, and innovative features like advanced budgeting tools, instant notifications, and personalized financial insights. They also provide greater accessibility and a streamlined user experience.
How will digital-only banks change banking by 2026?▼
By 2026, digital-only banks will make banking more personalized, convenient, and technologically advanced. They will drive traditional banks to innovate further, leading to more integrated financial ecosystems, AI-driven advice, and a broader range of specialized financial products catering to diverse consumer needs.
Who should consider using a digital-only bank?▼
Anyone seeking a modern, convenient, and fee-efficient banking experience should consider a digital-only bank. They are particularly suitable for tech-savvy individuals, those who prefer managing finances on the go, or anyone looking for advanced budgeting tools and personalized financial guidance.
Conclusion
The rise of digital-only banks is not merely a trend; it’s a fundamental reshaping of the financial services industry. By 2026, these innovative institutions will have solidified their position as key players, offering a banking experience characterized by unparalleled convenience, cutting-edge technology, and a deep understanding of individual financial needs. While traditional banks adapt, the overall landscape will become more dynamic and consumer-centric, providing a wider array of choices and empowering individuals to manage their money with greater efficiency and insight. Embracing the future of digital banking means unlocking new possibilities for financial growth and well-being.