Best Robo-Advisors 2026: Fees & Performance for $5K Portfolios
Choosing the right robo-advisor for a $5,000 portfolio in 2026 involves a careful comparison of fees, investment strategies, and historical performance to maximize returns and minimize costs for new investors.
By: Rafaela on September 23, 2026
Choosing the right robo-advisor for a $5,000 portfolio in 2026 involves a careful comparison of fees, investment strategies, and historical performance to maximize returns and minimize costs for new investors.
Navigating the world of automated investing can be daunting, especially when starting with a modest sum. This article delves into the best robo-advisors for 2026: comparing fees and performance for $5,000 portfolios, offering clarity and actionable insights to help you make an informed decision for your financial future.
Understanding the Robo-Advisor Landscape in 2026
The financial technology sector continues its rapid evolution, with robo-advisors becoming an increasingly popular choice for investors seeking low-cost, automated portfolio management. In 2026, these platforms leverage sophisticated algorithms to construct and manage investment portfolios tailored to individual risk tolerances and financial goals, making professional-grade investing accessible to a broader audience.
For those with a $5,000 portfolio, the choice of a robo-advisor is critical. While many platforms cater to larger sums, several excel at serving smaller accounts, often waiving minimums or offering tiered fee structures that benefit emerging investors. Understanding their core functionalities and how they adapt to market conditions is paramount.
What Defines a Top Robo-Advisor?
A leading robo-advisor distinguishes itself through several key attributes. Beyond just low fees, it offers robust portfolio diversification, intuitive user experience, and strong customer support. The ability to adapt to market volatility and provide educational resources also plays a significant role in its overall value proposition.
Automated Portfolio Management: Rebalancing and diversification handled automatically.
Goal-Based Planning: Tools to help set and track financial objectives.
Tax-Loss Harvesting: Advanced strategies to minimize tax liabilities.
User-Friendly Interface: Easy-to-navigate platforms for all experience levels.
In essence, the best robo-advisors for a $5,000 portfolio in 2026 combine technological efficiency with a focus on investor empowerment, ensuring that even small investments are managed strategically and cost-effectively. Their continued innovation addresses the evolving needs of modern investors, from budgeting tools to advanced financial planning features.
Key Factors for $5,000 Portfolios: Fees and Minimums
When investing $5,000, fees can significantly impact your net returns. A seemingly small percentage can erode a substantial portion of your gains over time. Therefore, scrutinizing the fee structure is one of the most crucial steps in selecting a robo-advisor. Minimum investment requirements also play a pivotal role, as some platforms may have thresholds above $5,000.
Many robo-advisors have adjusted their models to be more accommodating to smaller accounts, recognizing the growing demand from new investors. Some even offer commission-free trading or fee waivers for balances below a certain amount, which can be a game-changer for a $5,000 portfolio.
Breaking Down Robo-Advisor Fees
Robo-advisor fees typically come in two main forms: advisory fees and expense ratios. Advisory fees are what the platform charges for managing your money, usually a percentage of assets under management (AUM). Expense ratios are embedded within the ETFs (Exchange Traded Funds) or mutual funds that make up your portfolio, representing the cost of operating those funds.
Advisory Fees: Ranging from 0.15% to 0.50% of AUM annually.
Expense Ratios: Typically between 0.05% and 0.25% annually.
Hidden Fees: Be aware of potential trading fees, rebalancing fees, or withdrawal fees, though these are less common with top-tier robo-advisors.
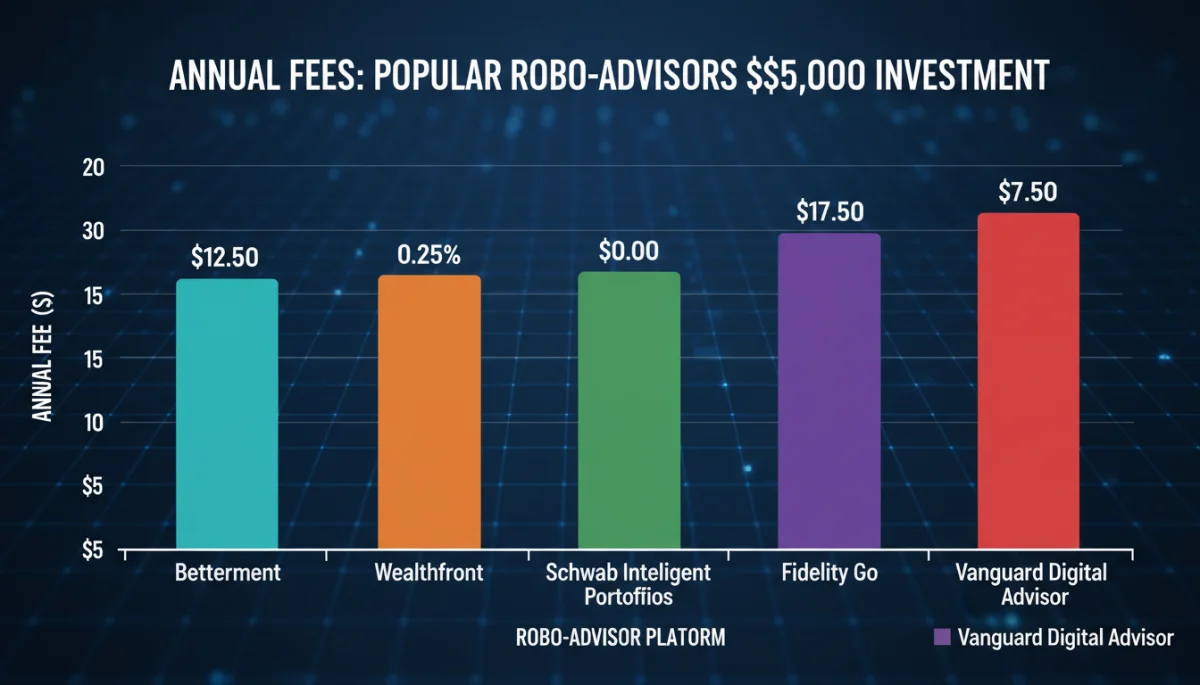
A $5,000 portfolio at a 0.25% advisory fee would cost $12.50 per year, plus the underlying ETF expense ratios. While this might seem minimal, every dollar saved is a dollar earned, especially in the early stages of investing. Platforms offering no advisory fees for small balances can provide a significant advantage, allowing your capital to compound more effectively.
Performance Metrics and Investment Strategies
Evaluating the performance of robo-advisors for a $5,000 portfolio requires looking beyond just raw returns. It’s essential to understand the underlying investment philosophy, asset allocation, and how each platform manages risk. Past performance is not indicative of future results, but it can offer insights into the robustness of their strategies.
Most robo-advisors employ modern portfolio theory (MPT), focusing on diversification across various asset classes like stocks, bonds, and sometimes real estate or commodities. Their algorithms determine an optimal asset mix based on your risk profile, which is usually assessed through a questionnaire.
Diversification and Risk Management
Diversification is the cornerstone of any sound investment strategy, and robo-advisors excel at implementing it automatically. By spreading your investment across different asset classes and geographies, they aim to reduce overall portfolio volatility while still pursuing growth. For a $5,000 portfolio, this means access to a broad market exposure that would be difficult to achieve manually.
Global Diversification: Exposure to U.S. and international equities and fixed income.
Asset Allocation: Portfolios tailored to conservative, moderate, or aggressive risk levels.
Rebalancing: Automated adjustments to maintain target asset allocations.
Understanding how a robo-advisor constructs its portfolios and manages risk is vital. Some may lean towards more aggressive growth portfolios, while others prioritize capital preservation. For a $5,000 investment, a balanced approach that provides exposure to growth while mitigating significant downside risk is often ideal.
Top Robo-Advisors for $5,000 Portfolios in 2026
Several robo-advisors stand out in 2026 for their suitability for $5,000 portfolios, balancing competitive fees with strong performance and user-friendly features. Each has its unique strengths, catering to different investor preferences and needs. It’s important to consider what matters most to you: lowest fees, specific investment options, or access to human advisors.
We’ve analyzed platforms that offer low or no account minimums, transparent fee structures, and proven investment methodologies. These platforms often provide excellent educational resources, which are particularly beneficial for new investors starting with a smaller sum.
Detailed Look at Leading Options
For instance, one prominent robo-advisor might offer a zero-fee structure for balances under a certain threshold, making it highly attractive for an initial $5,000 investment. Another might have slightly higher fees but provide access to a wider range of socially responsible investing (SRI) options or even fractional shares, allowing for greater diversification with less capital.
Robo-Advisor A: Known for zero advisory fees on small balances and robust tax-loss harvesting.
Robo-Advisor B: Offers access to human advisors for a slightly higher fee, ideal for those who want a hybrid approach.
Robo-Advisor C: Specializes in socially responsible investing (SRI) portfolios with competitive expense ratios.
When selecting from these top contenders, consider not only the fees and performance but also the overall user experience, the quality of customer support, and any additional features that align with your long-term financial objectives. The best choice is ultimately the one that best fits your individual investment philosophy and comfort level.
Integrating Human Advice: Hybrid Models
While the appeal of fully automated investing is strong, some investors, even with a $5,000 portfolio, may appreciate the option of human guidance. Hybrid robo-advisors in 2026 blend the efficiency and cost-effectiveness of algorithms with the personalized touch of a human financial advisor. This model can be particularly reassuring for those who are new to investing or facing complex financial decisions.
For a $5,000 investment, access to a human advisor might seem like an expensive luxury. However, many hybrid models offer tiered services, where a limited number of consultations or specific financial planning sessions are included for a slightly higher, but still competitive, fee. This can provide invaluable peace of mind and strategic direction.
Benefits of a Hybrid Approach
The primary advantage of a hybrid model is the ability to consult with a certified financial planner (CFP) when needed, without incurring the high costs of traditional wealth management. These advisors can help with more intricate financial planning aspects, such as retirement planning, college savings, or estate planning, which algorithms alone might not fully address.
Emotional Support: Guidance during market downturns, preventing impulsive decisions.
Complex Situations: Assistance with unique financial circumstances or goals.
For an investor with a $5,000 portfolio, a hybrid model can offer a valuable safety net and educational resource. It allows you to leverage the best of both worlds: automated efficiency for day-to-day portfolio management and expert human insight for critical decisions, ensuring your investment journey is well-supported.
Maximizing Your $5,000 Portfolio: Tips and Strategies
Starting with $5,000 is an excellent first step towards building wealth, and there are several strategies you can employ to maximize the potential of your robo-advised portfolio. Beyond simply choosing the right platform, consistent contributions, understanding compounding, and regular review of your financial goals are crucial for long-term success.
Even small, regular contributions can significantly boost your portfolio’s growth over time, thanks to the power of dollar-cost averaging. This strategy involves investing a fixed amount regularly, regardless of market fluctuations, which can reduce risk and potentially increase returns over the long run.
Smart Investing Practices for Small Portfolios
One of the most effective ways to grow a $5,000 portfolio is to commit to consistent, automatic contributions. Setting up a recurring transfer of even $50 or $100 per month can make a substantial difference. This not only adds to your principal but also allows your investments to benefit from compounding returns more effectively.
Automate Contributions: Set up recurring deposits to ensure consistent growth.
Reinvest Dividends: Allow any dividends or interest earned to be reinvested back into your portfolio.
Monitor and Adjust: Periodically review your portfolio and financial goals, making adjustments as needed.
Stay Informed: Continue to learn about investing and personal finance to make better decisions.
Remember that investing is a long-term game. While starting with $5,000 might seem small, the discipline of consistent contributions and smart strategy selection through a well-chosen robo-advisor can lead to significant wealth accumulation over the decades. Focus on what you can control: your savings rate, your investment costs, and your long-term perspective.
Key Aspect
Brief Description
Fee Structures
Annual advisory fees (0.15%-0.50% AUM) and ETF expense ratios (0.05%-0.25%) are crucial for a $5K portfolio.
Minimum Investments
Many top robo-advisors offer $0 minimums or low thresholds, ideal for starting with $5,000.
Investment Strategies
Algorithms apply Modern Portfolio Theory, focusing on global diversification and risk management.
Hybrid Options
Some platforms offer access to human advisors for a blend of automation and personalized guidance.
Frequently Asked Questions About Robo-Advisors
Are robo-advisors safe for a $5,000 investment?▼
Yes, robo-advisors are generally safe. They are regulated financial institutions, often SIPC-insured, protecting your investments up to $500,000. Your funds are held by custodians, not directly by the robo-advisor, adding an extra layer of security for your $5,000 portfolio.
Can I lose money with a robo-advisor?▼
Yes, all investments carry inherent risks, and it’s possible to lose money with a robo-advisor. They invest in market-traded securities, which fluctuate in value. Robo-advisors aim to mitigate risk through diversification, but market downturns can still impact your $5,000 portfolio.
Do robo-advisors offer tax-loss harvesting for small portfolios?▼
Many leading robo-advisors offer tax-loss harvesting, even for smaller portfolios like $5,000. This strategy involves selling investments at a loss to offset capital gains and potentially reduce taxable income, automatically implemented by the platform to optimize your tax efficiency.
What is the typical return on a $5,000 robo-advised portfolio?▼
Returns vary significantly based on market conditions, your risk tolerance, and the specific portfolio allocation. While past performance is not a guarantee, diversified portfolios often target average annual returns of 5-8% over the long term, though short-term fluctuations are common.
How often should I check my robo-advisor account?▼
For a $5,000 portfolio managed by a robo-advisor, it’s generally best to check periodically, perhaps quarterly or semi-annually, rather than daily. Over-monitoring can lead to emotional decisions. Focus on long-term goals and let the automation work, only making adjustments if your financial situation changes.
Conclusion
Choosing the right robo-advisor for your $5,000 portfolio in 2026 is a strategic decision that can significantly impact your financial growth. By carefully comparing fees, understanding investment strategies, and considering the benefits of hybrid models, investors can find a platform that aligns with their goals and risk tolerance. The key is to prioritize low costs, effective diversification, and a user-friendly experience, ensuring your initial investment is set on a path for long-term success and wealth accumulation. With the right tools and consistent effort, even a modest starting capital can achieve substantial returns over time.