Annuities in 2026: Insider Knowledge for US Retirement Savers
Annuities offer a unique blend of guaranteed income and tax-deferred growth, making them a cornerstone for many US retirement savers in 2026, providing financial security and peace of mind.
By: Rafaela on September 23, 2026
Understanding annuities in 2026: insider knowledge for US retirement savers is crucial for securing guaranteed income and tax-deferred growth, offering a vital component in comprehensive retirement planning strategies.
Are you a US retirement saver looking to fortify your financial future? Navigating the complex landscape of retirement planning requires insight, and understanding annuities in 2026: insider knowledge for US retirement savers can be a game-changer. Annuities, often misunderstood, offer a powerful tool to ensure a steady income stream in your golden years, protecting you from market volatility and longevity risk. This article will demystify annuities, providing you with the essential information to make informed decisions for your financial well-being.
The evolving landscape of annuities in 2026
The financial world is constantly shifting, and annuities are no exception. In 2026, we see new features, regulations, and product innovations designed to meet the diverse needs of an aging population. Staying informed about these changes is paramount for anyone considering an annuity as part of their retirement portfolio. The market is more competitive, leading to a wider array of options than ever before.
Understanding these developments helps you choose an annuity that aligns with your specific financial goals and risk tolerance. It’s not just about finding a product; it’s about finding the right product for your unique situation, considering factors like interest rates, inflation, and your expected retirement lifestyle.
Regulatory updates and consumer protection
Recent years have brought significant regulatory scrutiny to the annuity market, primarily aimed at enhancing consumer protection. In 2026, these regulations continue to evolve, ensuring greater transparency and suitability standards for annuity sales. This means advisors are held to higher standards when recommending annuity products.
Best interest standard: Advisors must act in the client’s best interest, not just suitability.
Enhanced disclosure requirements: Clearer explanations of fees, surrender charges, and riders.
Fiduciary duty emphasis: A growing focus on advisors acting as fiduciaries for their clients.
These regulatory shifts are designed to build trust and ensure that consumers fully comprehend the intricacies of their annuity contracts. They empower you to ask more informed questions and demand greater clarity from your financial professional, ultimately leading to better outcomes.
Technological advancements and accessibility
Technology is transforming how annuities are bought and managed. Digital platforms are making it easier for consumers to research, compare, and even purchase annuities online. This increased accessibility, combined with advanced analytical tools, allows for more personalized product recommendations.
The integration of AI and data analytics helps providers tailor annuity solutions to individual financial profiles, making the selection process less daunting. This technological leap benefits consumers by offering more choices and greater convenience, while still emphasizing the importance of professional guidance.
The landscape of annuities in 2026 is one of innovation and increased protection. These changes are positive for US retirement savers, providing more robust options and a safer environment for making crucial financial decisions. Staying abreast of these developments is key to leveraging annuities effectively.
Decoding the different types of annuities
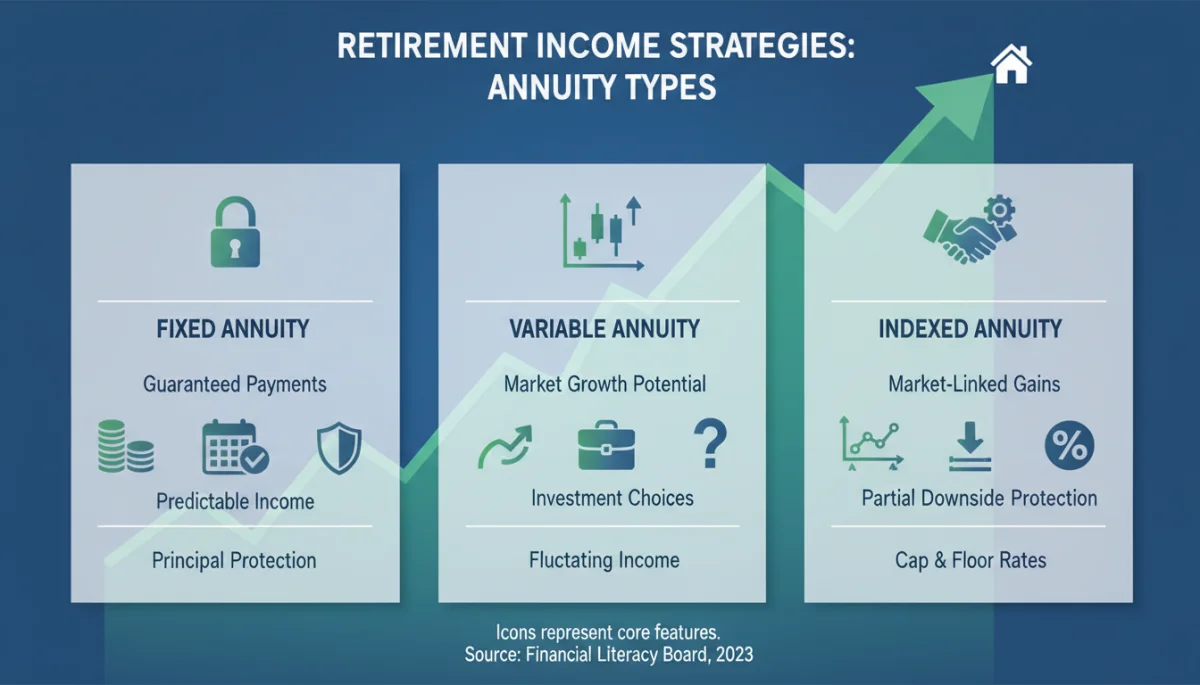
Annuities aren’t a one-size-fits-all solution; they come in various forms, each with distinct features and benefits. Knowing the differences between these types is fundamental to selecting the annuity that best fits your retirement strategy. The choice often depends on your risk tolerance, income needs, and time horizon.
The primary classifications include fixed, variable, and indexed annuities, but within these categories, there are numerous variations and riders that can customize a product to your exact specifications. Understanding these nuances is where the ‘insider knowledge’ truly comes into play for US retirement savers.
Fixed annuities: stability and predictability
Fixed annuities offer a guaranteed interest rate for a set period, providing predictable growth and income. They are often favored by those seeking security and a conservative approach to their retirement savings, similar to a certificate of deposit but with tax-deferred growth.
These annuities are ideal for individuals who prioritize capital preservation and a steady, reliable income stream in retirement. The interest rate is declared upfront and remains constant, offering peace of mind even during market downturns. This predictability makes them a strong foundational component for a diversified retirement portfolio.
Variable annuities: growth potential with market exposure
Variable annuities allow your money to be invested in sub-accounts that resemble mutual funds, offering the potential for higher returns but also exposing you to market risk. These are suitable for savers comfortable with some volatility in exchange for growth potential.
While variable annuities come with higher fees, they often include optional riders that can provide guaranteed income or protect against market losses, even if the underlying investments perform poorly. It’s crucial to understand the fees and the specific guarantees offered before committing to a variable annuity.
Indexed annuities: a blend of security and growth
Indexed annuities, also known as fixed-indexed annuities, offer a middle ground between fixed and variable options. Their returns are linked to a market index, like the S&P 500, but typically include a floor to protect against losses and a cap on potential gains. This provides a balance of growth potential and capital protection.
These annuities appeal to those who want some exposure to market upside without the full risk of direct market participation. They can be a good choice for individuals seeking moderate growth with a strong emphasis on preserving their principal, making them increasingly popular for retirement planning in 2026.
Choosing the right type of annuity requires careful consideration of your financial situation, risk tolerance, and retirement goals. Each type serves a different purpose, and a well-informed decision can significantly impact your financial security in retirement.
Benefits of incorporating annuities into your retirement plan
Annuities offer several compelling advantages that make them a valuable component of a comprehensive retirement plan, particularly for US retirement savers. These benefits extend beyond simple investment growth, addressing crucial aspects of financial security in later life. Understanding these benefits can help you appreciate the role annuities play.
From guaranteed income to tax advantages, annuities provide a layer of protection and predictability that other investment vehicles might not. They are designed to address some of the most significant concerns retirees face, such as outliving their savings or navigating market downturns.
Guaranteed income for life
One of the most attractive features of many annuities is the ability to provide a guaranteed income stream for life. This is often referred to as ‘longevity insurance,’ as it protects you from the risk of outliving your savings. Knowing you will have a steady income, regardless of market performance, offers immense peace of mind.
Predictable cash flow: Helps cover essential living expenses in retirement.
Longevity protection: Ensures income lasts as long as you do.
Reduced financial stress: Less worry about market fluctuations impacting your income.
This guaranteed income can be a cornerstone of your retirement budget, allowing you to plan with greater certainty and confidence. It’s a key reason why many financial advisors recommend annuities to their clients.
Tax-deferred growth
Annuities offer tax-deferred growth, meaning you don’t pay taxes on the earnings until you withdraw the money. This allows your investments to compound more rapidly over time, potentially leading to a larger sum for retirement. This tax advantage is a significant benefit for long-term savers.
Unlike other investment accounts where you might pay taxes annually on dividends or capital gains, annuities allow your money to grow untouched by taxes until you start taking distributions. This can be particularly advantageous for individuals in higher tax brackets during their working years.
Customizable features and riders
Modern annuities come with a wide array of customizable features and riders that can be added to tailor the contract to your specific needs. These riders can offer benefits such as enhanced death benefits, guaranteed minimum withdrawal benefits, or inflation protection.
While riders often come with additional fees, they can provide valuable protections and flexibility, making the annuity a more robust tool for your retirement planning. It’s important to carefully evaluate which riders are truly necessary and cost-effective for your individual circumstances.
The benefits of annuities, from guaranteed income to tax advantages and customization, highlight their potential as a powerful tool for US retirement savers. When strategically integrated into a broader financial plan, they can significantly enhance your financial security and peace of mind.
Understanding the potential risks and drawbacks
While annuities offer many benefits, it’s equally important for US retirement savers to understand their potential risks and drawbacks. Like any financial product, annuities are not without their complexities and potential downsides. A thorough understanding of these aspects ensures you make a fully informed decision.
Ignoring these risks can lead to unexpected challenges down the line. It’s crucial to weigh the advantages against the disadvantages to determine if an annuity truly aligns with your financial philosophy and retirement objectives. Transparency about these factors is a hallmark of good financial advice.
Liquidity limitations and surrender charges
One of the primary drawbacks of annuities is their limited liquidity. Annuity contracts typically include a surrender period, which can last several years, during which withdrawing funds beyond a certain percentage can incur significant surrender charges. These charges are designed to compensate the insurance company for the commission paid to the agent and other administrative costs.
This means that while your money is growing, it might not be easily accessible without financial penalty. For this reason, annuities are generally best suited for funds you don’t anticipate needing for immediate expenses or emergencies. It’s essential to have an emergency fund separate from your annuity investments.
Fees and expenses
Annuities, especially variable annuities and those with numerous riders, can come with a variety of fees and expenses. These can include administrative fees, mortality and expense risk charges, underlying fund expenses, and rider fees. These costs can eat into your returns over time.
It’s vital to meticulously review all fee structures before purchasing an annuity. A clear understanding of how these costs impact your overall return is crucial. While some fees are standard, excessive fees can significantly diminish the value of your annuity, making it less effective as a retirement vehicle.
Inflation risk
For annuities that offer fixed payments, inflation can erode the purchasing power of your income over time. A fixed income stream that seems adequate today might not cover your living expenses two or three decades into retirement if inflation is high.
Some annuities offer inflation protection riders, but these typically come at an additional cost. When considering a fixed annuity, it’s important to factor in the potential impact of inflation and explore options that help mitigate this risk, ensuring your income maintains its value throughout your retirement.
Understanding the risks and drawbacks associated with annuities is just as important as knowing their benefits. By being aware of liquidity limitations, various fees, and inflation risk, US retirement savers can approach annuity decisions with greater caution and make choices that truly serve their long-term financial health.
Strategic integration: fitting annuities into your broader financial plan
Integrating annuities effectively into your overall financial plan requires careful thought and strategic planning. Annuities should not be viewed in isolation but as one component of a diversified portfolio designed to meet specific retirement goals. This holistic approach ensures all your financial instruments work in concert.
For US retirement savers, the key is to determine how annuities complement existing savings, investments, and other income sources. This often involves working with a qualified financial advisor who can assess your entire financial picture and recommend the most suitable strategy.
Balancing guaranteed income with growth investments
A common strategy is to use annuities to cover essential living expenses in retirement, providing a guaranteed income floor, while other investments, such as stocks and bonds, are used for growth potential and discretionary spending. This approach creates a balanced portfolio that combines security with upside potential.
By segmenting your retirement funds in this manner, you can reduce the pressure on your growth investments to perform consistently, allowing them to weather market downturns without impacting your ability to cover basic needs. This balanced approach is highly recommended for long-term financial stability.
Considering your overall risk tolerance
Your personal risk tolerance plays a significant role in determining the type and amount of annuity suitable for your plan. If you are highly risk-averse, fixed annuities or indexed annuities with strong principal protection might be more appealing. Those comfortable with more risk might explore variable annuities for higher growth potential.
It’s crucial that your annuity choices align with your comfort level regarding market fluctuations and potential losses. A financial plan that causes undue stress is unlikely to be sustainable. Your advisor should help you quantify your risk tolerance and match it with appropriate annuity solutions.
Working with a financial advisor
Given the complexity of annuities and the myriad of options available, working with a qualified financial advisor is highly recommended. An advisor can help you:
Assess your needs: Determine your income needs, risk tolerance, and financial goals.
Compare products: Navigate the vast market to find suitable annuity products.
Understand contracts: Explain the fine print, fees, and riders in plain language.
Integrate into plan: Ensure the annuity fits seamlessly into your overall retirement strategy.
A knowledgeable advisor acts as a guide, providing invaluable expertise and helping you avoid common pitfalls. Their objective perspective can be instrumental in making smart, long-term decisions about annuities for your retirement.
Strategic integration of annuities involves balancing guaranteed income with growth, aligning with your risk tolerance, and leveraging professional guidance. This comprehensive approach ensures that annuities serve as a powerful and appropriate tool within your broader financial strategy for a secure retirement.
Future trends and innovations in annuities for 2026 and beyond
The annuity market is not static; it continues to evolve with new products and features designed to meet the changing demands of US retirement savers. Looking ahead to 2026 and beyond, several trends and innovations are poised to shape the future of annuities, making them even more versatile and appealing.
These advancements reflect a growing understanding of retiree needs, technological capabilities, and the desire for greater flexibility and personalization. Staying informed about these emerging trends can help you anticipate future opportunities and make forward-thinking financial decisions.
Personalized annuity solutions
Expect to see a greater emphasis on personalized annuity solutions. Advances in data analytics and artificial intelligence will allow insurance companies to offer highly customized products tailored to individual health, lifestyle, and financial profiles. This means annuities that adapt more closely to your unique retirement journey.
These personalized options could include dynamic income adjustments based on health changes, or investment strategies within variable annuities that automatically rebalance based on your evolving risk capacity. The goal is to move away from generic products towards solutions that truly reflect individual circumstances.
Hybrid annuity products
The market is likely to see an increase in hybrid annuity products that combine features from different annuity types or integrate with other financial products. For example, annuities that blend long-term care benefits with guaranteed income are becoming more common, offering a comprehensive solution for multiple retirement concerns.
These hybrid products aim to provide greater efficiency and convenience, addressing several needs within a single contract. They can simplify financial planning by consolidating various protections and benefits, making them an attractive option for those seeking integrated solutions.
Focus on environmental, social, and governance (ESG) factors
As ESG investing gains traction, it’s probable that annuity providers will offer more options for investors to align their annuity sub-accounts with their values. This could mean variable annuities with sub-accounts focused on sustainable investments or fixed annuities from companies with strong ESG ratings.
This trend caters to a growing demand among investors to make socially responsible choices across all their financial products, including retirement vehicles. The integration of ESG factors into annuities reflects a broader shift in the financial industry towards more conscious investing.
The future of annuities in 2026 and beyond promises greater personalization, innovative hybrid products, and an increased focus on ESG factors. These developments are set to make annuities even more sophisticated and adaptable, offering US retirement savers a wider range of tools to secure their financial futures.
Making informed annuity decisions in 2026
Making informed decisions about annuities in 2026 is critical for US retirement savers. The complexity of these products, coupled with their long-term implications, necessitates a thoughtful and diligent approach. Rushing into a decision without proper research and guidance can lead to suboptimal outcomes.
The key to success lies in understanding your needs, exploring all available options, and seeking expert advice. This section provides a practical framework to guide you through the decision-making process, ensuring your annuity choices align perfectly with your retirement aspirations.
Self-assessment of your financial situation
Before even looking at specific annuity products, conduct a thorough self-assessment of your financial situation. Consider:
Current savings and investments: How much do you have saved, and where is it invested?
Retirement income needs: What are your projected expenses in retirement?
Other income sources: Do you have Social Security, pensions, or other income?
Risk tolerance: How comfortable are you with market fluctuations?
Time horizon: How many years until you plan to retire?
Answering these questions will provide a clear picture of your starting point and help define what you need an annuity to accomplish within your broader financial strategy. This foundational step is often overlooked but is essential for making targeted choices.
Research and comparison of providers and products
Once you have a clear understanding of your needs, dedicate time to research and compare different annuity providers and their products. Look beyond just the interest rates or potential returns. Pay close attention to:
Company’s financial strength: Choose providers with strong credit ratings.
Contract terms and conditions: Understand all the fine print, including surrender charges.
Fees and expenses: Compare all costs associated with the annuity.
Riders and optional benefits: Evaluate if the additional costs are worth the benefits.
Online resources, financial publications, and independent rating agencies can be valuable tools in this research phase. Don’t be afraid to ask for multiple quotes and product illustrations.
Seeking professional guidance
As emphasized earlier, the expertise of a qualified financial advisor is invaluable when it comes to annuities. They can help you:
Translate complex jargon: Simplify the intricate language of annuity contracts.
Identify hidden costs: Point out fees or clauses you might miss.
Tailor recommendations: Suggest products that truly fit your unique situation.
Ensure suitability: Verify that the annuity is appropriate for your age, financial standing, and goals.
Choose an advisor who is a fiduciary and transparent about their compensation. Their guidance can save you from costly mistakes and help you optimize your annuity choices for a secure and comfortable retirement.
Making informed annuity decisions in 2026 involves a combination of self-assessment, thorough research, and professional guidance. By following these steps, US retirement savers can confidently select annuities that enhance their financial security and contribute to a fulfilling retirement.
Key Aspect
Brief Description
Guaranteed Income
Annuities can provide a stable, lifelong income stream, protecting against outliving savings.
Tax-Deferred Growth
Earnings grow tax-free until withdrawal, allowing for greater compounding over time.
Types of Annuities
Fixed, Variable, and Indexed annuities offer different risk/reward profiles to suit various needs.
Potential Drawbacks
Consider liquidity limitations, fees, and inflation risk before committing to an annuity.
Frequently asked questions about annuities in 2026
What is the primary benefit of an annuity for retirement savers?▼
The main benefit is guaranteed income for life, which protects against outliving your savings. Many annuities offer predictable payments, providing financial security and stability throughout your retirement years, regardless of market performance or economic fluctuations.
Are annuities suitable for everyone’s retirement plan?▼
No, annuities are not suitable for everyone. They are best for individuals seeking guaranteed income and tax-deferred growth, who have already maxed out other retirement accounts and don’t need immediate access to a large portion of their funds due to liquidity limitations.
How do regulatory changes in 2026 impact annuity buyers?▼
Regulatory changes in 2026 focus on consumer protection, requiring advisors to act in your best interest and provide clearer disclosures. This means greater transparency regarding fees, surrender charges, and product features, leading to more informed and suitable annuity recommendations.
What are the main differences between fixed and variable annuities?▼
Fixed annuities offer guaranteed interest rates and predictable growth, while variable annuities invest in market sub-accounts, providing growth potential but also market risk. Fixed annuities prioritize security, whereas variable annuities aim for higher returns with associated volatility.
Should I consult a financial advisor before buying an annuity?▼
Yes, consulting a qualified financial advisor is highly recommended. They can help assess your specific needs, compare various products, explain complex contract terms, and ensure the annuity aligns strategically with your overall retirement and financial goals.
Conclusion
Understanding annuities in 2026: insider knowledge for US retirement savers is more crucial than ever in building a resilient financial future. Annuities offer a unique blend of guaranteed income, tax-deferred growth, and customization options that can significantly enhance your retirement security. While they come with considerations such as liquidity limitations and fees, a well-informed decision, ideally made with the guidance of a financial advisor, can leverage their benefits to create a stable and predictable income stream for your golden years. As the market continues to evolve with innovations and increased consumer protection, staying knowledgeable about these financial instruments will empower you to make strategic choices that align with your long-term aspirations, ensuring peace of mind and financial independence in retirement.