Estate Planning in 2026: Navigating Federal Gift & Estate Tax Exemptions
Understanding the upcoming changes to US federal gift and estate tax exemptions in 2026 is crucial for effective estate planning, offering significant opportunities to optimize wealth transfer strategies and minimize tax liabilities.
By: Rafaela on September 23, 2026
Understanding the upcoming changes to US federal gift and estate tax exemptions in 2026 is crucial for effective estate planning, offering significant opportunities to optimize wealth transfer strategies and minimize tax liabilities.
As we approach 2026, the landscape of estate planning in 2026 is set for significant shifts, particularly concerning US federal gift and estate tax exemptions. These impending changes could dramatically impact how you plan for your legacy and transfer wealth to future generations. Are you ready to adapt your strategy to these new realities?
Understanding the 2026 tax landscape for estate planning
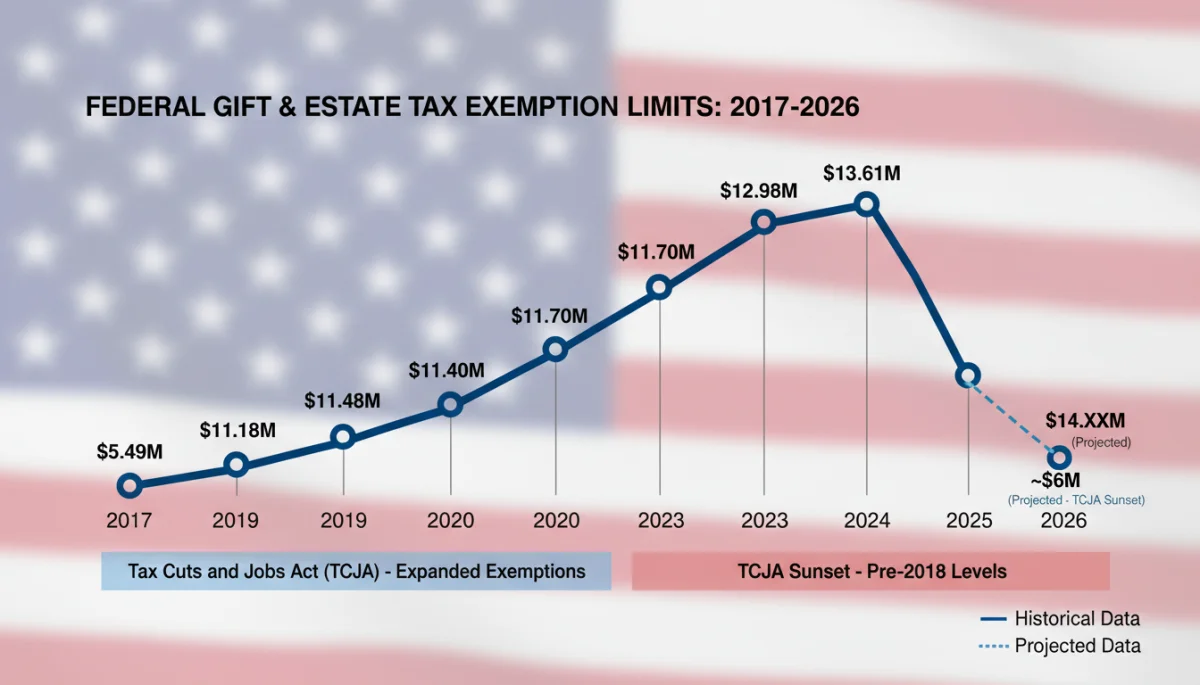
The year 2026 marks a pivotal moment for estate planning in the United States. Key provisions from the Tax Cuts and Jobs Act of 2017 (TCJA) are set to expire, which will significantly alter the federal gift and estate tax exemptions. This expiration will likely lead to a substantial reduction in the exemption amounts, potentially subjecting more estates to federal taxation.
For individuals and families, understanding these changes is not merely an academic exercise; it’s a critical component of responsible financial stewardship. Proactive planning can help mitigate potential tax burdens and ensure that your assets are distributed according to your wishes, rather than being diminished by unforeseen taxes.
The sunset of TCJA provisions
Increased Exemption Amounts: TCJA dramatically increased the federal gift and estate tax exemption amounts, effectively doubling them for a period.
Scheduled Expiration: These enhanced exemptions are temporary and are scheduled to revert to pre-TCJA levels, adjusted for inflation, at the end of 2025.
Impact on Wealth Transfer: This sunset provision will mean a lower threshold for taxable estates, affecting a broader range of high-net-worth individuals.
The immediate consequence of these expiring provisions is a predicted decrease in the federal gift and estate tax exemption. While the exact figure will depend on inflation adjustments, it is widely anticipated to fall from over $13 million per individual in 2024 to approximately $7 million or $6.5 million in 2026. This substantial reduction necessitates a thorough review of existing estate plans and the consideration of new strategies to maximize wealth transfer efficiency.
Current federal gift and estate tax exemptions
Before delving into the future, it’s essential to grasp the current framework of federal gift and estate tax exemptions. These exemptions dictate how much an individual can give away during their lifetime or leave to heirs at death without incurring federal gift or estate taxes. The current high exemption amounts have provided a unique window of opportunity for many to engage in significant wealth transfer strategies.
The unified credit system allows taxpayers to use their lifetime gift tax exemption or their estate tax exemption interchangeably. Any gifts made during one’s lifetime that exceed the annual gift tax exclusion reduce the available estate tax exemption at death. This integrated approach ensures a comprehensive view of an individual’s total taxable transfers.
Annual gift tax exclusion
Tax-Free Gifting: Individuals can gift a certain amount each year to as many recipients as they wish, free of gift tax and without using up their lifetime exemption.
Inflation Adjustment: This annual exclusion is subject to inflation adjustments and has steadily increased over the years.
Strategic Gifting: Utilizing the annual exclusion is a powerful tool for reducing the size of one’s taxable estate over time.
For 2024, the annual gift tax exclusion is $18,000 per donee. This means an individual can give $18,000 to their child, $18,000 to a grandchild, and so on, without any gift tax implications or impact on their lifetime exemption. Married couples can combine their exclusions, effectively gifting $36,000 per donee annually. Understanding and leveraging this annual exclusion is a foundational element of effective estate planning, particularly as we look towards potentially lower lifetime exemption amounts in 2026.
Projected changes to exemption amounts in 2026
The most significant change looming for estate planning in 2026 is the anticipated reduction in the federal gift and estate tax exemption amounts. This reversion to pre-TCJA levels, adjusted for inflation, will have far-reaching implications for individuals with substantial assets. The exact figures are still subject to inflation adjustments and potential legislative action, but the direction of change is clear.
Experts widely anticipate the exemption to approximately halve from its current levels. This means that estates previously unaffected by federal estate taxes may suddenly find themselves within the taxable bracket. This shift underscores the urgency for high-net-worth individuals to review and potentially revise their estate plans well in advance of 2026.
Potential exemption scenarios
While the precise figures for 2026 are not yet finalized, financial advisors and estate planners are preparing for a range of possibilities. The most common projection suggests a return to approximately $6.5 million to $7 million per individual, adjusted for inflation from the 2011 baseline. This substantial decrease will necessitate a re-evaluation of gifting strategies, trust structures, and charitable giving plans.
It’s also important to consider that legislative changes could occur before 2026. While the current law dictates the sunset, Congress could act to extend the higher exemptions, modify them, or even introduce entirely new tax legislation. However, prudence dictates planning based on the current law’s scheduled expiration, as relying on uncertain future legislation is a risky strategy for estate planning.
Strategies for effective estate planning before 2026
Given the impending changes, proactive estate planning is paramount. There are several strategies individuals can employ now to take advantage of the higher exemption amounts before they potentially decrease. These strategies often involve making substantial gifts during one’s lifetime, establishing various types of trusts, and reviewing existing documents.
Engaging with an experienced estate planning attorney and financial advisor is crucial to tailor these strategies to your specific financial situation and family goals. A personalized approach ensures that all aspects of your estate are considered, from asset protection to beneficiary designations.
Maximizing current gift exemptions
Lifetime Gifting: Consider making large gifts to beneficiaries now, utilizing the current high lifetime exemption amount. This allows assets to grow outside of your taxable estate.
Spousal Gifting: Married couples can combine their exemptions to gift even larger amounts, potentially up to $26 million in 2024, without incurring gift taxes.
Irrevocable Trusts: Transferring assets into irrevocable trusts can remove them from your estate, making them exempt from future estate taxes, provided certain conditions are met.
One popular strategy is to establish an Irrevocable Life Insurance Trust (ILIT). An ILIT removes life insurance proceeds from your taxable estate, ensuring that the death benefit goes directly to your beneficiaries without being subject to estate taxes. Another effective tool is a Grantor Retained Annuity Trust (GRAT), which allows you to transfer appreciating assets out of your estate with minimal gift tax implications, especially in a low-interest-rate environment.
Impact on different types of estates and wealth transfer
The 2026 changes will not affect all estates equally. While ultra-high-net-worth individuals have always engaged in sophisticated estate planning, the reduced exemption amounts will bring a broader segment of the affluent population into the federal estate tax conversation. This means that individuals with what might be considered a ‘moderately’ large estate today could face significant tax liabilities in the future.
Understanding how these changes impact various types of wealth transfer mechanisms is critical for adjusting your plan. From outright gifts to complex trust structures, each vehicle will need re-evaluation in light of the new tax environment.
Considerations for various asset types
Different assets respond differently to tax planning strategies. For instance, highly appreciating assets, such as real estate or business interests, are often ideal candidates for early gifting or transfer into trusts, as their future appreciation occurs outside the grantor’s taxable estate. Conversely, liquid assets might be retained for flexibility or used to fund annual exclusion gifts.
Business owners, in particular, should pay close attention. The transfer of a family business can be a complex undertaking, and the reduced exemption could make such transfers more costly. Succession planning, therefore, becomes even more intertwined with estate tax planning, requiring careful consideration of entity structures, valuation methods, and buy-sell agreements.
Reviewing and updating your existing estate plan
The impending changes in 2026 make it imperative for everyone with an existing estate plan to review and potentially update their documents. What worked perfectly under the current tax regime may become inefficient or even counterproductive once the exemptions decrease. This review should encompass wills, trusts, beneficiary designations, and powers of attorney.
A comprehensive review ensures that your estate plan remains aligned with your intentions and is optimized for the future tax environment. It’s an opportunity to ensure that your beneficiaries are still correctly identified, that guardians for minor children are still appropriate, and that your overall financial planning goals are still being met.
Key elements to review
Wills and Trusts: Ensure that your testamentary documents reflect the current tax laws and your wishes regarding asset distribution. Pay particular attention to formulas that reference exemption amounts.
Beneficiary Designations: Confirm that beneficiary designations on retirement accounts, life insurance policies, and other financial assets are up to date and align with your overall estate plan.
Powers of Attorney: Verify that your durable power of attorney and healthcare power of attorney are current and appoint individuals you trust to make decisions on your behalf.
Many estate plans contain clauses that are tied to the federal estate tax exemption amount. For example, a will might state that the maximum amount exempt from federal estate tax goes into a bypass trust, with the remainder going to a spouse. If the exemption amount significantly decreases, this formula could inadvertently lead to unintended outcomes, such as a larger portion going into the bypass trust than originally intended, or vice-versa. Therefore, specific language within these documents must be carefully scrutinized and adjusted.
The role of professional advice in navigating 2026 changes
Navigating the complexities of federal gift and estate tax exemptions, especially with impending changes, requires expert guidance. The landscape of estate planning in 2026 is intricate, and professional advisors can provide invaluable insights tailored to your unique financial situation. This includes estate planning attorneys, financial advisors, and tax professionals.
These professionals can help you understand the nuances of the law, identify potential planning opportunities, and implement strategies that align with your long-term goals. Their expertise can be the difference between an efficient, tax-optimized estate and one burdened by avoidable taxes and administrative hurdles.
Choosing the right advisors
When selecting your estate planning team, look for professionals with extensive experience in estate and gift tax planning, particularly those who stay current with legislative developments. A collaborative approach, where your attorney, financial advisor, and accountant work together, often yields the most comprehensive and effective plan.
Don’t hesitate to ask about their experience with similar client situations and their approach to proactive planning for legislative changes. A good advisor will not only react to changes but will help you anticipate them and position your estate accordingly. Their guidance is not just about avoiding taxes; it’s about securing your legacy and ensuring your wishes are honored.
Key Aspect
Brief Description
TCJA Sunset
High federal gift and estate tax exemptions from TCJA expire end of 2025.
Exemption Reduction
Exemption amounts are projected to significantly decrease in 2026.
Proactive Gifting
Utilize current higher exemptions for lifetime gifts before 2026.
Plan Review
Review and update wills, trusts, and beneficiary designations for 2026.
Frequently asked questions about 2026 estate planning
What is the main change expected for estate planning in 2026?▼
The primary change is the expiration of the Tax Cuts and Jobs Act (TCJA) provisions, which will likely cause a significant reduction in the federal gift and estate tax exemption amounts. This means more estates could be subject to federal taxation starting in 2026.
How will the reduced exemption amounts affect my estate?▼
If your estate’s value exceeds the new, lower exemption amount, a portion of it may be subject to federal estate tax. This could reduce the inheritance your beneficiaries receive, highlighting the need for proactive planning to mitigate potential tax liabilities.
What can I do now to prepare for the 2026 changes?▼
Consider utilizing the current higher gift and estate tax exemptions by making substantial lifetime gifts or establishing irrevocable trusts. Reviewing and updating your existing estate documents, such as wills and beneficiary designations, is also crucial before 2026.
Should I consult with a professional for my estate plan?▼
Absolutely. Given the complexity of the impending changes, consulting with an experienced estate planning attorney, financial advisor, and tax professional is highly recommended. They can provide tailored advice and strategies to optimize your plan.
Will the annual gift tax exclusion also change in 2026?▼
The annual gift tax exclusion is adjusted separately for inflation and is not directly tied to the TCJA sunset. While it may see incremental increases, the significant reduction expected for the lifetime gift and estate tax exemption does not apply to the annual exclusion.
Conclusion
The upcoming changes to US federal gift and estate tax exemptions in 2026 represent a critical juncture for estate planning. With the anticipated reduction in exemption amounts, proactive and informed decision-making is more important than ever. By understanding the projected tax landscape, leveraging current opportunities, and engaging with knowledgeable professionals, individuals can effectively navigate these shifts. Reviewing and updating your estate plan now will ensure your legacy is preserved and your loved ones are provided for, aligning your financial strategies with your long-term goals.