Discover how a Home Equity Line of Credit (HELOC) in 2026 can empower you to access up to 80% of your home's equity. This guide covers the mechanics, benefits, and crucial considerations for leveraging your property's value effectively.
By: Rafaela on September 23, 2026
A Home Equity Line of Credit (HELOC) in 2026 enables homeowners to access a revolving line of credit, typically up to 80% of their home’s equity, offering flexible funds for various financial needs.
Are you wondering how to tap into your most significant asset? Understanding HELOCs in 2026: Leveraging Your Home Equity for Up to 80% of Its Value is becoming increasingly vital for homeowners seeking financial flexibility. This guide will demystify the Home Equity Line of Credit, exploring its mechanisms, benefits, and what you need to know to make an informed decision in the current economic landscape.
What is a HELOC and How Does It Work in 2026?
A Home Equity Line of Credit, or HELOC, is a revolving credit line secured by your home. Unlike a traditional loan that provides a lump sum, a HELOC allows you to borrow money as needed, up to a pre-approved limit, using your home as collateral. In 2026, HELOCs continue to be a popular financial tool, offering flexibility that many other lending products do not.
The core concept remains consistent: lenders assess your home’s value, subtract any outstanding mortgage balance, and then offer a credit line based on a percentage of that available equity, often up to 80%. This percentage can vary depending on the lender, your creditworthiness, and prevailing market conditions.
The Draw and Repayment Periods
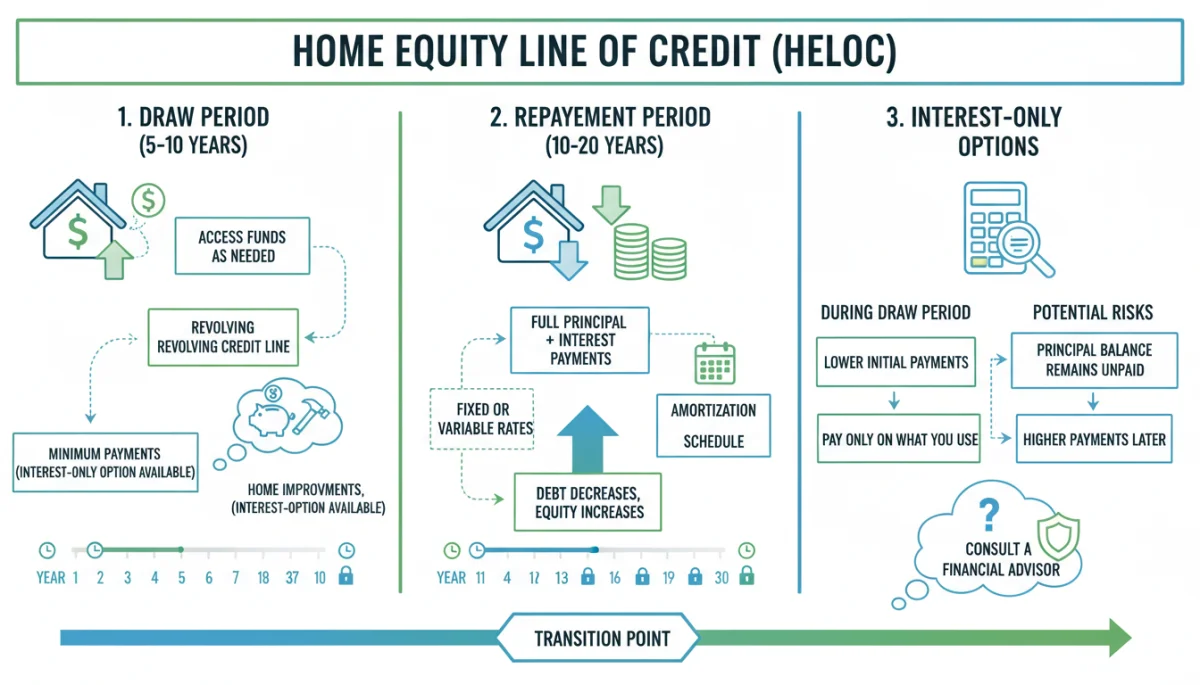
HELOCs operate in two distinct phases: the draw period and the repayment period. Understanding these phases is crucial for managing your line of credit effectively.
Draw Period: Typically lasting 5 to 10 years, this is when you can access funds, make purchases, or pay off debts using your HELOC. During this period, you generally only pay interest on the amount you’ve borrowed, not the entire credit line.
Repayment Period: Once the draw period ends, you can no longer borrow money. Instead, you begin repaying the principal and interest on the outstanding balance. This phase can last 10 to 20 years, depending on the terms of your agreement.
In 2026, lenders are placing a stronger emphasis on transparent communication regarding these phases, ensuring borrowers fully comprehend the transition from drawing funds to full repayment. This shift aims to prevent payment shock and promote responsible borrowing practices.
Understanding these fundamental mechanics is the first step toward effectively utilizing your home’s equity. A HELOC can be a powerful financial instrument if managed wisely, providing access to capital when you need it most.
Eligibility and Application Process for 2026 HELOCs
Securing a HELOC in 2026 involves meeting specific eligibility criteria and navigating a structured application process. Lenders evaluate several factors to determine your creditworthiness and the amount of equity you can access. These factors are designed to minimize risk for both the borrower and the financial institution.
Typically, a strong credit score is paramount, often above 680, though some lenders may consider scores slightly lower with other compensating factors. Your debt-to-income (DTI) ratio is another critical metric; lenders prefer a DTI below 43% to ensure you can comfortably manage additional debt obligations.
Key Eligibility Factors
Beyond credit score and DTI, several other elements play a significant role in your HELOC approval.
Home Equity: You must have substantial equity in your home. Lenders generally require you to maintain at least 20% equity after taking out the HELOC, meaning they will lend up to 80% of your home’s value minus your current mortgage balance.
Stable Income: Demonstrating a consistent and reliable income source is essential. This reassures lenders of your ability to make regular payments on the HELOC.
Property Type: Most lenders prefer primary residences, though some may offer HELOCs on secondary homes or investment properties, often with stricter terms.
The application process usually begins with pre-qualification, followed by a formal application that includes providing financial documents such as tax returns, pay stubs, and bank statements. An appraisal of your home is almost always required to determine its current market value, which directly impacts your available credit limit.
In 2026, digital platforms are streamlining the application process, making it faster and more convenient for homeowners to apply and track their HELOC status. However, thorough documentation and understanding of terms remain crucial.
Benefits of Leveraging Your Home Equity with a HELOC
A HELOC offers a versatile financial solution for homeowners looking to access capital. The benefits extend beyond mere access to funds, encompassing flexibility, potentially lower interest rates, and advantageous tax implications, making them an attractive option for various financial goals.
One of the primary advantages is the flexibility it provides. Unlike a fixed-term loan, a HELOC allows you to draw funds as needed, much like a credit card. This means you only pay interest on the amount you actually borrow, not the entire credit line, which can lead to significant savings if you don’t need all the funds upfront.
Common Uses for HELOC Funds
Home Renovations: Funding home improvements can increase your property’s value, making a HELOC a strategic investment.
Debt Consolidation: Consolidating high-interest debts, such as credit card balances, into a HELOC can result in lower monthly payments and reduced interest costs.
Education Expenses: Covering college tuition or other educational costs can be more affordable with the lower interest rates often associated with HELOCs.
Emergency Fund: A HELOC can serve as a safety net for unexpected expenses, providing immediate access to funds without liquidating other assets.
Furthermore, the interest paid on a HELOC may be tax-deductible if the funds are used to buy, build, or substantially improve the home that secures the loan. This potential tax benefit further enhances the financial appeal of a HELOC, though consulting with a tax advisor is always recommended for personalized guidance.
The ability to access significant capital with favorable terms makes HELOCs a powerful tool for achieving diverse financial objectives in 2026.
Potential Risks and Considerations for HELOC Borrowers
While HELOCs offer considerable benefits, it’s crucial to acknowledge the inherent risks and carefully consider various factors before committing. As with any financial product secured by your home, there are significant implications if not managed responsibly. Understanding these potential downsides is key to making a sound financial decision.
The most substantial risk lies in the fact that your home serves as collateral. If you default on your HELOC payments, your lender could initiate foreclosure proceedings, leading to the loss of your home. This emphasizes the importance of a clear repayment strategy and a realistic assessment of your financial capacity.
Variable Interest Rates and Payment Shock
Many HELOCs come with variable interest rates, meaning your monthly payments can fluctuate. This variability introduces an element of unpredictability to your budget.
In 2026, with potential shifts in interest rate environments, borrowers must be prepared for possible payment increases. This is particularly relevant as you transition from the draw period, where interest-only payments are often an option, to the repayment period, where both principal and interest payments begin. This transition can lead to a significant increase in monthly payments, known as payment shock, which can strain your budget if not anticipated and planned for.
Moreover, if your home’s value declines, you could end up owing more than your home is worth, a situation known as being “underwater.” While less common in a stable market, it’s a risk to consider, as it can make refinancing or selling your home more challenging. Lenders also have the right to freeze or reduce your credit line if property values drop or your financial situation deteriorates.
Careful planning, a thorough understanding of the terms, and a conservative approach to borrowing are essential to mitigate these risks and ensure a positive HELOC experience.
Comparing HELOCs with Other Home Equity Options
When considering leveraging your home’s equity, a HELOC is not your only option. Understanding how it stacks up against alternatives like home equity loans and cash-out refinances is vital for choosing the best financial path for your specific needs. Each product has distinct features, benefits, and drawbacks.
A key differentiator is the borrowing structure. A HELOC provides a revolving line of credit, offering flexibility to borrow and repay funds over time. This contrasts sharply with a home equity loan, which provides a lump sum of money upfront that you repay with fixed monthly payments over a set period. The fixed nature of a home equity loan can offer more predictability in budgeting, as interest rates are typically fixed for the life of the loan.
HELOC vs. Cash-Out Refinance
A cash-out refinance is another popular option, particularly if you have a high-interest rate on your existing mortgage or want to extend your loan term. This involves replacing your current mortgage with a new, larger mortgage and taking the difference in cash.
Interest Rates: HELOCs often have variable rates, while cash-out refinances typically offer fixed rates, providing stability.
Closing Costs: Cash-out refinances usually involve higher closing costs, similar to a new mortgage, whereas HELOCs often have lower or no closing costs.
Access to Funds: A HELOC offers a flexible line of credit, while a cash-out refinance provides a single lump sum.
The choice between these options depends on your financial goals, risk tolerance, and current market conditions. If you need ongoing access to funds and prefer payment flexibility, a HELOC might be suitable. If you need a large, one-time sum and desire predictable payments, a home equity loan or cash-out refinance could be better. In 2026, financial advisors are increasingly recommending a thorough analysis of all options, considering individual financial health and future plans.
Maximizing Your HELOC’s Potential in 2026
To truly harness the power of your HELOC in 2026, strategic planning and disciplined management are paramount. Simply having access to a line of credit isn’t enough; maximizing its potential means using it wisely to achieve your financial objectives while minimizing risks. This involves understanding your financial capacity, monitoring market trends, and having a clear repayment strategy.
One effective strategy is to use your HELOC for investments that can increase your home’s value or generate a return. For instance, carefully planned home renovations can not only improve your living space but also boost your property’s market appeal. This ensures that the borrowed funds are working to enhance your overall financial position.
Budgeting: Create a detailed budget that accounts for potential interest rate fluctuations and ensures you can comfortably make all payments, especially as you transition to the repayment period.
Timely Payments: Always make your payments on time to avoid penalties and maintain a healthy credit score. Consider setting up automatic payments to prevent missed deadlines.
Avoid Over-borrowing: Only borrow what you genuinely need and have a clear plan for repayment. Resist the temptation to treat your HELOC as an extension of your disposable income.
Monitor Interest Rates: Stay informed about prevailing interest rate trends, especially if you have a variable-rate HELOC. This allows you to anticipate payment changes and adjust your budget accordingly.
In 2026, leveraging digital tools and financial planning resources can significantly aid in managing your HELOC effectively. Many lenders offer online portals and mobile apps that provide real-time access to your balance, payment history, and available credit. By adopting a proactive and informed approach, you can ensure your HELOC serves as a valuable asset rather than a financial burden.
Key Aspect
Brief Description
Access to Equity
Leverage up to 80% of your home’s value as a revolving credit line.
Flexible Borrowing
Draw funds as needed during the draw period, paying interest only on the amount used.
Variable Rates
Interest rates typically fluctuate, impacting monthly payment amounts.
Home as Collateral
Your home secures the line of credit, carrying foreclosure risk if payments are missed.
Frequently Asked Questions About HELOCs in 2026
What is the typical maximum percentage of home equity I can access with a HELOC in 2026?▼
In 2026, most lenders allow you to access up to 80% of your home’s appraised value, minus your outstanding mortgage balance. This percentage can vary based on your credit score, financial stability, and the specific lender’s policies, so it’s always wise to compare options.
Are HELOC interest rates fixed or variable in 2026?▼
The majority of HELOCs in 2026 feature variable interest rates, meaning they can fluctuate with market conditions. Some lenders might offer a fixed-rate option for a portion of the balance, but variable rates are more common, impacting your monthly payment amounts over time.
What happens when the draw period of my HELOC ends?▼
Once the draw period concludes, you can no longer borrow funds. You then enter the repayment period, during which you must pay back both the principal and interest on your outstanding balance. This often results in significantly higher monthly payments than during the draw period.
Can I use a HELOC for debt consolidation, and is it a good idea in 2026?▼
Yes, many homeowners use HELOCs for debt consolidation, especially for high-interest debts like credit cards. It can be a good idea in 2026 due to potentially lower interest rates, but remember your home is collateral, so evaluate the risks carefully before proceeding.
What are the typical closing costs for a HELOC in 2026?▼
HELOC closing costs in 2026 are generally lower than those for a traditional mortgage or cash-out refinance. Some lenders may even offer no-closing-cost HELOCs, though these often come with slightly higher interest rates or other fees, so always read the fine print.
Conclusion
Understanding HELOCs in 2026: Leveraging Your Home Equity for Up to 80% of Its Value presents a powerful opportunity for homeowners seeking financial flexibility and access to capital. This guide has illuminated the mechanics, benefits, and critical considerations for this versatile financial product. While HELOCs offer significant advantages like flexible borrowing and potentially lower interest rates, it’s paramount to approach them with a clear understanding of the variable interest rate risks, the implications of using your home as collateral, and the transition from the draw to the repayment period. By carefully assessing your financial situation, comparing options, and adopting a disciplined approach to borrowing and repayment, a HELOC can be an invaluable tool for achieving your personal and financial goals in the evolving economic landscape of 2026.