Comparing Personal Loan Rates Across Banks: Early 2026 Guide
Effectively comparing personal loan rates across various banks in early 2026 is crucial for securing the most advantageous financial solution, requiring a thorough understanding of market trends and individual credit profiles.
By: Rafaela on September 23, 2026
Comparing personal loan rates across banks: finding the best deal in early 2026 is essential for consumers seeking optimal financial solutions, demanding careful research and an understanding of market dynamics.
As we step into early 2026, the financial landscape continues to evolve, making the task of comparing personal loan rates across banks: finding the best deal in early 2026 more critical than ever. Whether you’re consolidating debt, funding a major purchase, or covering unexpected expenses, securing a personal loan with favorable terms can significantly impact your financial well-being. This comprehensive guide will walk you through the intricacies of the personal loan market, offering insights and strategies to help you identify and secure the most advantageous rates available.
Understanding personal loan basics and market trends in early 2026
Before diving into rate comparisons, it’s essential to grasp the fundamental aspects of personal loans and the prevailing market trends. A personal loan is typically an unsecured loan, meaning it doesn’t require collateral like a car or home. Lenders assess your creditworthiness to determine eligibility and interest rates. In early 2026, we are observing a dynamic interest rate environment, influenced by global economic factors, inflation, and central bank policies.
Understanding these macro trends is the first step in positioning yourself for success. Economic stability or volatility directly impacts how banks price their loan products. A rising interest rate environment, for instance, means that lenders will likely offer higher Annual Percentage Rates (APRs) on personal loans. Conversely, a stable or declining rate environment could present opportunities for lower rates.
Key factors influencing personal loan rates
Several variables contribute to the interest rate you might receive. These factors are not static and can shift based on economic conditions and individual lender policies.
Credit Score: A higher credit score (typically 700+) signals lower risk to lenders, often resulting in lower interest rates.
Debt-to-Income Ratio: Lenders assess your ability to repay by looking at how much debt you carry relative to your income. A lower ratio is generally more favorable.
Loan Term: Shorter loan terms often come with lower interest rates, though monthly payments will be higher. Longer terms mean lower monthly payments but potentially more interest paid over time.
Loan Amount: The principal amount you wish to borrow can also influence the rate. Some lenders offer better rates for larger loans, while others might penalize very small or very large amounts.
Economic Climate: As mentioned, the broader economic environment, including inflation and central bank rates, plays a significant role in setting baseline interest rates.
Staying informed about these factors will empower you to better anticipate the rates you might qualify for and understand the rationale behind different offers. Early 2026 predictions suggest a period of cautious optimism, with lenders carefully balancing risk and opportunity.
The importance of your credit profile in securing favorable rates
Your credit profile is arguably the most influential factor in determining the personal loan rates you’ll be offered. A strong credit history not only increases your chances of approval but also ensures access to the most competitive rates. Lenders use your credit report and score to evaluate your financial responsibility and repayment reliability.
Before you even begin the process of comparing personal loan rates, it is highly advisable to review your credit report. You can obtain a free copy from each of the three major credit bureaus (Equifax, Experian, TransUnion) annually. Look for any inaccuracies or discrepancies that could be negatively impacting your score. Rectifying these errors can significantly improve your credit standing and, consequently, the loan rates you qualify for.
Strategies to improve your credit score
Even if your credit score isn’t perfect, there are proactive steps you can take to enhance it before applying for a personal loan. These strategies require time and discipline but can yield substantial benefits.
Pay Bills on Time: Payment history is the most significant factor in your credit score. Make sure all your payments are made on or before their due dates.
Reduce Credit Utilization: Keep your credit card balances low relative to your credit limits. A utilization rate below 30% is generally recommended.
Avoid New Credit: Opening multiple new credit accounts in a short period can lower your score. Limit new applications when you’re preparing to apply for a personal loan.
Address Delinquent Accounts: If you have any overdue accounts, work to bring them current. Even old delinquencies can continue to impact your score.
A well-maintained credit profile not only opens doors to better personal loan rates but also to other financial products with more favorable terms. Investing time in improving your credit score is a long-term financial strategy that pays dividends across various aspects of your financial life.
Navigating different types of lenders in early 2026
The landscape of personal loan providers is diverse, ranging from traditional banks to online lenders and credit unions. Each type of institution has its own strengths, target demographics, and rate structures. Understanding these differences is key to effectively comparing personal loan rates across banks: finding the best deal in early 2026.
Traditional banks, often recognized for their established presence and comprehensive services, might offer competitive rates to existing customers or those with excellent credit. However, their application processes can sometimes be more rigorous and time-consuming. Online lenders, on the other hand, are known for their speed and convenience, often providing quick approvals and funding. They might cater to a broader range of credit scores, though rates can vary widely.
Exploring your lending options
Consider the pros and cons of each lender type based on your financial situation and priorities.
Traditional Banks: Offer personalized service, potentially better rates for existing customers, and a wide array of financial products. May have stricter eligibility requirements.
Credit Unions: Member-owned institutions that often offer lower interest rates and more flexible terms due to their non-profit status. Membership is typically required.
Online Lenders: Known for fast application and approval processes, competitive rates, and often more lenient credit requirements compared to traditional banks. Less personal interaction.
Peer-to-Peer (P2P) Lending Platforms: Connect borrowers directly with individual investors. Rates can be competitive, but approval depends on investor interest.
It’s important not to limit your search to just one type of lender. Broadening your scope to include various institutions will increase your chances of finding the most suitable loan product and the best possible rate in early 2026.
The application process: what to expect and how to prepare
Once you’ve researched lenders and understood your credit profile, the next step is the application process. While specific requirements vary by lender, there are common elements you can expect and prepare for. Being organized and having all necessary documentation ready can streamline the process and prevent delays.
Most lenders will require personal identification, proof of income, and details about your financial obligations. This information allows them to verify your identity, assess your ability to repay the loan, and ensure compliance with regulatory standards. Be prepared to provide bank statements, pay stubs, tax returns, and possibly utility bills.
Pre-qualification versus full application
Many lenders offer a pre-qualification process, which is a soft credit inquiry that doesn’t impact your credit score. This allows you to see potential rates and terms without committing to a full application. This is an excellent tool for comparing personal loan rates across banks: finding the best deal in early 2026 without negatively affecting your credit.
Once you’ve pre-qualified with a few lenders and identified the most attractive options, you can proceed with a full application. This involves a hard credit inquiry, which will temporarily ding your credit score by a few points. However, if you complete all your applications within a short window (typically 14-45 days, depending on the credit scoring model), they will often be treated as a single inquiry for scoring purposes.
Preparing thoroughly for the application process, from gathering documents to understanding the difference between pre-qualification and full application, will make your loan search more efficient and less stressful.
Key metrics for comparing personal loan offers
Simply looking at the advertised interest rate is not enough when comparing personal loan rates across banks: finding the best deal in early 2026. There are several other crucial metrics that can significantly impact the total cost of your loan. A holistic view of these factors is essential for making an informed decision.
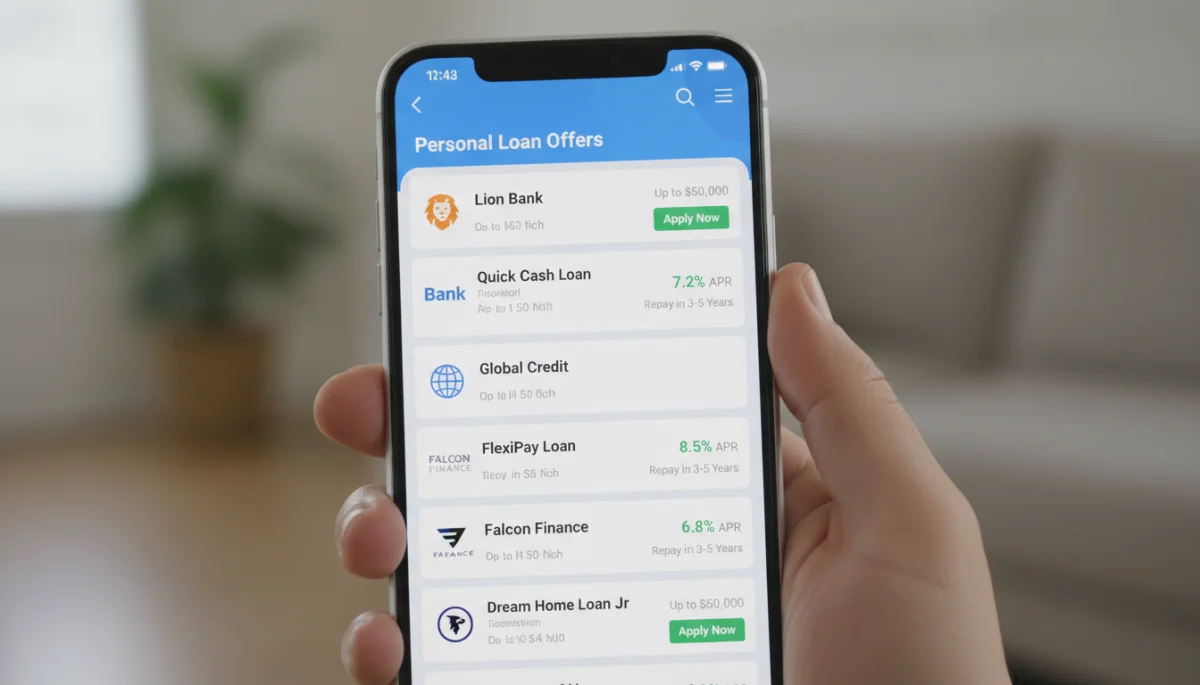
The Annual Percentage Rate (APR) is a more comprehensive measure than the interest rate alone, as it includes not only the interest but also any fees associated with the loan. This gives you a more accurate picture of the true cost of borrowing. Always prioritize comparing APRs rather than just interest rates.
Beyond the APR: fees, terms, and flexibility
While APR is paramount, other elements of a loan offer deserve your careful attention. These can add up and affect the overall affordability and suitability of the loan.
Origination Fees: Some lenders charge an upfront fee for processing the loan, typically a percentage of the loan amount. This fee is often deducted from the loan proceeds.
Late Payment Fees: Understand the penalties for missed or late payments. These can be substantial and add to your debt.
Prepayment Penalties: Check if there are any fees for paying off your loan early. Ideally, you want a loan that allows you to pay it off without extra charges.
Loan Term: As discussed, the length of the loan impacts both your monthly payment and the total interest paid. Choose a term that aligns with your budget and financial goals.
Repayment Flexibility: Some lenders offer options like changing payment dates or hardship programs. While not always a primary concern, these can be valuable in unforeseen circumstances.
Thoroughly evaluating all these components will help you uncover the true cost of each loan offer and select the one that provides the best value and flexibility for your specific needs in early 2026.
Negotiating and finalizing your personal loan
Once you have compared various offers and identified a strong contender, don’t be afraid to try and negotiate. While not all lenders are open to negotiation, some might be willing to adjust terms, especially if you have an excellent credit score or have received better offers from competitors. This step can be crucial in truly comparing personal loan rates across banks: finding the best deal in early 2026.
Even if you can’t negotiate the interest rate directly, you might be able to negotiate other aspects, such as waiving an origination fee or adjusting the repayment schedule. Always present your case politely and with concrete data from competing offers. Highlight your strong credit history and consistent payment record to bolster your position.
Reading the fine print and understanding the contract
Before signing any loan agreement, meticulously read all the terms and conditions. Ensure that you fully understand every clause, including the interest rate, APR, fees, repayment schedule, and any penalties for default or early repayment. If anything is unclear, do not hesitate to ask the lender for clarification.
Disclosure Statement: This document outlines all the costs and terms of the loan. Review it carefully.
Payment Schedule: Confirm the exact dates and amounts of your monthly payments.
Default Clauses: Understand what constitutes a default and the consequences.
Early Repayment: Reconfirm if there are any penalties for paying off the loan ahead of schedule.
Signing a loan agreement is a significant financial commitment. Taking the time to understand every detail protects you from unexpected costs and ensures that the loan you are taking on truly meets your expectations and financial capabilities. A well-negotiated and fully understood loan provides peace of mind.
Key Point
Brief Description
Credit Profile Review
Crucial for securing best rates; check report for accuracy and improve score proactively.
Diverse Lender Options
Explore traditional banks, credit unions, and online lenders for varied offers.
APR vs. Interest Rate
Compare Annual Percentage Rate (APR) for true cost, as it includes fees.
Read the Fine Print
Understand all terms, fees, and penalties before finalizing any loan agreement.
Frequently asked questions about personal loan rates
What is a good credit score to get a personal loan in early 2026?▼
While lenders vary, a credit score of 700 or higher is generally considered good and will likely qualify you for more favorable personal loan rates. Scores above 760 are excellent and typically unlock the best offers. However, some lenders cater to individuals with lower scores, albeit often with higher interest rates.
How does pre-qualification work for personal loans?▼
Pre-qualification involves a soft credit check that doesn’t affect your credit score. You provide basic financial information, and the lender gives you an estimate of the loan amount and interest rate you might qualify for. It’s a useful tool for comparing multiple offers without commitment.
Are personal loan rates fixed or variable in early 2026?▼
Most personal loans offered by banks and online lenders in early 2026 are fixed-rate loans, meaning your interest rate and monthly payment remain the same throughout the loan term. Variable-rate options are less common but do exist, where the rate can fluctuate based on market indices.
What fees should I watch out for with personal loans?▼
Key fees to consider include origination fees (deducted from loan proceeds), late payment fees, and potentially prepayment penalties if you pay off the loan early. Always check the Annual Percentage Rate (APR) as it includes most of these costs in one figure.
Can I negotiate personal loan rates with banks?▼
While not always possible, some lenders may be open to negotiation, especially if you have excellent credit or have received a better offer from a competitor. It’s always worth asking, as even a small reduction in the rate or waiver of a fee can save you money.
Conclusion
Successfully comparing personal loan rates across banks: finding the best deal in early 2026 requires a combination of diligent research, a solid understanding of your own financial standing, and an awareness of the broader economic landscape. By taking the time to improve your credit profile, exploring diverse lending options, meticulously comparing APRs and associated fees, and understanding the fine print, you can position yourself to secure a personal loan that truly aligns with your financial goals and budget. Remember, an informed borrower is an empowered borrower, capable of making the best financial decisions for their future.