Discover how to implement smart student loan refinancing strategies in 2026 to reduce your monthly payments and overall interest costs, offering a path to financial freedom.
By: Rafaela on September 23, 2026
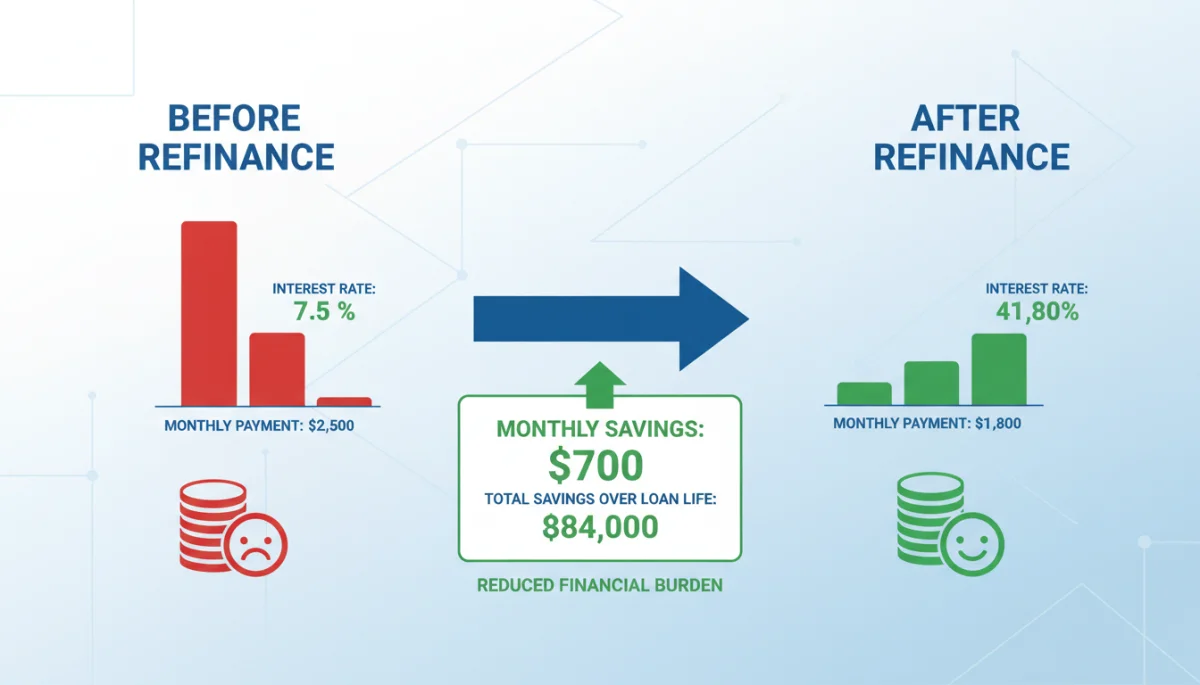
Student loan refinancing strategies for 2026 focus on securing lower interest rates and adjusting repayment terms to significantly reduce monthly payments and total interest paid over the life of the loan.
Navigating the complexities of student loan debt can feel overwhelming, but with the right approach, significant relief is within reach. For 2026, understanding and implementing effective student loan refinancing strategies is crucial for anyone looking to lighten their financial burden. This comprehensive guide will walk you through the essential steps to potentially lower your monthly payments by 1.5% or more, helping you regain control of your finances and accelerate your journey to debt freedom.
Understanding Student Loan Refinancing in 2026
Student loan refinancing involves taking out a new loan to pay off one or more existing student loans. The primary goal is often to secure a lower interest rate, which can lead to reduced monthly payments and substantial savings over the life of the loan. In 2026, the financial landscape continues to evolve, making it important to understand how current market conditions and lender offerings can impact your refinancing opportunities.
Refinancing is not merely about consolidating loans; it’s a strategic financial maneuver that can dramatically alter your repayment trajectory. It requires careful consideration of your current financial health, credit score, and future income potential. The benefits can be profound, but so can the implications if not approached thoughtfully.
What’s New in 2026 for Refinancing?
The year 2026 brings with it new economic indicators and potential policy shifts that could influence interest rates and lender requirements. Staying informed about these changes is key to timing your refinancing application effectively. Lenders are increasingly offering more personalized rates based on a broader range of financial data.
Dynamic Interest Rates: Keep an eye on federal interest rate forecasts, as these often influence private lender rates.
Expanded Eligibility Criteria: Some lenders are broadening their eligibility requirements, making refinancing accessible to more borrowers.
Digital Application Processes: The application process is becoming even more streamlined and digital, simplifying the experience for borrowers.
For many borrowers, refinancing offers a chance to simplify their financial life by combining multiple loans into a single payment. This not only reduces the number of bills to track but also creates a clearer path to understanding your total debt and repayment schedule. The potential for a lower interest rate is the most attractive feature, but the convenience and clarity it provides are equally valuable.
Assessing Your Eligibility for Refinancing
Before diving into applications, it’s crucial to assess your eligibility for student loan refinancing. Lenders evaluate several factors to determine your creditworthiness and the terms they are willing to offer. Understanding these criteria beforehand can help you prepare and improve your chances of securing the best possible rates.
A strong financial profile is your greatest asset when seeking refinancing. Lenders are looking for reliability and a low risk of default. This means a solid credit history, stable income, and a manageable debt-to-income ratio are all critical components of a successful application.
Key Eligibility Factors
Several factors play a significant role in a lender’s decision. Focusing on improving these areas can directly impact the interest rate you receive.
Credit Score: A high credit score (typically 670 or above) is often a prerequisite for the best rates. Lenders view borrowers with excellent credit as lower risk.
Income and Employment History: A stable income and consistent employment demonstrate your ability to make regular payments. Lenders usually prefer to see at least two years of steady employment.
Debt-to-Income Ratio: This ratio compares your monthly debt payments to your gross monthly income. A lower ratio indicates that you have more disposable income to cover your loan payments.
Existing Loan Balances: While not a strict eligibility factor, the amount you wish to refinance can influence lender options.
Even if your current financial situation isn’t perfect, there are steps you can take to strengthen your application. Improving your credit score by paying bills on time, reducing other debts, or even enlisting a co-signer can make a substantial difference. Remember, the goal is to present yourself as the most attractive borrower possible.
Comparing Refinancing Lenders and Offers
Once you’ve assessed your eligibility, the next critical step is to compare various lenders and their refinancing offers. The market for student loan refinancing is competitive, with many banks, credit unions, and online lenders vying for your business. Each lender has its own set of terms, rates, and benefits, making thorough comparison essential.
Don’t settle for the first offer you receive. Taking the time to research multiple lenders can uncover significant savings. Look beyond just the interest rate; consider fees, repayment terms, customer service, and any unique perks or protections each lender offers.
What to Look for in Lender Offers
A comprehensive comparison involves more than just the advertised interest rate. Dig deeper into the fine print to understand the true cost and flexibility of each loan.
Interest Rates (Fixed vs. Variable): Decide whether a fixed rate (stable payments) or a variable rate (potentially lower initial payments, but risk of increase) is better for your financial comfort.
Loan Terms: Shorter terms often mean higher monthly payments but less interest paid overall, while longer terms reduce monthly payments but increase total interest.
Fees: Check for origination fees, application fees, or prepayment penalties. Ideally, look for lenders with no such fees.
Borrower Protections: Some lenders offer forbearance or deferment options in case of financial hardship, similar to federal loans.
Many lenders offer pre-qualification processes that allow you to see potential rates without impacting your credit score. This is an excellent way to shop around and get a clear picture of your options before committing to a hard credit inquiry. Utilize these tools to your advantage to find the most favorable terms for your specific situation. This meticulous comparison is a cornerstone of effective student loan refinancing strategies.
The Application Process: Step-by-Step Guide
Refinancing your student loans involves a structured application process. While it may seem daunting, breaking it down into manageable steps can make it much smoother. Being prepared with all necessary documentation and understanding each stage will help you navigate the process efficiently.
The application typically starts online, where you’ll provide personal, financial, and loan-specific information. Accuracy and completeness are key to avoiding delays. Remember, the goal is to present a clear and compelling financial picture to the lender.
Required Documentation and Information
Having all your documents ready before you begin will significantly speed up the application.
Personal Information: Government-issued ID, Social Security number, and contact details.
Financial Information: Income verification (pay stubs, tax returns), bank statements, and details of other debts.
Existing Loan Information: Account numbers, current balances, and interest rates for all loans you wish to refinance.
Education Information: Proof of graduation or enrollment, if applicable.
Once you submit your application, the lender will review your information, conduct a hard credit inquiry, and verify your employment and income. This underwriting process can take anywhere from a few days to a few weeks. Be prepared to respond promptly to any requests for additional information to keep the process moving. Successfully navigating this process is a vital part of implementing effective student loan refinancing strategies.
Optimizing Your Refinancing Terms for Maximum Savings
Securing a lower interest rate is a primary objective of refinancing, but optimizing your loan terms goes beyond just the rate. Strategic decisions regarding loan duration, fixed versus variable rates, and payment structure can further maximize your savings and align the loan with your financial goals for 2026 and beyond.
Consider your long-term financial outlook. Do you anticipate a significant increase in income? Are you planning other major financial commitments, like buying a home? These factors should influence your choice of loan terms to ensure the refinancing truly benefits you in the long run.
Strategies for Term Optimization
Making informed choices about your loan terms can lead to substantial long-term savings.
Shorter Loan Terms: While increasing monthly payments, a shorter term drastically reduces the total interest paid. This is ideal if you can comfortably afford higher payments.
Fixed-Rate Loans: Offers predictability and protection against rising interest rates, providing peace of mind for the duration of the loan.
Variable-Rate Loans: Can offer a lower initial interest rate, potentially saving you money in the short term, but comes with the risk of future rate increases. Suitable for those who plan to pay off their loan quickly or are comfortable with market fluctuations.
Bi-weekly Payments: Making half-payments every two weeks (26 payments a year) can effectively shave years off your loan term and reduce total interest.
It’s also worth exploring if the lender offers any loyalty discounts or rate reductions for setting up automatic payments. Even a small reduction can add up over time. The goal is to tailor the new loan to fit your current financial capacity and future aspirations, ensuring that every aspect of the refinancing works in your favor.
Post-Refinancing Best Practices and Financial Planning
Refinancing your student loans is a significant financial achievement, but the journey doesn’t end there. Implementing best practices post-refinancing is crucial to maintaining your financial momentum and maximizing the benefits of your new loan terms. This includes diligent payment management, continued financial planning, and exploring further savings opportunities.
The period immediately following refinancing is an excellent time to re-evaluate your overall budget and financial goals. With potentially lower monthly payments, you might find yourself with more disposable income. Strategically allocating these extra funds can further accelerate your financial progress.
Maintaining Momentum After Refinancing
To fully capitalize on your refinancing efforts, consider these ongoing strategies.
Automate Payments: Set up automatic payments to ensure you never miss a due date, which can also sometimes qualify you for a small interest rate discount.
Make Extra Payments: If financially feasible, making extra payments (even small ones) can further reduce your principal balance and total interest paid.
Regularly Review Your Financial Health: Periodically check your credit score and debt-to-income ratio. Continuous improvement can open doors to even better financial products in the future.
Build an Emergency Fund: With potentially lower monthly obligations, prioritize building a robust emergency fund to cover unexpected expenses without derailing your loan payments.
Remember, refinancing is a powerful tool, but it’s part of a larger financial strategy. By consistently applying sound financial principles, you can leverage your refinanced student loan to achieve greater financial stability and peace of mind. This proactive approach is a hallmark of successful student loan refinancing strategies.
Key Strategy
Brief Description
Rate Shopping
Compare multiple lenders to find the lowest interest rates and best terms for your new loan.
Credit Improvement
Boost your credit score and reduce debt-to-income ratio before applying to secure better offers.
Term Optimization
Choose between fixed/variable rates and adjust loan terms to align with your financial goals.
Post-Refinancing Habits
Automate payments and consider making extra payments to accelerate debt payoff.
Frequently Asked Questions About Student Loan Refinancing
What is the primary benefit of student loan refinancing?▼
The main benefit is securing a lower interest rate, which can lead to significantly reduced monthly payments and substantial savings on the total interest paid over the life of the loan. It can also simplify payments by consolidating multiple loans.
Will refinancing my federal student loans affect my borrower protections?▼
Yes, refinancing federal student loans into a private loan means losing federal protections like income-driven repayment plans, forbearance, deferment, and potential loan forgiveness programs. This is a crucial consideration before proceeding with refinancing.
What credit score do I need to refinance student loans?▼
While requirements vary by lender, a strong credit score, typically 670 or higher (good to excellent), is generally needed to qualify for the most competitive interest rates. A higher score indicates lower risk to lenders.
Can I refinance student loans with a co-signer?▼
Yes, many lenders allow you to refinance with a co-signer, which can help you qualify for a loan or secure a lower interest rate, especially if your own credit profile is not yet strong enough.
How often can I refinance my student loans?▼
There’s generally no limit to how many times you can refinance your student loans. If your credit score improves or interest rates drop further, you can refinance again to potentially secure an even better deal.
Conclusion
Successfully implementing student loan refinancing strategies in 2026 offers a tangible pathway to financial relief and greater control over your debt. By understanding your eligibility, diligently comparing lender offers, and optimizing your loan terms, you can significantly reduce your monthly payments and overall interest burden. Remember that refinancing is a powerful tool, but it requires careful consideration of your financial situation and future goals. With a proactive approach and adherence to post-refinancing best practices, you can transform your student loan debt into a manageable part of your financial journey, paving the way for a more secure and prosperous future.