Debt consolidation loans in 2026 offer a strategic path to simplify finances, potentially lowering monthly payments and interest rates, with current offerings typically ranging from 7.5% to 18.2% based on creditworthiness and market conditions.
By: Rafaela on September 23, 2026
Debt consolidation loans in 2026 offer a strategic path to simplify finances, potentially lowering monthly payments and interest rates, with current offerings typically ranging from 7.5% to 18.2% based on creditworthiness and market conditions.
Navigating the complex world of personal finance can be challenging, especially when multiple debts are weighing you down. For many, debt consolidation loans in 2026 present a viable solution, promising simplified payments and potentially lower interest rates. But with rates ranging from 7.5% to 18.2%, understanding when and how to act is crucial.
Understanding Debt Consolidation in 2026
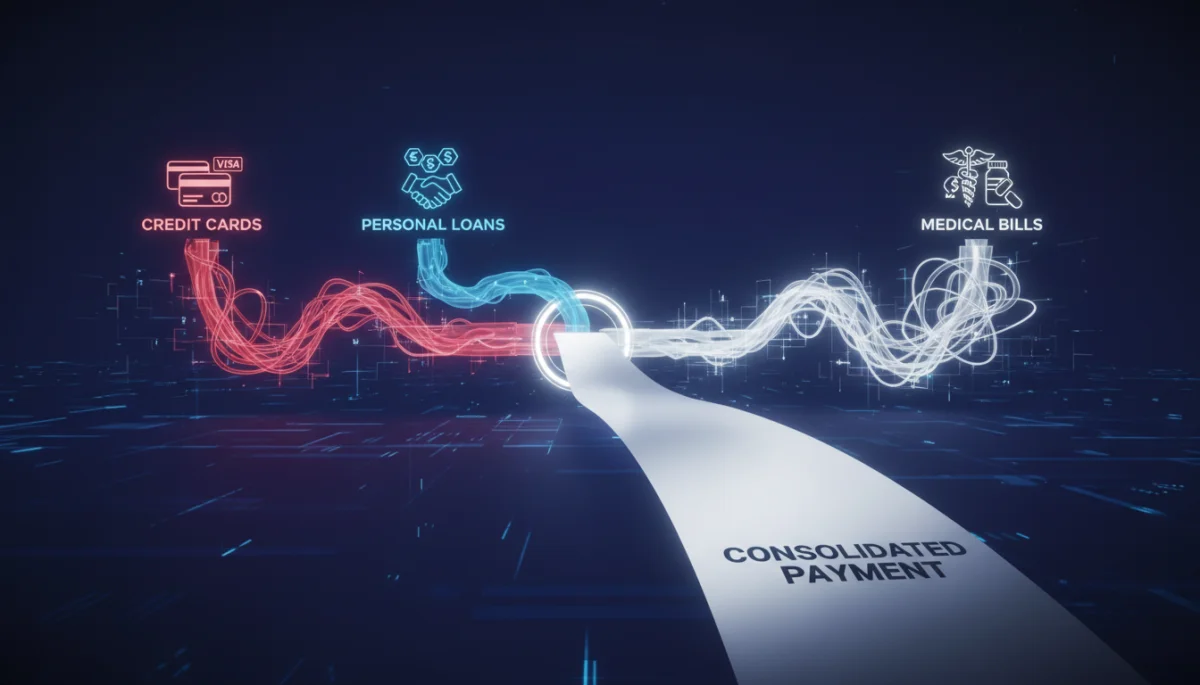
Debt consolidation involves taking out a single, larger loan to pay off several smaller debts, typically those with high interest rates like credit card balances or personal loans. The goal is to streamline your payments into one manageable monthly installment, often at a lower overall interest rate. In 2026, the financial landscape continues to evolve, influencing the availability and terms of these loans.
This strategy can simplify your financial life, making it easier to track your obligations and avoid missed payments. By converting multiple debts into a single one, you gain clarity and a clearer path to becoming debt-free. It’s a proactive approach to debt management that can alleviate significant financial stress.
The Core Mechanism of Consolidation
When you consolidate, the new loan’s interest rate becomes paramount. A lower rate means less money paid in interest over the life of the loan. This can result in substantial savings, freeing up funds for other financial goals or necessities.
Combines multiple debts into one payment.
Potentially secures a lower interest rate.
Simplifies monthly budgeting and tracking.
Offers a fixed repayment schedule.
Ultimately, understanding the mechanics of debt consolidation is the first step towards making an informed decision about whether it’s the right choice for your financial situation in the current economic climate of 2026. Evaluating your existing debts and their respective interest rates is essential before proceeding.
Current Interest Rate Landscape: 7.5% to 18.2%
The interest rates for debt consolidation loans in 2026 are heavily influenced by several factors, primarily your credit score, the lender, and the prevailing economic conditions. While a range of 7.5% to 18.2% is broad, it reflects the diversity in borrower profiles and market dynamics.
Borrowers with excellent credit scores and stable financial histories are more likely to qualify for the lower end of this spectrum, potentially securing rates closer to 7.5%. Conversely, individuals with less-than-perfect credit might find themselves offered rates towards the higher end, or even above 18.2%, depending on the lender’s risk assessment.
Factors Influencing Your Rate
Several key elements determine the interest rate you’ll be offered. A strong credit report is your best asset, demonstrating your reliability as a borrower. Lenders also consider your income, debt-to-income ratio, and the loan term.
Credit Score: Higher scores (700+) typically yield lower rates.
Income Stability: Consistent income reassures lenders of your repayment ability.
Debt-to-Income Ratio: A lower ratio indicates less financial strain.
Loan Term: Shorter terms often come with lower rates but higher monthly payments.
It’s vital to shop around and compare offers from multiple lenders to find the most competitive rate. Even a slight difference in interest can lead to significant savings over the life of the loan. Knowing your financial standing before applying empowers you in negotiations.
When is Debt Consolidation the Right Move?
Deciding if a debt consolidation loan is appropriate requires careful consideration of your financial situation and future goals. It’s not a universal solution but can be highly effective under specific circumstances. The primary indicator is often the presence of high-interest, unsecured debts.
If you’re struggling to manage multiple payments, or if the cumulative interest on your existing debts is preventing you from making progress, consolidation might be beneficial. It offers a fresh start, combining everything into one payment with a clear end date. However, it requires discipline to avoid accumulating new debt.
Evaluating Your Financial Health
Before committing, assess your current budget, spending habits, and ability to stick to a new repayment plan. Consolidation is a tool, not a magic bullet; its success depends on your commitment to financial responsibility.
You have multiple high-interest debts (e.g., credit cards).
You can secure a lower interest rate than your current average.
You have a stable income to manage the new monthly payment.
You are committed to avoiding new debt.
Consider the total cost of the loan, including any origination fees, to ensure it genuinely saves you money in the long run. A thorough cost-benefit analysis is an indispensable part of this decision-making process.
Comparing Loan Options and Lenders
The market for debt consolidation loans in 2026 is diverse, with various lenders offering different terms, rates, and features. From traditional banks and credit unions to online lenders, each has its own application process and eligibility criteria. It’s crucial to compare these options meticulously.
Online lenders, for example, often provide quicker approvals and more flexible terms, sometimes catering to a wider range of credit scores. Credit unions, on the other hand, might offer more personalized service and potentially lower rates for their members due to their non-profit structure.
Key Factors for Comparison
Beyond the interest rate, consider other aspects of the loan, such as repayment terms, fees, and customer service. A loan with a slightly higher interest rate but no origination fee might be more cost-effective than one with a lower rate and a significant upfront charge.
Interest Rate (APR): The true annual cost of borrowing.
Loan Term: How long you have to repay the loan.
Fees: Origination fees, prepayment penalties, late fees.
Customer Service: The lender’s reputation and support.
Utilize online comparison tools and get pre-qualified offers, which allow you to see potential rates without impacting your credit score. This proactive research can save you a substantial amount of money and ensure you choose the best fit for your financial situation.
Strategies for Securing the Best Rates (7.5% and Beyond)
To obtain the most favorable interest rates for debt consolidation loans in 2026, proactive financial management and strategic planning are essential. Aiming for the lower end of the 7.5% to 18.2% range requires demonstrating strong creditworthiness and understanding lender expectations.
Improving your credit score is arguably the most impactful step. This involves paying bills on time, reducing existing debt, and avoiding new credit applications before seeking consolidation. A higher score signals lower risk to lenders, making them more willing to offer competitive rates.
Boosting Your Credit Profile
Beyond a good credit score, a low debt-to-income ratio is highly attractive to lenders. This ratio indicates how much of your gross monthly income goes towards debt payments. Lowering it shows you have ample capacity to take on and repay new debt.
Improve Credit Score: Pay bills on time, reduce credit card balances.
Lower Debt-to-Income Ratio: Increase income or pay down existing debt.
Gather Documentation: Have proof of income and employment ready.
Consider a Co-signer: A co-signer with excellent credit can help secure a lower rate.
Additionally, having a clear understanding of your financial history and being prepared to explain any past issues can also work in your favor. Transparency and a well-thought-out plan for repayment can build trust with potential lenders, even if your credit isn’t perfect.
The Risks and Downsides of Consolidation
While debt consolidation offers numerous benefits, it’s not without its risks and potential downsides. Understanding these drawbacks is crucial for making an informed decision and avoiding pitfalls that could worsen your financial situation. The most significant risk is accumulating new debt after consolidating.
If you don’t address the underlying spending habits that led to the original debt, you might find yourself with a new consolidation loan and renewed credit card balances. This scenario leaves you in a worse financial position than before, with more debt to manage.
Potential Pitfalls to Avoid
Another common pitfall is extending the loan term to achieve lower monthly payments. While this can provide immediate relief, it often means paying more in total interest over the life of the loan. Always calculate the total cost, not just the monthly payment.
Accumulating New Debt: The biggest risk if spending habits aren’t changed.
Longer Repayment Terms: Can lead to paying more interest overall.
Fees and Charges: Origination fees can add to the total cost.
Impact on Credit Score: Initial dip from new hard inquiries.
It’s also important to be aware of any prepayment penalties, though these are less common with personal consolidation loans. Always read the fine print and understand all terms and conditions before signing any loan agreement. A well-informed decision minimizes risk.
Alternative Debt Management Strategies
Debt consolidation loans are just one tool in the arsenal of debt management. For some, alternative strategies might be more suitable, depending on the amount of debt, financial discipline, and credit profile. Exploring these options can provide a broader perspective and ensure you choose the most effective path.
One common alternative is a debt management plan (DMP) offered by credit counseling agencies. In a DMP, counselors negotiate with your creditors for lower interest rates and a single monthly payment, similar to consolidation, but without taking out a new loan. This can be beneficial if your credit score prevents you from qualifying for favorable loan rates.
Other Viable Options
Another approach is the debt snowball or debt avalanche method. The debt snowball focuses on paying off the smallest debts first to build momentum, while the debt avalanche prioritizes debts with the highest interest rates to save money. Both require discipline but don’t involve new credit.
Debt Management Plan (DMP): Negotiated payments through credit counseling.
Balance Transfer Credit Cards: Move high-interest debt to a card with 0% APR intro offer.
Home Equity Loans/Lines of Credit: Utilize home equity, but risks your home.
Each alternative has its own set of pros and cons. A balance transfer card can be excellent if you can pay off the debt during the promotional period, but standard rates can be high afterward. Home equity options offer low rates but put your home at risk if you default. Carefully weigh these against consolidation.
Key Aspect
Brief Description
Rate Range 2026
Typically 7.5% to 18.2%, influenced by credit score and market.
When to Act
Ideal for high-interest, multiple debts with a commitment to new financial habits.
Key Benefit
Simplified payments, potential interest savings, and clearer debt-free path.
Main Risk
Accumulating new debt if underlying spending issues aren’t resolved.
Frequently Asked Questions About Debt Consolidation
What is the average interest rate for debt consolidation loans in 2026?▼
In 2026, interest rates for debt consolidation loans typically range from 7.5% to 18.2%, largely depending on the borrower’s credit score, financial history, and the specific lender. Excellent credit can secure rates at the lower end of this spectrum.
How does my credit score affect my consolidation loan rate?▼
Your credit score is a primary determinant. A higher credit score (e.g., 700+) indicates lower risk to lenders, making you eligible for more favorable interest rates. Conversely, a lower score will generally result in higher offered rates.
Are there any hidden fees with debt consolidation loans?▼
Some debt consolidation loans may include origination fees, which are deducted from the loan amount. Other potential fees can include late payment charges or prepayment penalties, though these are less common. Always review the loan agreement thoroughly.
Can debt consolidation negatively impact my credit score?▼
Initially, applying for a new loan can cause a slight dip due to a hard inquiry. However, if managed responsibly, consolidating and making timely payments can improve your credit score over time by reducing credit utilization and showing consistent repayment behavior.
What are the alternatives to a debt consolidation loan?▼
Alternatives include debt management plans through credit counseling, balance transfer credit cards with introductory 0% APRs, or self-managed strategies like the debt snowball or debt avalanche method. Home equity loans are also an option but carry higher risk.
Conclusion
Debt consolidation loans in 2026 offer a compelling pathway for individuals seeking to simplify their financial obligations and reduce overall interest costs. With rates ranging from 7.5% to 18.2%, the key to success lies in understanding your financial standing, meticulously comparing lenders, and committing to responsible spending habits. While not a universal solution, for those burdened by high-interest debts and a clear plan for the future, consolidation can be a transformative step towards financial freedom. Always weigh the benefits against the risks and consider all available alternatives to ensure the chosen path aligns perfectly with your long-term financial health.