Understanding the latest payday loan regulations in 2026 is crucial for consumers to navigate the financial landscape safely and effectively avoid predatory lending practices.
By: Rafaela on September 23, 2026
Navigating the 2026 payday loan regulations is essential for consumers to understand their protections and identify legitimate lenders, thereby safeguarding against predatory practices.
In an ever-evolving financial landscape, staying informed about the latest regulatory changes is paramount, especially concerning short-term credit solutions. Understanding the latest regulations on payday loans: what you need to know in 2026 to avoid predatory lenders is not just good practice; it’s a critical shield against potential financial pitfalls. This guide aims to demystify the complexities of current payday loan laws, empowering you to make informed decisions and protect your financial well-being.
Understanding the Evolving Landscape of Payday Loan Regulations
The regulatory environment surrounding payday loans has seen significant shifts over the past few years, with 2026 bringing new nuances designed to enhance consumer protection. These changes reflect a continuous effort by federal and state authorities to curb predatory lending practices and ensure that borrowers have access to fair and transparent credit options.
For many, payday loans represent a quick solution for urgent financial needs. However, their high-interest rates and short repayment terms can often lead to a cycle of debt. The new regulations aim to address these inherent risks, providing clearer guidelines for lenders and stronger safeguards for consumers. It’s crucial for anyone considering a payday loan to be fully aware of these updated rules.
Federal Oversight and State-Specific Rules
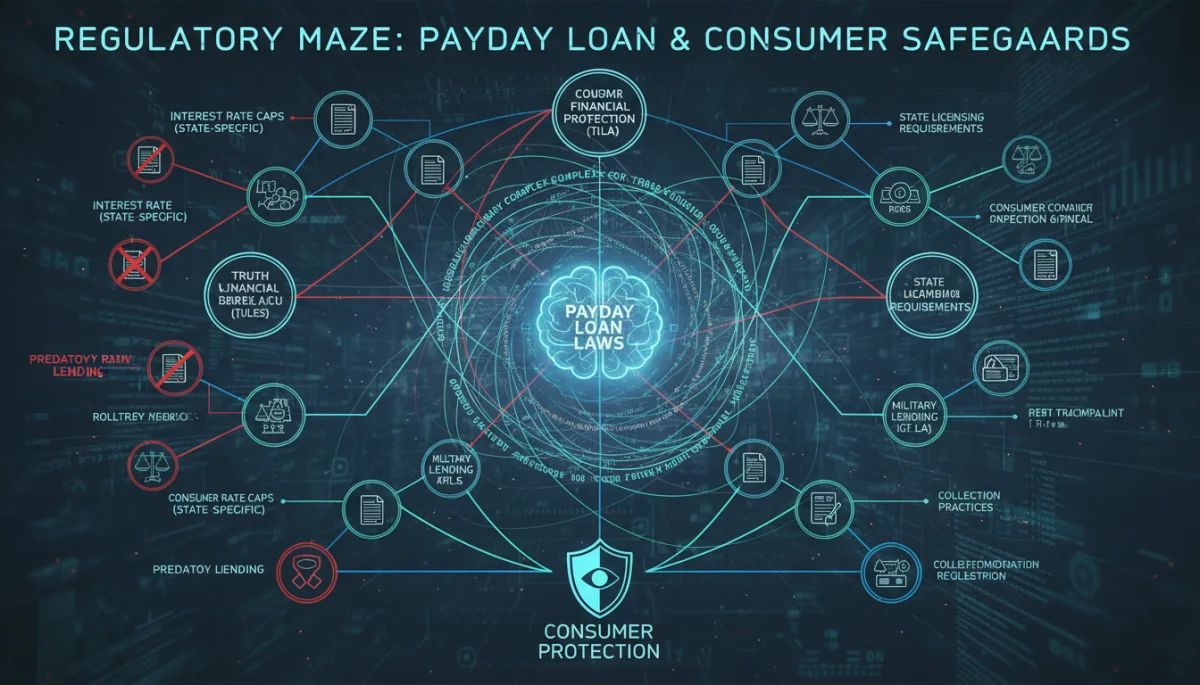
While federal agencies like the Consumer Financial Protection Bureau (CFPB) set broad guidelines, many critical regulations are enacted at the state level. This dual layer of oversight means that protections can vary significantly depending on where you live. Understanding both federal mandates and your state’s specific laws is key to navigating the payday loan market safely.
CFPB Directives: The CFPB continues to enforce rules regarding disclosure requirements, ensuring lenders clearly communicate terms, fees, and annual percentage rates (APRs).
State-Level Caps: Many states have specific interest rate caps and limits on loan amounts or repayment periods, which can offer stronger protections than federal guidelines alone.
Licensing Requirements: Lenders must often obtain state licenses, which can be revoked for non-compliance, adding another layer of accountability.
The interplay between federal and state regulations creates a complex mosaic of rules. Borrowers must proactively research the specific laws that apply in their jurisdiction to fully grasp their rights and the obligations of lenders. This proactive approach is your first line of defense against potentially unfair practices.
Ultimately, the evolving landscape of payday loan regulations in 2026 is a testament to the ongoing battle against predatory lending. These rules are designed to create a more equitable lending environment, but their effectiveness relies heavily on consumer awareness and vigilance. By staying informed, you contribute to a marketplace where ethical lending practices are prioritized.
Key Regulatory Changes in 2026 Affecting Payday Loans
The year 2026 brings several notable regulatory adjustments aimed at fortifying consumer defenses against the more exploitative aspects of the payday loan industry. These changes are a direct response to past issues, seeking to create a more transparent and fair lending environment. Understanding these specific updates is vital for any consumer seeking short-term financial assistance.
One of the primary focuses of the new regulations is on the affordability of these loans. Regulators are increasingly scrutinizing the ability of borrowers to repay loans without falling into a debt trap. This includes stricter guidelines on how lenders assess a borrower’s income and existing financial obligations before approving a loan.
Enhanced Disclosure Requirements
Transparency has always been a cornerstone of fair lending, and 2026 regulations push this further. Lenders are now mandated to provide clearer, more explicit disclosures of all loan terms, including the total cost of the loan, the APR, and any potential fees for late payments or rollovers. These disclosures must be presented in a way that is easily understandable, avoiding jargon and fine print.
Standardized Cost Sheets: Many jurisdictions are implementing standardized cost sheets, making it easier for borrowers to compare offers from different lenders side-by-side.
Clearer APR Representation: Lenders must emphasize the annual percentage rate more prominently, helping borrowers grasp the true cost of short-term borrowing.
Consequences of Non-Payment: The potential repercussions of failing to repay a loan must be clearly outlined, including impacts on credit scores and collection practices.
Beyond disclosures, there’s a growing emphasis on restricting loan rollovers and repeat borrowing. Some regulations now limit the number of times a borrower can roll over a loan or the total number of payday loans they can take out within a specific period. These measures are designed to break the cycle of debt that often ensnares vulnerable borrowers.
In essence, the 2026 regulatory changes are a concerted effort to empower consumers with knowledge and restrict practices that could lead to financial hardship. By being aware of these new rules, you can better protect your interests and ensure you engage with lenders who adhere to the highest standards of ethical conduct.
Identifying and Avoiding Predatory Lenders in 2026
Even with strengthened regulations, the landscape of short-term lending can still harbor predatory practices. It’s crucial for consumers to develop a keen eye for identifying red flags that distinguish legitimate lenders from those seeking to exploit financial vulnerability. Protecting yourself starts with recognizing these warning signs.
Predatory lenders often target individuals in desperate financial situations, offering seemingly easy solutions that come with hidden costs and traps. Their tactics can be subtle, making it difficult for an uninformed borrower to discern the danger until it’s too late. Education and awareness are your strongest tools in this fight.
Red Flags of Predatory Lending
Several indicators can signal that a lender might not have your best interests at heart. Being aware of these red flags can help you steer clear of potentially harmful financial agreements.
Lack of Transparency: If a lender is vague about fees, interest rates, or repayment terms, or pressures you to sign without fully explaining the contract, proceed with extreme caution.
Excessive Fees and APRs: While payday loans inherently have higher APRs, predatory lenders will often charge rates that far exceed reasonable limits, sometimes disguised as various ‘fees’.
Pressure Tactics: Aggressive sales tactics, demands for immediate decisions, or threats regarding credit scores if you don’t accept their terms are significant warning signs.
No Credit Check Promises: While some legitimate lenders offer loans without traditional credit checks, those who promise ‘guaranteed approval’ regardless of financial history might be masking high-risk, high-cost loans.
Unsolicited Offers: Be wary of unsolicited loan offers, especially those that seem too good to be true, as they can often lead to scams or predatory terms.
Beyond these immediate red flags, consider the lender’s reputation. A quick online search for reviews, complaints with the Better Business Bureau (BBB), or reports to the CFPB can provide valuable insights into a lender’s practices. A history of unresolved complaints is a major warning sign.
Ultimately, avoiding predatory lenders in 2026 requires a combination of vigilance, research, and a healthy dose of skepticism. If an offer feels off or a lender seems too eager, it’s always best to step back and explore alternative, more reputable options.
Consumer Rights and Protections Under 2026 Regulations
The 2026 regulatory updates are not just about setting rules for lenders; they are fundamentally about reinforcing consumer rights and providing stronger protections. Knowing your rights is an essential part of being an empowered borrower. These protections serve as your legal framework when engaging with short-term loan providers.
These regulations are designed to ensure that you are treated fairly, have access to clear information, and possess avenues for recourse if a lender acts improperly. They move beyond basic disclosures to establish a more equitable power dynamic between borrower and lender, particularly in the often-vulnerable context of payday loans.
Key Consumer Rights
Under the updated regulations, several core rights are emphasized, giving borrowers more leverage and security:
Right to Clear Information: You have the right to receive all loan terms, including APR, fees, and repayment schedule, in a clear, concise, and understandable format before signing any agreement.
Right to Rescind: In some jurisdictions, you may have a limited period (e.g., 24-48 hours) to cancel a loan agreement without penalty after signing. This ‘cooling-off’ period is a critical protection.
Protection Against Harassment: Lenders and debt collectors are prohibited from using abusive, unfair, or deceptive practices to collect debts. This includes limits on communication times and methods.
Right to Dispute: If you believe a lender has violated regulations or acted unfairly, you have the right to file a complaint with state regulators or federal agencies like the CFPB.
Limits on Rollovers: Depending on state law, there may be limits on how many times a loan can be rolled over or refinanced, preventing perpetual debt cycles.
Furthermore, many states are implementing or strengthening databases that track payday loan activity. These databases help prevent borrowers from taking out multiple loans simultaneously, which can quickly lead to unmanageable debt. This proactive measure benefits consumers by limiting their exposure to high-cost credit.
Understanding and asserting these rights is crucial. If you encounter a situation where you believe your rights have been violated, do not hesitate to seek assistance from consumer protection agencies or legal aid services. These resources are available to help you navigate disputes and ensure lenders adhere to the law.
Alternatives to Payday Loans in 2026
While payday loans can seem like the only option during a financial crunch, it’s important to remember that they are often a last resort due to their high costs. In 2026, a growing number of alternatives are available, many of which offer more favorable terms and are designed to support long-term financial health. Exploring these options before resorting to a payday loan can save you significant money and stress.
The goal should always be to find a solution that addresses your immediate need without creating a new, larger financial burden. Many of these alternatives are structured with lower interest rates, longer repayment periods, and more flexible terms, making them a safer choice for most borrowers.
Exploring Safer Financial Options
Consider these alternatives before committing to a payday loan:
Personal Installment Loans: Offered by banks and credit unions, these loans typically have lower interest rates and longer repayment terms, making them more manageable.
Credit Union Small-Dollar Loans: Many credit unions offer ‘payday alternative loans’ (PALs) with significantly lower APRs and more flexible repayment schedules than traditional payday loans.
Cash Advances from Credit Cards: While still expensive, a credit card cash advance often has a lower APR than a payday loan, though interest accrues immediately.
Borrowing from Friends or Family: If possible, a loan from a trusted individual can be interest-free or come with very flexible terms, avoiding the formal lending market altogether.
Community Assistance Programs: Many non-profit organizations and government agencies offer assistance for rent, utilities, and food, which can alleviate the immediate need for a loan.
Employer Advances: Some employers offer salary advances or flexible payment schedules, which can be a no-cost way to bridge a temporary financial gap.
Building an emergency fund, even a small one, can also significantly reduce the need for short-term, high-cost loans. Starting with small, consistent contributions can create a financial cushion over time. Additionally, improving your credit score can open doors to more affordable lending options in the future.
By proactively exploring these alternatives, you not only save money but also build a more resilient financial future. The emphasis in 2026 is on informed decision-making and leveraging safer, more sustainable credit solutions.
The Role of Technology in Payday Loan Regulation and Compliance
As the financial sector continues its rapid digital transformation, technology plays an increasingly critical role in both the enforcement of payday loan regulations and ensuring lender compliance. In 2026, digital tools and data analytics are central to monitoring the market, identifying non-compliant practices, and enhancing consumer protection. This technological integration is reshaping how regulations are applied and experienced.
The sheer volume of transactions and the speed at which they occur necessitate advanced systems for oversight. Regulators are leveraging AI and machine learning to detect patterns indicative of predatory lending, while lenders are employing technology to streamline compliance and improve transparency for borrowers.
Digital Tools for Oversight and Compliance
Technology is empowering both sides of the regulatory equation:
Automated Compliance Checks: Lenders are using software to automatically check loan applications against state and federal regulations, reducing errors and ensuring adherence to interest rate caps and disclosure requirements.
Regulatory Technology (RegTech): Specialized RegTech solutions are helping financial institutions manage their regulatory obligations more efficiently, from reporting to risk management.
Data Analytics for Regulators: Government agencies are utilizing big data analytics to monitor the payday loan market for trends, identify problematic lenders, and enforce regulations more effectively.
Secure Digital Disclosures: Technology facilitates the delivery of clear, standardized digital disclosures, ensuring borrowers receive and acknowledge critical loan information.
Blockchain for Transparency: While nascent, some are exploring blockchain technology to create immutable records of loan agreements, potentially enhancing transparency and trust.
Furthermore, technology is improving consumer access to information. Online platforms and mobile apps are making it easier for borrowers to research lenders, compare loan terms, and report suspicious activities. This democratized access to information empowers individuals to make more informed decisions and act as additional eyes on the market.
The ongoing integration of technology into payday loan regulation in 2026 signifies a move towards a more dynamic and responsive oversight system. This evolution aims to create a market where compliance is not just a burden but an integrated, automated part of the lending process, ultimately benefiting consumers through greater protection and transparency.
Future Outlook: What to Expect Beyond 2026
The regulatory journey for payday loans doesn’t end in 2026; it’s an ongoing process driven by market dynamics, technological advancements, and evolving consumer needs. Looking beyond the current year, we can anticipate further refinements and new initiatives aimed at striking a balance between access to credit and robust consumer protection. The goal remains to foster a financial ecosystem where short-term lending serves as a responsible tool, not a trap.
Future changes will likely be influenced by the effectiveness of current regulations, emerging financial products, and shifts in economic conditions. Continuous adaptation is key for regulators to keep pace with the innovative, sometimes disruptive, nature of the financial industry.
Anticipated Trends and Developments
Several areas are likely to see continued focus and potential regulatory action in the coming years:
Focus on Financial Health: Expect a greater emphasis on solutions that promote long-term financial health rather than just immediate relief. This could include incentives for lenders to offer financial literacy resources or credit-building products.
Digital Lending Scrutiny: As more lending moves online, regulators will likely intensify their scrutiny of digital lenders, particularly regarding data privacy, cybersecurity, and the use of algorithms in loan decision-making.
Harmonization of State Laws: There might be a push for greater harmonization of state-level payday loan regulations to reduce complexity for both lenders and borrowers operating across state lines.
Alternative Credit Scoring: The exploration of alternative credit scoring models, which consider factors beyond traditional credit reports, could expand access to credit for underserved populations while still maintaining consumer protections.
International Influence: Global trends in consumer finance regulation, particularly from countries with advanced financial protection frameworks, could influence future U.S. policies.
The role of artificial intelligence and machine learning in assessing creditworthiness will also be a critical area of discussion. While these technologies can offer efficiency, regulators will need to ensure they do not lead to discriminatory practices or exacerbate existing biases. Ethical AI in lending will be a significant theme.
In conclusion, the future of payday loan regulation is one of continuous evolution, driven by a commitment to consumer welfare and market integrity. Staying informed about these potential future developments will enable you to remain proactive in managing your financial decisions and advocating for fair lending practices.
Key Aspect
2026 Regulation Impact
Consumer Protection
Enhanced federal and state oversight to prevent predatory lending practices.
Transparency & Disclosure
Stricter rules for clear communication of loan terms, fees, and APRs to borrowers.
Avoiding Predatory Lenders
Increased awareness of red flags and access to safer alternatives like credit union loans.
Technological Role
Digital tools and data analytics are crucial for both regulatory oversight and lender compliance.
Frequently Asked Questions About Payday Loan Regulations
What are the most significant changes in 2026 payday loan regulations?▼
The most significant changes in 2026 regulations include enhanced disclosure requirements, stricter limits on loan rollovers, and increased scrutiny on lenders’ ability-to-repay assessments. These aim to prevent borrowers from falling into debt traps and ensure greater transparency in loan terms.
How can I identify a predatory payday lender?▼
Predatory lenders often exhibit red flags such as lack of transparency regarding fees and APRs, aggressive sales tactics, promises of guaranteed approval regardless of credit, and a history of customer complaints. Always research a lender’s reputation and carefully review all loan documents.
What alternatives to payday loans are available in 2026?▼
Safer alternatives include personal installment loans from banks or credit unions, Credit Union Small-Dollar Loans (PALs), credit card cash advances (with caution), borrowing from friends or family, and community assistance programs. Building an emergency fund is also a long-term solution.
Do federal or state laws have more impact on payday loans?▼
Both federal and state laws impact payday loans. While federal agencies like the CFPB set broad guidelines, state laws often impose specific interest rate caps, loan limits, and licensing requirements that can offer stronger, more localized consumer protections.
How does technology help in enforcing payday loan regulations?▼
Technology aids regulation through automated compliance checks for lenders, RegTech solutions for financial institutions, and data analytics used by regulators to monitor markets and identify non-compliant practices. It also facilitates secure digital disclosures for borrowers, enhancing transparency.
Conclusion
Navigating the world of payday loans in 2026 demands awareness and diligence. The latest regulations are a testament to ongoing efforts to protect consumers from predatory practices, but ultimately, the power lies in your hands. By understanding these new rules, recognizing the warning signs of unscrupulous lenders, and actively seeking out safer financial alternatives, you can safeguard your financial health. Empower yourself with knowledge, make informed choices, and ensure your short-term financial solutions don’t lead to long-term debt burdens. Your financial well-being depends on it.