Credit Application Denied 2026: 5-Point Recovery Plan
If your credit application is denied in 2026, it's crucial to understand the reasons, take immediate corrective actions to improve your financial standing, and strategize for future success.
By: Rafaela on September 23, 2026
When your credit application is denied in 2026, understanding the underlying causes and implementing a structured recovery plan is essential to rebuild your financial profile and achieve future approval.
Facing a credit application denial can be a disheartening experience, especially when you’re counting on that financing. But don’t let a rejection derail your financial aspirations. Understanding what to do when your credit application is denied in 2026: a 5-point recovery plan is your first step towards turning this setback into a strategic opportunity for financial growth.
Understanding the Denial: Your First Step to Recovery
When a lender denies your credit application, it’s not the end of the road; it’s a clear signal to investigate and understand the underlying issues. Lenders are legally obligated to provide you with a reason for their decision, or at least direct you to where you can obtain that information. This initial step is paramount because without knowing why you were denied, you cannot effectively address the problem.
Often, the denial letter will cite specific reasons, such as a low credit score, high debt-to-income ratio, or insufficient credit history. Sometimes, it might be something simpler, like an error on your application or a recent late payment you overlooked. It’s crucial not to guess; always seek out the official reason. This empowers you to move forward with targeted solutions rather than broad, ineffective actions.
Requesting the Adverse Action Notice
The Equal Credit Opportunity Act (ECOA) mandates that creditors must provide you with an Adverse Action Notice if your application is denied. This notice will either state the specific reasons for the denial or inform you of your right to request them within 60 days. It’s not just a formality; it’s your key to understanding the lender’s perspective.
Review the notice carefully for listed reasons.
If reasons aren’t explicit, contact the lender immediately.
Keep a record of all correspondence regarding the denial.
Accessing Your Credit Report and Score
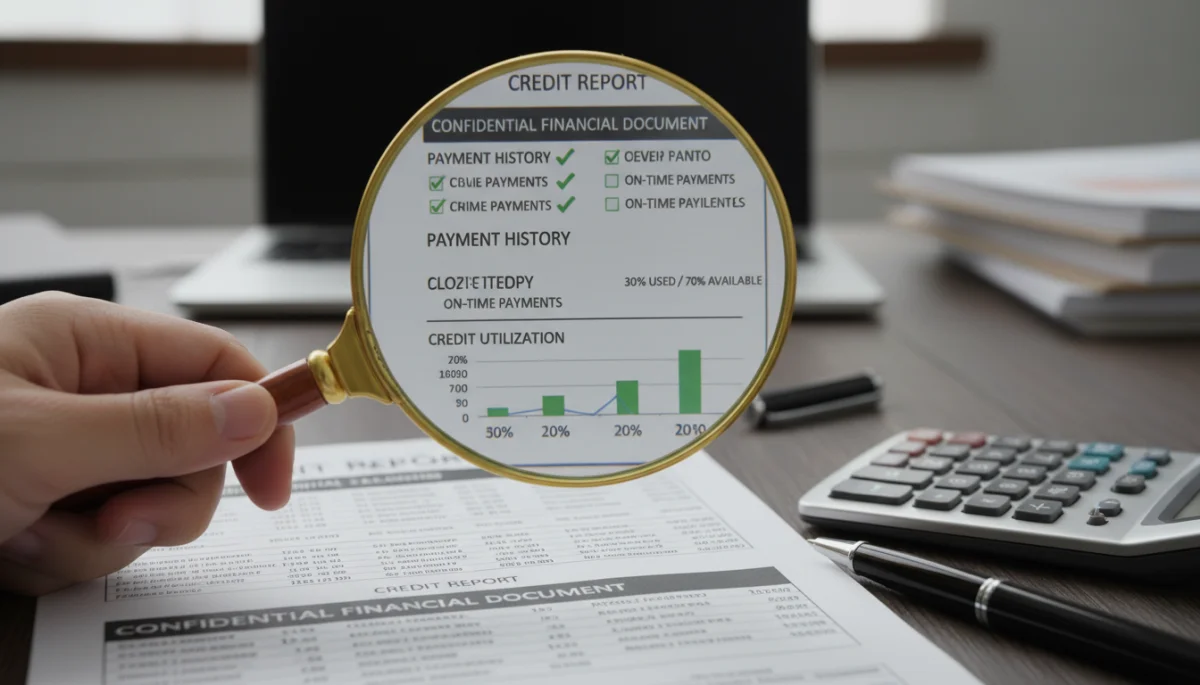
One of the most common reasons for a credit application denial is related to your credit report or score. In 2026, you can still access your credit reports from the three major bureaus (Equifax, Experian, and TransUnion) for free annually via AnnualCreditReport.com. Reviewing these reports is critical to identify discrepancies or negative marks that might be impacting your eligibility.
Your credit score, a numerical representation of your creditworthiness, is also a significant factor. While the free reports don’t always include scores, many credit card companies and financial institutions offer free access to one of your scores. Understanding your score and what factors influence it will provide valuable insight into the denial.
In conclusion, the first and most critical step after a credit application denial is to thoroughly understand why it happened. Requesting the adverse action notice and meticulously reviewing your credit reports and scores will provide the necessary insights to formulate an effective recovery plan.
Point 1: Review and Rectify Your Credit Report
Once you’ve identified the reasons for your credit application denial, the next logical step in your recovery plan is to meticulously review your credit reports and take action to rectify any inaccuracies. Your credit report is a detailed history of your financial behavior, and even a small error can significantly impact your creditworthiness, leading to a denial.
It’s not uncommon for credit reports to contain mistakes, ranging from incorrect personal information to fraudulent accounts opened in your name. These errors can drag down your credit score and make you appear riskier to lenders. A thorough review allows you to challenge any inaccuracies and ensure your report accurately reflects your financial standing.
Disputing Errors Effectively
If you find errors on your credit report, you have the right to dispute them with the credit bureaus. This process typically involves submitting a formal dispute letter, along with any supporting documentation, to the bureau reporting the incorrect information. The bureau then investigates your claim, usually within 30 days.
Submit disputes to each credit bureau reporting the error.
Follow up regularly on the status of your disputes.
Understanding Negative Entries
Beyond errors, your credit report may contain legitimate negative entries, such as late payments, collections, or bankruptcies. While these cannot be disputed unless they are inaccurate, understanding their impact and how long they remain on your report is important. Most negative information stays on your report for seven years, though bankruptcies can remain for up to ten.
Even with legitimate negative entries, there are strategies to mitigate their impact. For instance, if you have an old collection account, you might consider negotiating a ‘pay for delete’ with the collector, though this is not guaranteed. The goal is to ensure your report is as clean and accurate as possible, presenting the best version of your financial history to potential lenders.
In essence, a comprehensive review of your credit reports, coupled with proactive measures to dispute errors and understand legitimate negative entries, forms a crucial pillar of your recovery plan after a credit application denied notice. This step ensures your foundation is solid for future applications.
Point 2: Improve Your Credit Score Strategically
A low credit score is a frequent culprit behind a credit application denial. Therefore, a critical component of your 5-point recovery plan is to strategically improve your credit score. This isn’t an overnight fix, but consistent effort over time can lead to significant improvements, opening doors to better financial opportunities.
Understanding the factors that contribute to your credit score is the first step. Payment history, credit utilization, length of credit history, new credit, and credit mix all play a role. Focusing on these areas will yield the most impactful results in boosting your score.
Prioritizing Payment History
Your payment history is the most influential factor in your credit score, accounting for about 35% of your FICO score. Consistently making all your payments on time is paramount. Even one late payment can have a significant negative impact. Set up reminders, automate payments, or use a budgeting app to ensure you never miss a due date.
If you have past late payments, the best strategy is to continue making on-time payments going forward. The impact of older late payments diminishes over time as newer, positive payment history accumulates. Patience and discipline are key here.
Managing Credit Utilization
Credit utilization, the amount of credit you’re using compared to your total available credit, accounts for about 30% of your credit score. Keeping this ratio low, ideally below 30%, is crucial. For example, if you have a credit card with a $10,000 limit, try to keep your balance below $3,000.
To improve your credit utilization, you can either pay down existing balances or, if possible, increase your credit limits (but only if you can trust yourself not to spend more). Paying off your balances in full each month is the ideal scenario, as it not only helps your credit score but also saves you money on interest.
Building a Positive Credit Mix and History
While less impactful than payment history and utilization, having a mix of different types of credit (e.g., installment loans and revolving credit) and a long credit history can positively influence your score. Avoid opening too many new accounts at once, as this can temporarily lower your score due to multiple hard inquiries.
For those with limited credit history, consider options like secured credit cards or becoming an authorized user on a trusted individual’s account. These can help establish a positive payment history and build your credit profile over time.
In summary, improving your credit score strategically involves a disciplined approach to on-time payments, responsible credit utilization, and thoughtful credit management. This sustained effort will be instrumental in overcoming a credit application denied situation and achieving future approvals.
Point 3: Reduce Debt and Improve Your Debt-to-Income Ratio
Another significant factor that often leads to a credit application denial is a high debt-to-income (DTI) ratio. Lenders use this ratio to assess your ability to manage monthly payments and take on additional debt. A high DTI indicates that too much of your income is already allocated to debt payments, making you a higher risk for new credit.
Reducing your overall debt and, consequently, improving your DTI ratio is a powerful step in your recovery plan. This not only makes you a more attractive borrower but also frees up more of your income for other financial goals.
Calculating and Understanding Your DTI
Your debt-to-income ratio is calculated by dividing your total monthly debt payments by your gross monthly income. For instance, if your monthly debt payments (credit cards, student loans, car loans, mortgage) total $1,500 and your gross monthly income is $5,000, your DTI is 30% ($1,500 / $5,000). Most lenders prefer a DTI of 36% or lower, though this can vary by loan type.
Understanding your current DTI is the first step toward improving it. Once you know where you stand, you can set realistic goals for reduction.
Strategies for Debt Reduction
There are several effective strategies for reducing debt. One popular method is the ‘debt snowball’ where you pay off your smallest debts first, gaining momentum as each debt is eliminated. Another is the ‘debt avalanche,’ which focuses on paying off debts with the highest interest rates first, saving you money in the long run.
Create a detailed budget to identify areas for cutting expenses.
Prioritize high-interest debts for faster payoff.
Consider debt consolidation (e.g., a balance transfer credit card or personal loan) if it offers a lower interest rate and simplifies payments, but be cautious not to accrue new debt.
Look for opportunities to increase your income, even temporarily.
Impact on Future Applications
Reducing your debt not only improves your DTI but also often positively impacts your credit utilization, a key component of your credit score. As your DTI decreases, you present a much more favorable financial profile to lenders, significantly increasing your chances of approval for future credit applications.
Ultimately, actively working to reduce your debt and improve your debt-to-income ratio is a fundamental step in addressing a credit application denied situation. It demonstrates financial responsibility and enhances your capacity to manage new credit responsibly.
Point 4: Build a Positive Financial History and Diversify Credit
For some, a credit application denial isn’t due to poor credit, but rather a lack of sufficient credit history. Lenders need to see a track record of responsible borrowing and repayment to assess your risk. This point in your recovery plan focuses on establishing and diversifying your credit profile in a positive way.
Even if you have some credit, a limited mix of credit types can be a disadvantage. Diversifying your credit portfolio by including both revolving and installment accounts can demonstrate your ability to manage different forms of debt responsibly.
Establishing New Credit Responsibly
If you have little to no credit history, your immediate goal should be to establish it. Secured credit cards are an excellent starting point. These cards require a cash deposit, which acts as your credit limit, making them low-risk for lenders. By using them responsibly and paying on time, you build positive payment history.
Another option is a credit-builder loan, offered by some credit unions and community banks. With these loans, the money is held in a savings account while you make payments, and you receive the funds once the loan is paid off. This is a safe way to demonstrate repayment ability.
Considering Authorized User Status
Becoming an authorized user on a trusted individual’s credit card can also help build your credit history. The primary cardholder’s positive payment history and low utilization will appear on your credit report. However, choose wisely, as their negative actions could also impact you. Ensure the primary user is financially responsible.
Apply for a secured credit card and use it for small, regular purchases.
Explore credit-builder loans from local financial institutions.
If appropriate, become an authorized user on a family member’s established account.
Maintain low balances and pay on time for all new accounts.
Diversifying Your Credit Mix
Once you have established a foundational credit history, consider diversifying your credit mix. This means having a healthy balance of revolving credit (like credit cards) and installment loans (like a car loan or personal loan). This shows lenders you can handle different types of financial commitments. However, only take on new credit if you genuinely need it and can afford the payments.
By proactively building and diversifying your credit history, you address a common reason for a credit application denied outcome, demonstrating to future lenders that you are a reliable and experienced borrower.
Point 5: Reapply Strategically and Seek Alternative Options
After diligently working through the previous four points of your recovery plan, you’ll be in a much stronger position to reapply for credit. However, reapplying strategically is just as important as the improvements you’ve made. Hasty or uninformed applications can lead to further denials and unnecessary hard inquiries on your credit report.
This final point also involves exploring alternative financing options, especially if traditional credit remains elusive or if your needs are immediate. There are various avenues available that cater to different credit profiles.
Choosing the Right Lenders and Products
When you’re ready to reapply, don’t just apply for the same product from the same lender. Research lenders that cater to individuals with rebuilding credit or those with specific financial situations. Look for pre-qualification options, which allow you to see your approval odds without a hard inquiry impacting your score.
Consider starting with smaller credit lines or different types of loans that are easier to qualify for, such as a smaller personal loan or a secured loan. Successfully managing these will further strengthen your credit profile for larger applications in the future.
Exploring Alternative Financing
If a traditional credit product is still out of reach, or if your needs are more immediate, consider alternative financing options. These can include:
Credit Unions: Often more flexible and willing to work with members with less-than-perfect credit.
Community Development Financial Institutions (CDFIs): Offer affordable financial products and services to underserved communities.
Secured Loans: Using an asset (like a savings account or car) as collateral can make it easier to qualify for a loan.
Peer-to-Peer Lending: Online platforms connect borrowers with individual investors, sometimes offering more lenient terms.
Maintaining Vigilance and Patience
Even after approval, the work isn’t over. Continue to monitor your credit report, make all payments on time, and manage your credit utilization responsibly. Building and maintaining excellent credit is an ongoing process. Patience is crucial throughout this entire recovery process; significant credit improvement takes time, often several months to a year or more.
By reapplying strategically and being open to alternative options, you complete your 5-point recovery plan, transforming a credit application denied experience into a pathway toward stronger financial health and future success.
Key Recovery Step
Brief Description
Understand Denial
Obtain Adverse Action Notice and review credit reports for reasons.
Rectify Credit Report
Dispute any errors and understand legitimate negative entries.
Improve Credit Score
Focus on timely payments and low credit utilization.
Reduce Debt & DTI
Lower overall debt to improve your debt-to-income ratio.
Frequently Asked Questions About Credit Denial Recovery
How long does it take to recover from a credit application denial?▼
Recovery time varies based on the reasons for denial and your actions. Minor issues like a single late payment might resolve in a few months, while significant credit report errors or high debt levels could take six months to over a year of consistent effort to improve. Patience and persistent positive financial habits are key.
Will applying for too much credit hurt my score after a denial?▼
Yes, multiple hard inquiries from numerous credit applications in a short period can negatively impact your credit score. It’s advisable to wait at least six months after a denial to reapply, giving you time to implement your recovery plan and allowing the initial hard inquiry to lessen its impact on your score.
What is the most effective way to boost my credit score quickly?▼
The most effective way to boost your credit score is to consistently make all payments on time and keep your credit utilization ratio below 30%. Paying down existing credit card balances significantly can show immediate improvement. Also, disputing any errors on your credit report can quickly remove negative marks.
Should I try a secured credit card if my application was denied?▼
Yes, a secured credit card is an excellent option if your credit application was denied due to limited credit history or a low credit score. They require a security deposit, making them easier to obtain. Responsible use, including on-time payments, helps build a positive credit history and improve your score over time.
Can a credit counseling agency help after a denial?▼
Absolutely. A reputable credit counseling agency can provide personalized advice, help you create a budget, and even assist with debt management plans. They can offer valuable insights into your financial situation and guide you through the process of improving your creditworthiness after a denial, often for free or low cost.
Conclusion
Experiencing a credit application denied can be a difficult moment, but it’s crucial to view it as an opportunity for financial introspection and improvement. By diligently following this 5-point recovery plan – understanding the denial, rectifying your credit report, strategically improving your credit score, reducing debt, and reapplying wisely – you empower yourself to navigate future financial endeavors with confidence. Remember, building strong credit is a journey, not a sprint, and every step you take towards financial health is a step towards a more secure future.