Home Equity Loans vs. HELOCs 2026: Funding for US Homeowners
For US homeowners in 2026 seeking funding, understanding the distinctions between a home equity loan and a home equity line of credit (HELOC) is crucial for making an informed financial decision based on interest rates, repayment structures, and flexibility.
By: Rafaela on September 23, 2026
For US homeowners in 2026 seeking funding, understanding the distinctions between a home equity loan and a home equity line of credit (HELOC) is crucial for making an informed financial decision based on interest rates, repayment structures, and flexibility.
As 2026 unfolds, many US homeowners are evaluating their financial options, especially when significant expenses arise or investment opportunities beckon. Navigating the landscape of borrowing can be complex, particularly when considering your home’s value as a source of funds. This guide will delve into the critical differences between a Home Equity Loan vs. HELOCs in 2026: A Comparison for US Homeowners Seeking Funding, helping you understand which option aligns best with your financial goals and risk tolerance.
Understanding home equity: your financial foundation
Home equity represents a significant asset for many homeowners, embodying the portion of your home that you truly own, free and clear of mortgage debt. As property values appreciate and you pay down your mortgage principal, your equity grows, providing a potential wellspring of funds for various needs. In 2026, with evolving market dynamics, leveraging this equity wisely is more important than ever.
Calculating your home equity is straightforward: it’s your home’s current market value minus your outstanding mortgage balance. For instance, if your home is appraised at $400,000 and you owe $200,000 on your mortgage, you have $200,000 in equity. Lenders typically allow you to borrow a percentage of this equity, usually up to 80% or 90%, depending on their policies and your creditworthiness.
The power of equity: unlocking opportunities
Your home equity isn’t just a number on a statement; it’s a financial tool that can be used to achieve various objectives. From home renovations that increase your property’s value to consolidating high-interest debt, the strategic use of home equity can significantly impact your financial health.
Home improvements: Fund renovations that boost your home’s value and enhance your living space.
Debt consolidation: Combine higher-interest debts into a single, potentially lower-interest payment.
Education expenses: Cover tuition costs for yourself or your children.
Emergency funds: Create a safety net for unexpected financial challenges.
Understanding the concept of home equity is the first step toward making an informed decision about whether a home equity loan or a HELOC is the right choice for your funding needs in 2026. Both options tap into this valuable asset, but they do so in fundamentally different ways, each with its own set of advantages and considerations.
Home equity loans: predictable payments for specific needs
A home equity loan, often referred to as a second mortgage, provides a lump sum of money upfront, which is then repaid over a fixed period with a fixed interest rate. This structure makes it a predictable borrowing option, favored by homeowners who have a clear, one-time funding need and prefer consistent monthly payments.
When you take out a home equity loan, the interest rate is locked in for the entire life of the loan. This means your monthly payments will remain the same, making budgeting straightforward and shielding you from potential interest rate hikes. This predictability is a significant advantage, particularly in an economic climate where interest rates might fluctuate.
Key features and benefits
Home equity loans are ideal for specific, large expenses where you know the exact amount you need. The fixed interest rate and set repayment schedule offer peace of mind and financial stability.
Lump sum disbursement: Receive all the funds at once, suitable for a single large expense.
Fixed interest rate: Your interest rate and monthly payments remain constant throughout the loan term.
Predictable budgeting: Easy to plan your finances with consistent payments.
Clear repayment schedule: You know exactly when the loan will be paid off.
However, it’s important to remember that a home equity loan is secured by your home. Failure to make payments could result in foreclosure. Therefore, careful consideration of your ability to repay is paramount before committing to this type of financing.
HELOCs: flexible credit lines for ongoing expenses
A Home Equity Line of Credit (HELOC) operates more like a credit card, allowing you to borrow money as needed, up to a pre-approved limit. Unlike a home equity loan, you don’t receive a lump sum; instead, you can draw on the line of credit during a specified draw period, typically 5-10 years. This flexibility makes HELOCs suitable for ongoing projects or unexpected expenses.
HELOCs usually come with a variable interest rate, meaning your monthly payments can change based on market fluctuations. While this can offer lower initial payments, it also introduces the risk of higher payments if rates increase. Understanding the potential for rate changes is crucial for homeowners considering a HELOC in 2026.
Draw and repayment periods
HELOCs are structured in two phases: the draw period and the repayment period. During the draw period, you can access funds as needed and typically only pay interest on the amount you’ve borrowed. Once the draw period ends, the repayment period begins, and you must start repaying both the principal and interest, often at a higher monthly payment.
The variable interest rate can be a double-edged sword. While it might offer lower initial payments, an upward trend in market rates could significantly increase your monthly burden. Homeowners should assess their comfort level with this variability and consider potential future rate environments. A HELOC provides unparalleled flexibility for those with evolving financial needs, but it demands careful management and an understanding of its variable nature.
Comparing interest rates and repayment structures in 2026
One of the most significant distinctions between home equity loans and HELOCs lies in their interest rates and repayment structures. In 2026, market conditions and individual lender policies will continue to shape these aspects, making a detailed comparison essential for US homeowners.
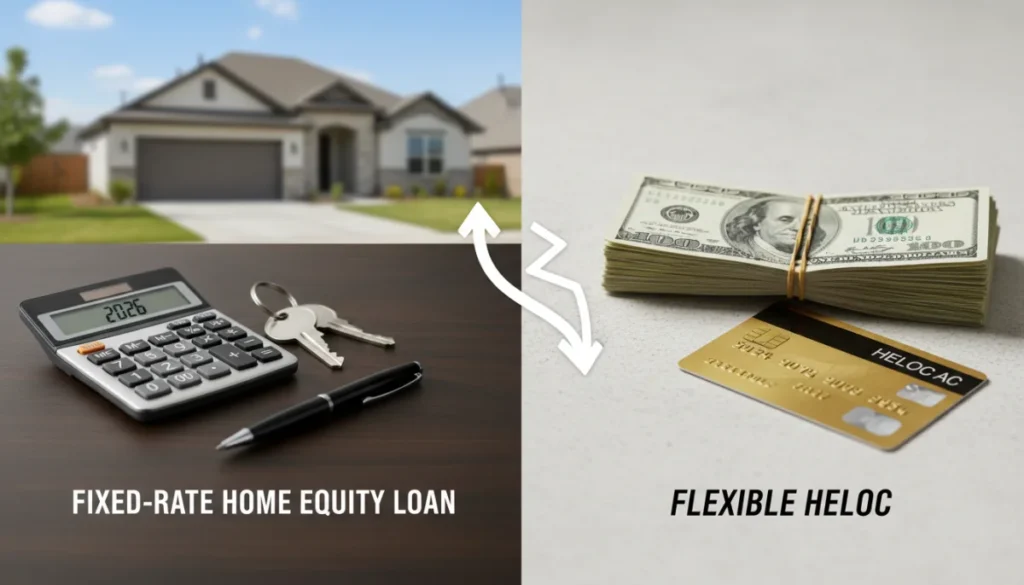
Home equity loans, with their fixed interest rates, offer stability. You’ll know exactly what your monthly payment will be from day one until the loan is paid off. This is particularly appealing in times of economic uncertainty or when interest rates are expected to rise. The downside is that if rates drop significantly, you won’t benefit unless you refinance.
HELOCs, on the other hand, typically feature variable interest rates, often tied to an index like the prime rate. This means your payments can go up or down. While this offers the potential for lower payments if rates fall, it also carries the risk of higher payments if rates climb. Some HELOCs offer an introductory fixed rate, or a cap on how high the rate can go, providing some protection.
Understanding the repayment differences
Home Equity Loan: Repayment begins immediately with principal and interest payments, fixed for the life of the loan.
HELOC: Often has an interest-only payment option during the draw period, followed by principal and interest payments during the repayment period, which can lead to a significant payment increase.
Prepayment penalties: Some lenders may charge penalties for paying off a loan or HELOC early, so always check the terms.
Closing costs: Both options typically involve closing costs, which can vary by lender and state.
The choice between a fixed-rate home equity loan and a variable-rate HELOC largely depends on your comfort with risk, your financial predictability, and your outlook on future interest rate movements. Carefully evaluating these factors in the context of 2026’s economic landscape is crucial for making the right borrowing decision.
When to choose a home equity loan
A home equity loan is often the preferred choice for homeowners who have a clearly defined need for a specific amount of money and desire the security of predictable payments. This option shines when you have a one-time, significant expense and want to avoid the potential fluctuations of a variable interest rate.
Consider a home equity loan if you are planning a major home renovation project with a fixed budget, consolidating high-interest debt into a single, manageable payment, or financing a large, one-time expense like a wedding or medical bills. The fixed interest rate means your monthly payments will not change, making it easier to budget and manage your finances over the long term, regardless of market shifts in 2026.
Ideal scenarios for a home equity loan
Major home renovations: When you have a detailed plan and a clear budget for extensive upgrades.
Debt consolidation: To streamline multiple debts into one payment with a potentially lower, fixed interest rate.
Fixed large expenses: For tuition, medical bills, or other substantial, non-recurring costs.
Budget predictability: If you prioritize stable monthly payments and want to avoid interest rate risk.
The certainty provided by a home equity loan can be a significant advantage, particularly for those who prefer strict budgeting and want to know their financial obligations well in advance. It offers a structured approach to borrowing, ensuring that your repayment plan remains consistent throughout the loan’s duration.
When a HELOC makes more sense
For homeowners facing uncertain or ongoing expenses, a Home Equity Line of Credit (HELOC) offers a level of flexibility that a traditional home equity loan cannot match. A HELOC is essentially a revolving credit line, allowing you to borrow, repay, and re-borrow funds up to your approved limit during the draw period.
This flexibility is particularly beneficial for projects with variable costs, such as a multi-stage home renovation where expenses might evolve over time, or for creating an emergency fund that you can tap into only when needed. The ability to access funds as required, rather than receiving a lump sum, means you only pay interest on the amount you actually use, which can lead to lower overall interest costs if managed properly.
Optimal uses for a HELOC
Ongoing home improvements: For projects where costs might fluctuate or stages are spread out.
Emergency fund: To have readily available funds for unexpected financial crises without drawing a lump sum immediately.
Variable expenses: When you need access to capital over time, but the exact amounts or timing are uncertain.
Interest-only payments: During the draw period, you might have the option to make interest-only payments, offering lower initial monthly obligations.
While the variable interest rate of a HELOC can introduce some payment uncertainty, its adaptability makes it a powerful tool for homeowners who need dynamic access to their home equity. Careful financial planning and monitoring of interest rate trends are key to maximizing the benefits of a HELOC in 2026.
Choosing the right option for your 2026 financial goals
Deciding between a home equity loan and a HELOC in 2026 requires a thorough assessment of your financial situation, borrowing needs, and risk tolerance. There isn’t a one-size-fits-all answer; the best choice depends entirely on your specific circumstances and what you aim to achieve with the borrowed funds.
If you have a clear, one-time financial need and prefer the stability of fixed monthly payments, a home equity loan offers predictability and peace of mind. This option is ideal for those who want to budget precisely and avoid any surprises related to interest rate fluctuations. It’s a straightforward approach to leveraging your home equity for a defined purpose.
Conversely, if your financial needs are ongoing, unpredictable, or you anticipate requiring funds at various intervals, a HELOC provides the flexibility you need. Its revolving credit nature allows you to draw funds as necessary and only pay interest on what you use. However, you must be comfortable with variable interest rates and the potential for changing monthly payments.
Factors to consider for your decision
Purpose of funds: Is it a single, large expense or ongoing, flexible needs?
Interest rate preference: Do you prefer fixed predictability or variable potential savings/risks?
Repayment comfort: Can you handle potentially increasing payments with a HELOC, or do you need stable payments?
Market outlook: What are the projections for interest rates in 2026 and beyond?
Credit score and debt-to-income ratio: These will influence your eligibility and terms for both options.
Ultimately, the decision should be based on a careful comparison of the terms offered by various lenders, an honest evaluation of your financial capacity, and a clear understanding of how each product aligns with your long-term financial strategy. Consulting with a financial advisor can also provide personalized insights to help you make the most informed choice for your home equity funding in 2026.
Feature
Description
Disbursement
Lump sum for Home Equity Loan; revolving credit line for HELOC.
Interest Rate
Fixed for Home Equity Loan; variable for HELOC (usually).
Repayment
Fixed monthly payments for Home Equity Loan; flexible/interest-only during draw for HELOC.
Best Use
Specific, large expenses for Home Equity Loan; ongoing, flexible needs for HELOC.
Frequently asked questions about home equity funding
What is the primary difference between a home equity loan and a HELOC?▼
A home equity loan provides a lump sum with a fixed interest rate and consistent payments. A HELOC is a revolving line of credit with a variable interest rate, allowing you to borrow as needed up to a limit, similar to a credit card.
Are interest rates for home equity products tax-deductible in 2026?▼
Under current tax laws, interest on home equity loans and HELOCs may be tax-deductible if the funds are used to buy, build, or substantially improve the home that secures the loan. Consult a tax professional for personalized advice.
What are the risks associated with a HELOC’s variable interest rate?▼
The main risk is that your monthly payments can increase significantly if market interest rates rise. This can make budgeting more challenging and potentially strain your financial resources if not properly anticipated.
Can I get a home equity loan or HELOC with bad credit?▼
While challenging, it’s not impossible. Lenders typically prefer good credit, but some may offer options with higher interest rates or stricter terms if you have significant equity. Improving your credit before applying is always recommended.
What happens at the end of a HELOC’s draw period?▼
At the end of the draw period, you can no longer borrow funds. You then enter the repayment period, where you must repay both principal and interest, often resulting in substantially higher monthly payments than during the draw period.
Conclusion
Navigating the choices between a home equity loan and a HELOC in 2026 is a significant financial decision for US homeowners seeking funding. Both options offer valuable ways to unlock the equity in your home, but their distinct features in terms of interest rates, disbursement, and repayment schedules cater to different financial needs and risk appetites. By carefully evaluating your specific goals, understanding the market’s potential movements, and considering your comfort with financial predictability versus flexibility, you can confidently choose the home equity solution that best supports your personal finance strategy for the years to come. Always remember to compare offers from multiple lenders and seek professional advice to ensure the decision aligns perfectly with your individual circumstances.