Debt Consolidation Loans 2026: Reduce Interest by 15% in US
Exploring debt consolidation loans in 2026 offers a strategic pathway for US consumers to significantly reduce interest payments, potentially by 15% or more, by combining multiple high-interest debts into a single, more manageable loan.
By: Rafaela on September 23, 2026
Exploring debt consolidation loans in 2026 offers a strategic pathway for US consumers to significantly reduce interest payments, potentially by 15% or more, by combining multiple high-interest debts into a single, more manageable loan.
Are you feeling overwhelmed by multiple debt payments and high-interest rates? Many Americans find themselves in a similar situation, searching for a viable path to financial relief. Understanding debt consolidation loans in 2026 could be your key to simplifying your finances and potentially reducing your interest payments by a significant margin, perhaps even 15% or more, allowing you to regain control of your financial future.
Understanding Debt Consolidation Loans in 2026
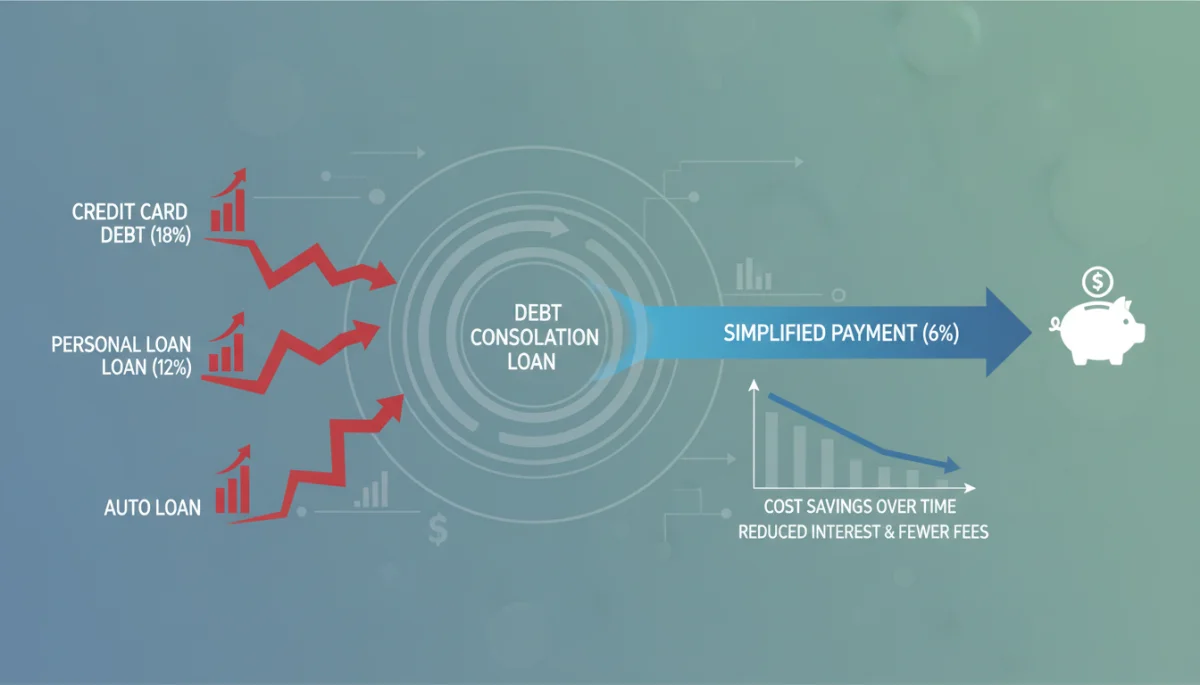
Debt consolidation loans are financial tools designed to streamline your repayment process by combining several unsecured debts, such as credit card balances, personal loans, or medical bills, into a single, new loan. This approach often comes with a lower interest rate and a more manageable monthly payment, making it easier to track and pay down your debt.
The landscape of personal finance is constantly evolving, and 2026 brings new considerations for borrowers. Economic indicators, interest rate forecasts, and lender policies all play a role in determining the availability and attractiveness of these loans. Staying informed about these factors is crucial for making an educated decision.
What defines a debt consolidation loan?
At its core, a debt consolidation loan is a personal loan specifically used to pay off other debts. Instead of making multiple payments to various creditors, you make one payment to a single lender. This simplification can lead to reduced stress and a clearer financial picture.
Single monthly payment: Consolidating makes managing debt simpler.
Potentially lower interest rates: A new loan might offer better terms than existing high-interest debts.
Fixed repayment term: Provides a clear timeline for becoming debt-free.
The primary benefit of debt consolidation is the potential to save money on interest. By securing a loan with a lower annual percentage rate (APR) than your current debts, you can reduce the total cost of borrowing over time. This is particularly impactful for those with high-interest credit card debt.
The Economic Outlook: Why 2026 is Crucial for Debt Consolidation
The economic climate significantly influences the debt consolidation market. As we look towards 2026, several macroeconomic factors could shape the options available to consumers in the US. Understanding these trends can help you decide if now is the right time to pursue consolidation.
Interest rates set by the Federal Reserve, inflation levels, and overall economic growth all impact lending conditions. A period of stable or declining interest rates could present an opportune moment for borrowers to secure favorable terms on a consolidation loan. Conversely, rising rates might make it harder to achieve significant interest savings.
Federal Reserve policy and interest rates
The Federal Reserve’s monetary policy plays a pivotal role in the cost of borrowing. If the Fed maintains or lowers its benchmark interest rate, lenders may offer more competitive rates on personal loans, including those for debt consolidation. Keeping an eye on Fed announcements will be key.
Impact on variable rates: Existing variable-rate debts could become more expensive if rates rise.
Opportunity for fixed rates: Consolidation can lock in a fixed rate, protecting against future increases.
Lender competitiveness: A stable rate environment can foster competition among lenders.
Beyond interest rates, the broader economic health of the US also matters. A strong job market and steady economic growth generally mean that lenders are more willing to extend credit. This can translate into better loan terms and more accessible options for those seeking to consolidate their debts.
Analyzing Options: Types of Debt Consolidation Loans
Not all debt consolidation solutions are created equal. In 2026, consumers will have a variety of options, each with its own advantages and disadvantages. Choosing the right type of loan depends on your financial situation, credit score, and overall goals.
The most common forms of debt consolidation include personal loans, balance transfer credit cards, and home equity loans or lines of credit (HELOCs). Each of these methods approaches debt repayment differently, offering distinct pathways to reducing interest and simplifying payments.
Personal loans for debt consolidation
A personal loan is a popular choice for debt consolidation because it is typically an unsecured loan, meaning it doesn’t require collateral. Lenders assess your creditworthiness, income, and debt-to-income ratio to determine eligibility and interest rates. These loans usually have fixed interest rates and repayment terms.
The main advantage of a personal loan for consolidation is the predictability of payments and the potential for a lower, fixed interest rate compared to revolving credit. This makes budgeting easier and ensures a clear path to becoming debt-free.
Balance transfer credit cards
Balance transfer credit cards offer an introductory 0% APR period, typically ranging from 12 to 21 months. This can be an excellent option if you can pay off the consolidated debt entirely before the promotional period ends, effectively avoiding interest charges. However, these cards often come with a balance transfer fee.
0% APR introductory period: Ideal for quick debt payoff.
Balance transfer fees: Usually 3-5% of the transferred amount.
Higher APR after promotion: Rates can jump significantly if not paid off.
It’s crucial to be disciplined when using a balance transfer card. If you don’t pay off the balance within the promotional period, the remaining debt will accrue interest at a much higher rate, potentially negating any initial savings.
Qualifying for Debt Consolidation Loans in 2026
Securing a favorable debt consolidation loan in 2026 will largely depend on your financial profile. Lenders evaluate several key factors to determine your eligibility and the interest rate you’ll receive. Understanding these criteria can help you prepare and improve your chances of approval.
A strong credit score, a stable income, and a manageable debt-to-income ratio are typically what lenders look for. The better your financial standing, the more likely you are to qualify for a loan with a lower interest rate, which is essential for achieving significant savings.
Credit score requirements
Your credit score is one of the most critical factors. Generally, a good to excellent credit score (typically FICO score of 670 or higher) will qualify you for the most competitive interest rates. Lenders view higher scores as an indication of responsible financial behavior.
Excellent credit (740-850): Best rates, most options.
Good credit (670-739): Good rates, broad access to loans.
Fair credit (580-669): Higher rates, fewer options, but still possible.
If your credit score is lower, you might still qualify for a debt consolidation loan, but the interest rates will likely be higher. In such cases, it might be beneficial to work on improving your credit score before applying, or consider a secured loan if available.
Strategies to Reduce Interest Payments by 15% or More
Achieving a 15% or greater reduction in interest payments through debt consolidation is an ambitious yet attainable goal for many. This requires not only securing a favorable loan but also implementing smart financial strategies to maximize your savings and accelerate debt repayment.
The journey to significant interest reduction involves careful planning, comparison shopping for loans, and a commitment to responsible financial habits post-consolidation. It’s not just about getting a new loan; it’s about changing your approach to debt.
Comparison shopping for lenders
To find the best rates, you must compare offers from multiple lenders. Don’t settle for the first offer you receive. Online lenders, traditional banks, and credit unions all offer debt consolidation loans, and their rates and terms can vary significantly.
Many lenders offer pre-qualification processes that allow you to see potential rates without impacting your credit score. This is an invaluable tool for comparing options without commitment.
Improving your credit score before applying
Even a small improvement in your credit score can lead to a better interest rate. Before applying for a debt consolidation loan, consider steps like paying down small balances, disputing errors on your credit report, and making all payments on time. These actions can significantly impact the loan terms you’re offered.
Pay bills on time: Payment history is a major credit score factor.
Check credit report: Dispute any inaccuracies that could be dragging your score down.
By proactively managing your credit, you position yourself as a less risky borrower, which directly translates into lower interest rates and a higher likelihood of achieving your 15% interest reduction goal.
Potential Pitfalls and How to Avoid Them
While debt consolidation offers numerous benefits, it’s not a magic bullet. There are potential pitfalls that borrowers must be aware of and actively avoid to ensure the strategy is successful. A poorly executed consolidation plan can leave you in a worse financial position.
The most common dangers include accumulating new debt, failing to secure a significantly lower interest rate, and not fully understanding the terms and conditions of the new loan. Vigilance and financial discipline are paramount.
Accumulating new debt
One of the biggest risks of debt consolidation is falling back into old spending habits and accumulating new debt on the credit cards you just paid off. This can lead to an even heavier debt burden than before consolidation, as you’ll have the new consolidation loan plus the newly acquired credit card debt.
To avoid this, it’s crucial to close old credit card accounts or at least freeze them to prevent new charges. Developing a strict budget and sticking to it is also essential for preventing future debt accumulation.
Not achieving significant interest savings
If the interest rate on your new consolidation loan isn’t substantially lower than the average rate of your existing debts, the financial benefits might be minimal. It’s important to do the math and ensure that the new loan truly offers a meaningful reduction in interest costs.
Calculate average current APR: Understand your starting point.
Factor in fees: Account for origination fees or balance transfer fees.
Compare total cost: Look at the total interest paid over the loan term, not just the monthly payment.
Always read the fine print. Some loans may have hidden fees or variable rates that could increase over time, eroding your potential savings. Ensure you understand all terms before committing to a new loan.
Making Debt Consolidation Work for You in 2026
Successfully leveraging debt consolidation loans in 2026 requires more than just securing a loan; it demands a holistic approach to your personal finances. It’s an opportunity to reset your financial habits and build a more secure future. By adopting proactive strategies, you can maximize the benefits and achieve lasting financial relief.
This includes not only managing your new consolidated debt responsibly but also cultivating a deeper understanding of your spending patterns and developing a robust budget. The goal is to break the cycle of debt and establish a foundation for long-term financial health.
Developing a post-consolidation budget
Once your debts are consolidated, create and adhere to a new budget that incorporates your single, lower monthly payment. This budget should also allocate funds towards an emergency savings account and other financial goals. A clear budget prevents overspending and helps you stay on track.
Consider using budgeting apps or financial planners to help you monitor your spending and ensure you’re living within your means. This is a critical step in preventing future debt accumulation.
Seeking professional financial guidance
If you’re unsure about the best approach for your specific situation, consulting with a certified financial advisor or credit counselor can be highly beneficial. They can help you evaluate your options, understand the implications of different loan types, and develop a personalized debt management plan.
Personalized advice: Tailored strategies for your unique financial situation.
Objective assessment: Unbiased opinions on loan options.
Long-term planning: Assistance with broader financial goals beyond debt.
A financial professional can provide clarity and confidence, ensuring that your debt consolidation efforts are aligned with your overall financial objectives and lead to sustainable improvements in your financial well-being.
Key Aspect
Brief Description
Loan Purpose
Combines multiple high-interest debts into one lower-interest payment.
Interest Savings
Potential to reduce overall interest paid by 15% or more.
Key Factors
Credit score, income, debt-to-income ratio, and lender terms.
Risk Mitigation
Avoid new debt, compare offers diligently, and understand all fees.
Frequently Asked Questions About Debt Consolidation in 2026
What is a debt consolidation loan?▼
A debt consolidation loan is a personal loan that combines multiple existing debts, such as credit card balances or medical bills, into a single new loan with one monthly payment. The goal is often to secure a lower interest rate, simplify payments, and pay off debt more efficiently.
How can I reduce my interest payments by 15%?▼
To achieve a 15% or more reduction, you need to secure a consolidation loan with a significantly lower APR than the average of your current debts. Improving your credit score, comparing offers from various lenders, and negotiating terms can help you obtain a more favorable rate.
What are the eligibility requirements for these loans in 2026?▼
Lenders in 2026 typically look for a good credit score (670+ FICO), stable income, and a manageable debt-to-income ratio. Requirements can vary by lender, but a stronger financial profile generally leads to better loan terms and higher approval chances.
Are there risks associated with debt consolidation?▼
Yes, common risks include accumulating new debt after consolidation, not achieving substantial interest savings if the new loan’s APR isn’t much lower, and potential fees like origination or balance transfer charges. Financial discipline is key to avoiding these pitfalls.
Should I consult a financial advisor before consolidating?▼
Consulting a financial advisor or credit counselor is highly recommended, especially if you have complex financial situations or are unsure about the best option. They can provide personalized guidance, help evaluate loan offers, and develop a comprehensive debt management strategy for your needs.
Conclusion
Navigating the complexities of personal debt can be challenging, but debt consolidation loans in 2026 offer a promising avenue for Americans seeking financial relief. By carefully analyzing your options, understanding the economic landscape, and adopting sound financial practices, you can effectively reduce your interest payments, simplify your financial life, and take a significant step towards achieving long-term financial stability. Remember, the key to success lies in informed decision-making and unwavering commitment to your financial goals.