High-Yield Savings Accounts 2026: Top US Banks & 5%+ APY
Securing a high-yield savings account in 2026 with rates above 5.0% APY from top US banks is essential for optimizing your money’s growth and outpacing inflation.
Are you looking to make your money work harder for you? In today’s dynamic financial landscape, finding the right place for your savings is more critical than ever. This guide will explore high-yield savings accounts in 2026, focusing on comparing top US banks that offer impressive annual percentage yields (APYs) exceeding 5.0%.
Understanding high-yield savings accounts in 2026
As we navigate 2026, the financial market continues to evolve, making high-yield savings accounts a cornerstone for smart financial planning. These accounts offer significantly higher interest rates than traditional savings accounts, allowing your money to grow more rapidly over time. The key is to understand what drives these rates and how to identify the best opportunities.
High-yield savings accounts typically operate online, which helps banks reduce overhead costs. These savings are then passed on to consumers in the form of better interest rates. For consumers, this means convenient access to their funds through digital platforms, often with robust mobile banking apps and customer support.
What defines a high-yield account?
A high-yield account is characterized by an annual percentage yield (APY) that significantly surpasses the national average for savings accounts. In 2026, with inflation and economic shifts, an APY above 5.0% is considered exceptional, offering a substantial advantage to savers. These accounts are designed for individuals who want to preserve capital while earning a competitive return, without the volatility of investment markets.
- Competitive APY: Rates significantly above traditional savings accounts.
- Online accessibility: Often managed primarily through digital channels.
- Low fees: Many offer no monthly maintenance fees with certain conditions.
- FDIC insurance: Funds are typically insured up to $250,000 per depositor.
The distinction between traditional and high-yield accounts boils down to the rate of return and the operational model of the bank. Traditional banks, with their extensive branch networks and higher operating costs, usually offer lower rates. Online-only banks, on the other hand, can afford to offer higher APYs due to their lean operational structures. This makes them particularly attractive for savers looking to maximize their earnings.
In conclusion, high-yield savings accounts in 2026 represent a vital tool for personal finance. They provide a secure environment for your money while ensuring it grows at a competitive pace, far outperforming what standard savings options can deliver. Understanding their core features is the first step towards making an informed financial decision.
Factors influencing APY rates in 2026
The annual percentage yield (APY) offered by banks on high-yield savings accounts is not static; it’s influenced by a complex interplay of economic factors. In 2026, understanding these dynamics is crucial for anticipating rate changes and choosing the most beneficial accounts. The Federal Reserve’s monetary policy, inflation rates, and the competitive landscape among banks all play significant roles.
The Federal Reserve’s federal funds rate decisions are perhaps the most impactful. When the Fed raises its benchmark rate, banks typically follow suit by increasing their savings rates to attract deposits. Conversely, rate cuts can lead to lower APYs. Monitoring the Fed’s announcements and economic forecasts is a good strategy for savers.
Economic indicators and their impact
Inflation is another major factor. When inflation is high, banks may offer higher interest rates to ensure that the real return on savings remains attractive, encouraging people to save rather than spend. Conversely, in periods of low inflation, rates might drop. The overall health of the economy, including GDP growth and employment figures, also subtly influences banks’ decisions on APY.
- Federal funds rate: Directly impacts bank lending and deposit rates.
- Inflation rates: Banks adjust APY to maintain real returns for savers.
- Economic growth: Strong economies can lead to more competitive rates.
- Market competition: Banks strive to offer attractive rates to draw in customers.
Beyond these broad economic indicators, the competitive landscape among banks is a powerful driver. Online-only banks, which are often at the forefront of offering high APYs, constantly monitor each other’s rates. If one bank raises its APY, others may follow to avoid losing customers. This competition is a boon for consumers, as it pushes rates upward.
Furthermore, banks’ individual liquidity needs can influence their rates. If a bank needs to attract more deposits to fund its lending activities, it might offer a higher APY. This can create temporary opportunities for savers to lock in excellent rates. Therefore, staying informed about both macro-economic trends and specific bank strategies is essential for maximizing your savings.
In summary, APY rates in 2026 are a reflection of broader economic conditions and bank-specific strategies. By keeping an eye on the Federal Reserve, inflation, and market competition, savers can better position themselves to benefit from the highest possible returns on their high-yield savings accounts.
Top US banks offering 5.0%+ APY in 2026
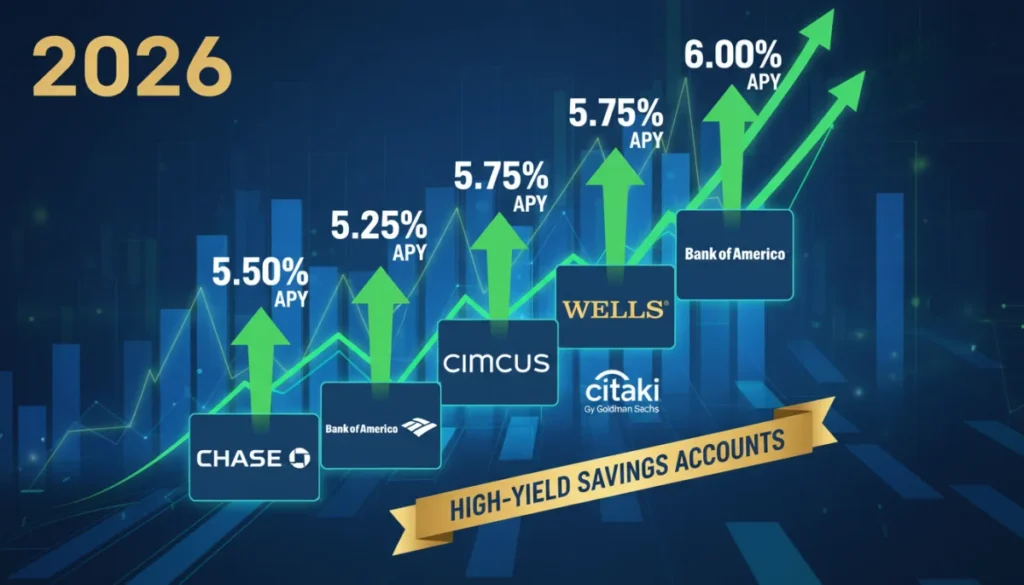
In 2026, several US banks distinguish themselves by offering high-yield savings accounts with APYs exceeding 5.0%. These institutions are often online-centric, leveraging lower operational costs to provide more attractive rates to their customers. Identifying these top performers requires careful research into their offerings, terms, and customer service.
While the exact list of banks and their rates can fluctuate, certain financial institutions consistently appear at the top of high-yield savings comparisons. These typically include challenger banks, online divisions of larger traditional banks, and credit unions that prioritize digital services. It’s important to remember that rates can change, so verifying current APYs directly with the bank is always recommended.
Key players and their offerings
Many of the leading banks in this space offer more than just high APYs. They often come with user-friendly digital platforms, mobile check deposit, fee-free ATM access through networks, and responsive customer support. Some may also integrate seamlessly with other financial products, providing a holistic banking experience.
- Bank A: Known for its consistent high APY and no monthly fees.
- Bank B: Offers competitive rates with a robust mobile banking app.
- Bank C: Provides excellent customer service and flexible deposit options.
- Bank D: Features a strong security infrastructure and easy account management.
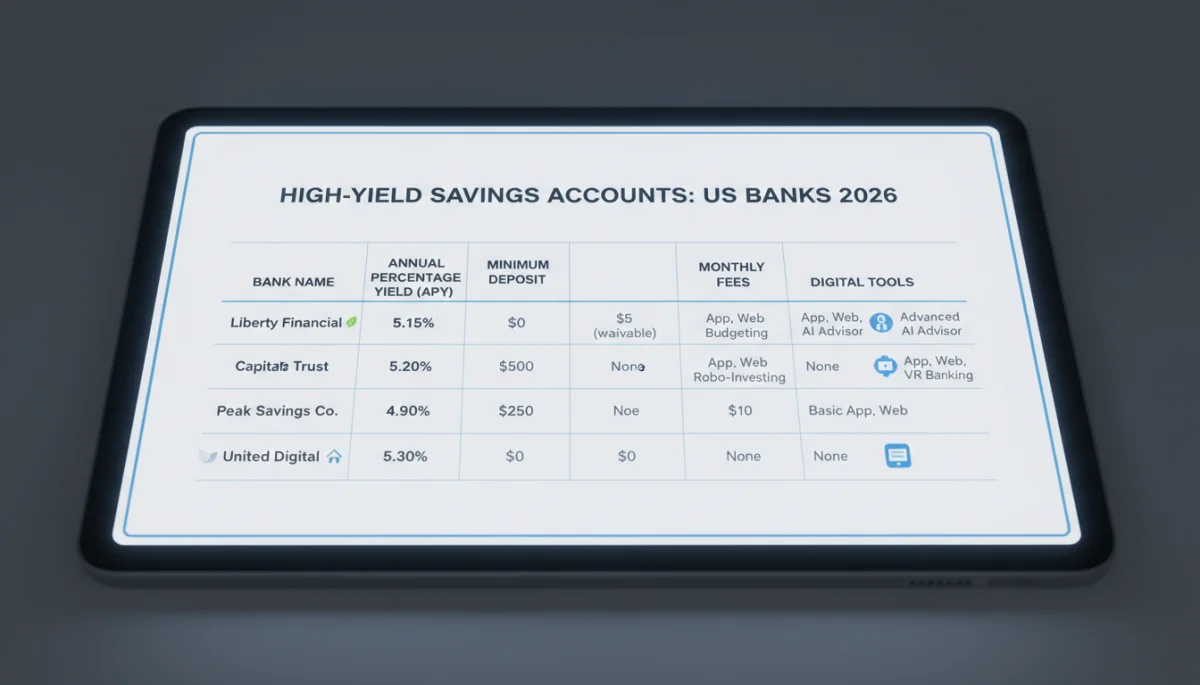
When comparing these banks, look beyond just the APY. Consider minimum balance requirements, any potential fees (even if conditional), ease of transferring funds, and the quality of their digital tools. A slightly lower APY might be acceptable if the bank offers superior convenience or features that align better with your financial habits.
For instance, some banks might require a direct deposit or a certain number of debit card transactions to unlock their highest APY tiers. Others might offer tiered rates, where higher balances earn better returns. It’s crucial to read the fine print to ensure you meet all criteria to qualify for the advertised rate.
Ultimately, the top US banks offering 5.0%+ APY in 2026 are those that combine compelling rates with reliable service and user-friendly platforms. By carefully evaluating these factors, savers can confidently choose an account that helps them achieve their financial goals.
Benefits of a high-yield savings account
Opting for a high-yield savings account in 2026 brings a multitude of benefits that extend beyond just earning more interest. These accounts are designed to optimize your financial well-being, offering a secure and efficient way to grow your money for various short-term and long-term goals. The advantages range from accelerated growth to enhanced financial flexibility.
The primary benefit, of course, is the significantly higher interest rate compared to traditional savings accounts. This means your money compounds faster, allowing you to reach your savings targets sooner. Whether you’re saving for a down payment, an emergency fund, or a major purchase, the power of compound interest at a high APY is undeniable.
Maximizing your savings growth
Beyond the raw interest, high-yield accounts often come with features that make managing your money easier and more effective. Many offer tools for budgeting, goal tracking, and automated transfers, helping you stay disciplined with your savings. The digital nature of these accounts also means 24/7 access to your funds and account information, providing unparalleled convenience.
- Faster growth: Higher APY leads to quicker accumulation of interest.
- Liquidity: Funds are readily accessible, unlike some investment vehicles.
- FDIC protection: Ensures your deposits are safe up to legal limits.
- Financial flexibility: Ideal for emergency funds and short-term goals.
Another significant advantage is the liquidity these accounts offer. Unlike certificates of deposit (CDs) or other investment vehicles that might lock up your funds for a specific period, high-yield savings accounts typically allow you to withdraw money without penalty, though some may have transaction limits. This makes them perfect for emergency funds, where quick access to cash is paramount.
Furthermore, the security provided by FDIC insurance (for banks) or NCUA insurance (for credit unions) up to $250,000 per depositor offers peace of mind. Your savings are protected even if the financial institution fails, making these accounts a very low-risk option for capital preservation. This combination of high returns and high security is what makes high-yield savings so attractive.
In conclusion, the benefits of a high-yield savings account in 2026 are clear: superior interest earnings, enhanced liquidity, robust security, and convenient digital management. These accounts are an indispensable tool for anyone serious about optimizing their savings and achieving financial freedom.
Choosing the right high-yield savings account
Selecting the ideal high-yield savings account in 2026 involves more than just picking the highest APY. It requires a comprehensive evaluation of various factors that align with your financial goals, habits, and preferences. A thoughtful approach ensures you choose an account that not only offers excellent returns but also fits seamlessly into your overall financial strategy.
Start by clearly defining your savings objectives. Are you building an emergency fund, saving for a down payment, or accumulating funds for a future expense? Your objective will influence how much liquidity you need and how long you plan to keep the money in the account, which can impact your choice of features.
Key considerations for selection
Beyond the APY, consider minimum balance requirements. Some accounts offer their highest rates only if you maintain a certain balance, while others might have no minimums at all. Fees are another critical aspect; look for accounts with no monthly maintenance fees or easily waivable fees. Hidden fees can quickly erode your interest earnings.
- APY (Annual Percentage Yield): Compare current rates carefully.
- Minimum balance: Check if there’s a requirement to earn the top APY.
- Fees: Look for accounts with no monthly maintenance or transaction fees.
- Accessibility: Evaluate ease of deposits, withdrawals, and transfers.
- Customer service: Assess the quality and availability of support channels.
- Digital tools: Consider mobile app features, online banking, and budgeting tools.
The accessibility of your funds is also paramount. How easy is it to deposit money into the account and withdraw it when needed? Look for options like mobile check deposit, electronic transfers, and ATM access. While high-yield accounts are generally liquid, some banks may have transfer limits or processing times that could impact your access.
Finally, don’t overlook customer service and digital tools. A bank with responsive support and an intuitive mobile app can significantly enhance your banking experience. Read reviews and consider what features are most important to you for managing your money effectively.
In conclusion, choosing the right high-yield savings account in 2026 means balancing a competitive APY with practical considerations like minimum balances, fees, accessibility, and customer support. By doing your homework, you can find an account that truly works for you.
Maximizing returns with high-yield strategies
Simply opening a high-yield savings account is a great start, but employing strategic approaches can further maximize your returns in 2026. These strategies involve more than just letting your money sit; they focus on active management, understanding market trends, and leveraging the features of your chosen account to their fullest potential. The goal is to consistently optimize your earnings.
One fundamental strategy is to automate your savings. Setting up recurring transfers from your checking account to your high-yield savings account ensures that you consistently contribute to your savings. This eliminates the temptation to spend the money and allows compound interest to work its magic more effectively over time.
Advanced tactics for higher APY
Stay informed about changes in interest rates. APYs are not fixed and can fluctuate with economic conditions. Regularly checking the rates offered by your bank and competitors can help you identify opportunities to switch to a higher-paying account if a better offer emerges. This proactive approach ensures your money is always earning the most it can.
- Automate savings: Set up regular, automatic transfers.
- Monitor rates: Periodically check for better APY offers from other banks.
- Tiered accounts: Utilize accounts with higher rates for larger balances.
- Avoid fees: Be mindful of minimum balance requirements to avoid charges.
- Leverage bonuses: Take advantage of sign-up bonuses for new accounts.
Consider tiered accounts if you have a substantial amount to save. Some high-yield accounts offer escalating APYs based on your balance, rewarding you with higher returns as your savings grow. While not all accounts have this feature, it’s worth exploring if your balance qualifies for a higher tier.
Also, be diligent about avoiding fees. Many high-yield accounts offer fee-free banking, but some might have conditions, such as maintaining a minimum balance or making a certain number of transactions. Missing these conditions can lead to fees that eat into your interest earnings. Always read the terms and conditions carefully.
Finally, explore sign-up bonuses. Some banks offer attractive cash bonuses for new customers who open a high-yield savings account and meet specific deposit or activity requirements. These bonuses can significantly boost your initial returns, but ensure you understand the terms and conditions to qualify.
In summary, maximizing your returns from high-yield savings accounts in 2026 involves a combination of automation, vigilance, and strategic decision-making. By actively managing your account and staying informed, you can ensure your savings grow at the fastest possible rate.
Future outlook for high-yield savings in 2026 and beyond
The financial landscape for high-yield savings accounts in 2026 and beyond is subject to various economic and technological shifts. While predicting the future with absolute certainty is impossible, we can anticipate certain trends that will likely shape the market, impacting both APY rates and the features offered by banks. Understanding these potential changes can help savers adapt their strategies.
One major trend is the continued rise of digital banking. As technology advances, more consumers are embracing online-only financial institutions, which will likely intensify competition among banks to offer even more attractive rates and innovative digital tools. This could lead to a more dynamic market where APYs adjust more frequently.
Anticipated market developments
Regulatory changes could also play a role. Governments and financial authorities continually review and update regulations affecting banking and consumer protection. Any new policies regarding interest rates, deposit insurance, or digital banking could influence how high-yield accounts operate and the benefits they offer. Staying informed about these developments is prudent.
- Increased digital adoption: More online-only banks and digital features.
- Technological innovations: AI-driven financial insights and personalized banking.
- Regulatory shifts: Potential changes impacting interest rates and consumer protection.
- Economic volatility: Continued influence of inflation and global events on APY.
Furthermore, the general economic climate, including inflation, interest rate policies from the Federal Reserve, and global economic stability, will remain a dominant factor. Periods of high inflation might see higher APYs to attract deposits, while stable or declining inflation could lead to a moderation of rates. Savers should remain flexible and ready to adjust their strategies based on these broader economic signals.
Another emerging area is the integration of artificial intelligence and personalized financial advice within banking platforms. Future high-yield accounts might offer more tailored recommendations for saving and spending, helping users optimize their financial health even further. This could transform the user experience and add significant value beyond just interest earnings.
In conclusion, the future of high-yield savings in 2026 and beyond appears to be one of continued evolution. With digital transformation, potential regulatory shifts, and ongoing economic influences, savers will need to remain agile and informed to consistently find the best accounts and maximize their financial growth.
| Key Point | Brief Description |
|---|---|
| APY Above 5.0% | Focus on accounts offering significantly higher interest rates than traditional savings. |
| Top US Banks | Primarily online banks and credit unions lead with competitive high-yield offers. |
| Economic Factors | APY rates are influenced by Federal Reserve policy, inflation, and market competition. |
| Strategic Maximization | Automate savings, monitor rates, and avoid fees to optimize your returns consistently. |
Frequently asked questions about high-yield savings in 2026
A high-yield savings account offers significantly higher interest rates than traditional savings accounts. In 2026, it’s crucial for counteracting inflation and maximizing your money’s growth, especially with competitive APYs exceeding 5.0% available from various US banks. These accounts help your savings keep pace with economic changes.
Yes, accounts offered by FDIC-insured banks are safe, with deposits protected up to $250,000 per depositor. Similarly, credit union accounts are insured by the NCUA. This federal insurance provides peace of mind, ensuring your principal and earned interest are secure even if the institution faces financial difficulties.
To find banks offering over 5.0% APY in 2026, focus on online-only banks and challenger banks, as they typically have lower overheads allowing for better rates. Regularly check financial comparison websites and the official sites of reputable online institutions, as rates can fluctuate based on market conditions and Federal Reserve policies.
Beyond APY, consider minimum balance requirements to earn the advertised rate, any potential fees (monthly, transaction, etc.), ease of access to your funds (transfers, ATM access), and the quality of the bank’s digital tools and customer service. These factors ensure the account meets your practical banking needs.
Yes, APY rates on high-yield savings accounts are variable and can change at any time. Banks adjust rates based on economic factors like the Federal Reserve’s actions, inflation, and market competition. It’s advisable to monitor your account’s rate and be prepared to switch banks if significantly better offers become available elsewhere.
Conclusion
In conclusion, navigating the world of high-yield savings accounts in 2026 offers significant opportunities for savvy savers to grow their wealth. By understanding the economic factors influencing APY rates, carefully comparing top US banks offering rates above 5.0%, and employing strategic savings practices, individuals can make informed decisions that align with their financial goals. The shift towards digital banking continues to empower consumers with competitive options, making it an opportune time to maximize your savings and secure your financial future.