Authorized User Strategy 2026: Boost Family Credit by 20 Points
Implementing an authorized user strategy in 2026 can significantly boost your family’s credit scores, potentially increasing them by 20 points or more, by leveraging established credit accounts responsibly.
Are you looking for a proven method to significantly improve your family’s financial standing? The authorized user strategy 2026 offers a powerful pathway to boost credit scores, potentially by 20 points or more, without taking on new debt. This approach leverages existing, well-managed credit accounts to extend their positive history to others, providing a tangible uplift in creditworthiness.
Understanding the authorized user strategy in 2026
The authorized user strategy involves adding someone to an existing credit card account as an authorized user. This means they can make purchases with the card, though they are not legally responsible for the debt. Crucially, the payment history of that credit card account can then appear on the authorized user’s credit report, potentially improving their score if the primary account holder has a strong credit history.
In 2026, this strategy remains a potent tool for credit building, particularly for young adults, spouses, or others needing a credit boost. The impact can be substantial, often leading to increases of 20 points or more, depending on the individual’s current credit profile and the primary account’s health.
How authorized user status impacts credit scores
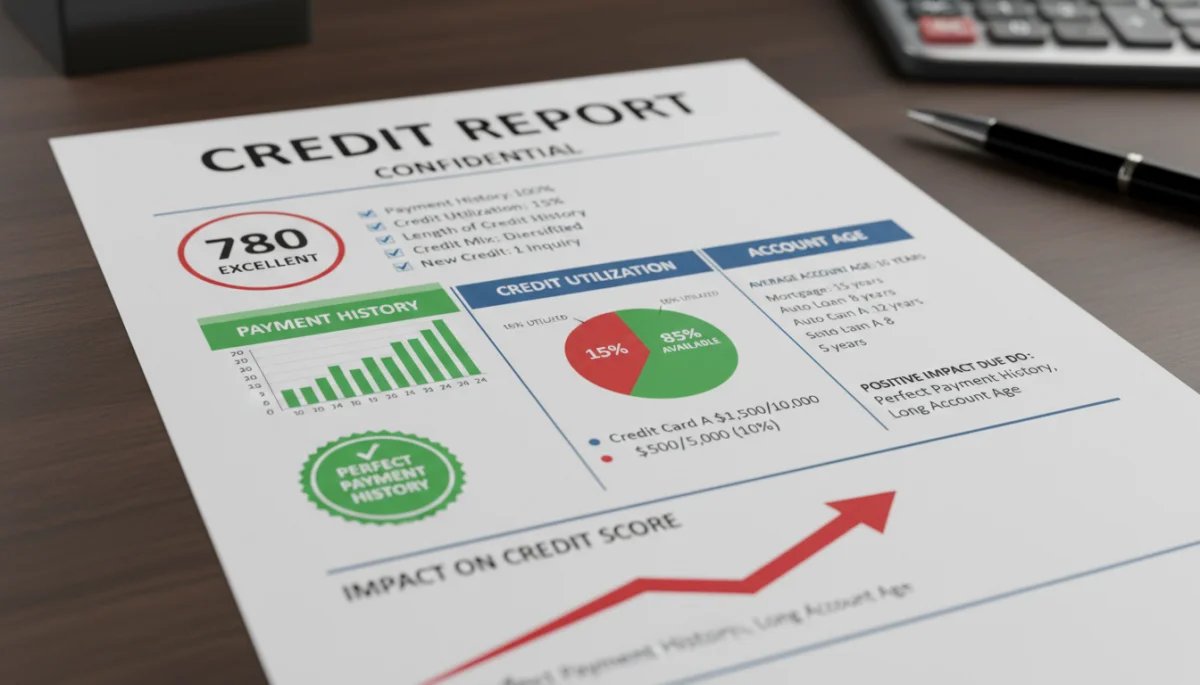
When you become an authorized user, the credit bureaus typically begin reporting the account’s history on your credit file. This includes factors like:
- Payment history: On-time payments by the primary cardholder reflect positively on the authorized user.
- Credit utilization: A low utilization ratio on the shared account can benefit the authorized user’s score.
- Length of credit history: Older accounts contribute to a longer average credit age for the authorized user.
These elements are fundamental to credit scoring models like FICO and VantageScore. By carefully selecting which accounts to join, authorized users can quickly establish a positive credit footprint, or strengthen an existing one. The key is to ensure the primary account is managed responsibly, with consistent on-time payments and low balances.
The authorized user strategy is not a quick fix for severe credit issues, but for those with limited or fair credit, it can provide a significant, measurable boost. It’s a strategic move that, when executed correctly, lays a strong foundation for future financial endeavors.
Selecting the right primary account holder
Choosing the right primary account holder is perhaps the most critical step in a successful authorized user strategy. This decision directly impacts the potential credit score boost and mitigates risks. An ideal primary account holder should possess a long, impeccable credit history.
Look for someone who consistently makes payments on time, maintains low credit utilization, and has held the account for several years. This combination ensures that the positive attributes of the account are maximized when reported to credit bureaus.
Key factors to consider in a primary account
Several aspects of the primary account itself are vital for maximizing the benefit to an authorized user:
- Length of credit history: Older accounts provide a deeper history of responsible financial behavior.
- Payment history: A flawless record of on-time payments is non-negotiable.
- Credit limit and utilization: Accounts with high credit limits and low balances (ideally under 10% utilization) are most beneficial.
- Card issuer policies: Some card issuers report authorized user activity differently, or not at all. Verify this beforehand.
It’s also important to have an open and honest conversation with the primary account holder about their spending habits and commitment to maintaining good credit. Transparency ensures both parties understand the implications and responsibilities. This collaborative approach fosters trust and increases the likelihood of a positive outcome for the authorized user’s credit score.
The goal is to leverage an account that reflects financial discipline and stability. A well-chosen primary account can provide the authorized user with a significant head start in building a robust credit profile, potentially adding those crucial 20 points or more to their score.
Potential benefits and risks for family members
The authorized user strategy in 2026 presents a unique opportunity for families to support each other’s financial health. The benefits, particularly for younger family members or those rebuilding credit, can be transformative. However, it’s equally important to acknowledge and manage the inherent risks.
For the authorized user, the primary benefit is a rapid improvement in credit score, often without the need to take on new debt or meet strict eligibility criteria. This can open doors to better loan rates, easier apartment rentals, and improved insurance premiums. For the primary account holder, it’s an act of generosity that can significantly help a loved one.
Mitigating risks associated with authorized users
While the primary account holder is ultimately responsible for the debt, certain risks must be addressed:
- Overspending by authorized user: Although not legally liable, an authorized user’s spending can increase the primary account holder’s balance, impacting their credit utilization.
- Damage to primary’s credit: If the primary account holder’s payments become erratic, or utilization spikes due to authorized user spending, both credit scores could suffer.
- Lack of financial education: Without proper understanding, an authorized user might not grasp the gravity of credit management, even if not directly liable.
To mitigate these risks, clear communication and established boundaries are essential. Consider setting spending limits for authorized users or even opting not to provide them with a physical card. Regular check-ins on account activity and credit reports are also advisable. This proactive approach helps ensure the strategy benefits everyone involved without creating unforeseen financial strain or damaged relationships.
Ultimately, the authorized user strategy is a powerful tool for mutual financial uplift within a family, but it demands careful planning, open dialogue, and ongoing vigilance to maximize benefits and minimize potential pitfalls.
Legal and practical considerations in 2026
Navigating the legal and practical landscape of the authorized user strategy in 2026 requires attention to detail and an understanding of current regulations. While the core mechanics remain similar, changes in reporting practices or card issuer policies can influence the effectiveness of this approach. It’s crucial to stay informed about these nuances to ensure the strategy yields the desired credit score boost.
One key aspect is verifying that the credit card issuer reports authorized user activity to all three major credit bureaus: Experian, Equifax, and TransUnion. Not all issuers do this uniformly, and missing reports can limit the impact on the authorized user’s credit file. A quick call to the card company can clarify their policy.
Understanding credit reporting and removal
The way authorized user accounts are reported can vary. Some bureaus may report the entire account history, while others might only report from the date the authorized user was added. This distinction can affect the length of credit history reflected on the authorized user’s report.
Furthermore, understanding how to remove an authorized user is also a practical consideration. Should circumstances change, or if the primary account holder wishes to terminate the arrangement, the process is usually straightforward:
- Contact the issuer: The primary account holder can typically call the credit card company to request removal.
- Credit report update: Once removed, the account may eventually cease to appear on the authorized user’s credit report, or its status will be updated.
- No legal liability: Even after removal, the authorized user was never legally responsible for the debt.
These practical steps ensure that the authorized user strategy is not only beneficial but also flexible and manageable. Being aware of these details allows families to implement the strategy with confidence, knowing they can adapt if needed while aiming for that significant credit score increase.
Maximizing the 20-point credit score boost
Achieving a 20-point or greater boost to a family member’s credit score through the authorized user strategy requires more than just adding them to an account. It demands a strategic approach focused on optimizing the factors that credit bureaus prioritize. By understanding these levers, you can maximize the positive impact and ensure the strategy delivers its full potential.
The primary account’s health is paramount. This means the primary cardholder must continue to exhibit exemplary credit behavior. Consistent on-time payments are foundational. A single late payment on the shared account can negate many months of positive reporting, potentially harming both the primary and authorized user’s scores.
Strategic account management for optimal results
To truly maximize the credit boost, consider these additional strategies:
- Keep utilization low: Ensure the primary account’s credit utilization remains well below 30%, ideally under 10%. This signals responsible credit management.
- Choose aged accounts: Opt for accounts that have been open for many years, as a longer credit history positively impacts average account age.
- Monitor credit reports: Both primary and authorized users should regularly check their credit reports to ensure the account is being reported correctly and to catch any discrepancies.
Furthermore, if the authorized user has other credit accounts, encouraging them to manage those responsibly will amplify the effect. The authorized user strategy is a powerful component, but it works best when integrated into an overall sound financial management plan. By focusing on these elements, families can effectively leverage the authorized user strategy to achieve significant and lasting credit score improvements, reaching or exceeding that 20-point goal.
Long-term financial planning with authorized users
Beyond the immediate credit score boost, the authorized user strategy in 2026 serves as an excellent foundation for long-term financial planning within a family. It’s an opportunity to educate younger generations about responsible credit use and to foster a culture of financial literacy. This strategy can be a stepping stone towards greater financial independence and stability for authorized users.
Once an authorized user establishes a solid credit score, they can then pursue their own credit products, such as their first credit card or a car loan, often with more favorable terms. This gradual transition from relying on a parent’s or guardian’s credit to building their own is a crucial part of financial maturity.
Transitioning to independent credit management
The goal is not for individuals to remain authorized users indefinitely, but rather to use the experience as a launchpad. Here’s how to facilitate that transition:
- Encourage their own credit card: Once credit is established, guide them to apply for a starter credit card in their own name, emphasizing responsible use.
- Teach budgeting skills: Connect credit management to overall budgeting, showing how debt fits into a larger financial picture.
- Discuss credit report details: Explain how different factors on a credit report impact their score, empowering them with knowledge.
This holistic approach ensures that the credit score gains from the authorized user strategy are not just temporary, but lead to sustainable financial habits. It’s about empowering family members to make informed decisions, understand the power of credit, and ultimately achieve their financial goals. By integrating this strategy into a broader financial education framework, families can build a legacy of strong credit and financial well-being for years to come.
| Key Aspect | Brief Description |
|---|---|
| Credit Boost Potential | Can boost scores by 20+ points by leveraging positive payment history. |
| Primary Account Selection | Choose accounts with long history, low utilization, and perfect payments. |
| Risk Management | Communicate clearly, set spending limits, and monitor account activity. |
| Long-Term Impact | Fosters financial literacy and aids transition to independent credit. |
Frequently asked questions about authorized users
Typically, a credit score increase can be seen within 30 to 60 days after the authorized user account is reported to the credit bureaus. The exact timing depends on the primary account’s reporting cycle and the individual’s current credit profile. Significant boosts often appear quickly.
No, as an authorized user, you are not legally responsible for the debt on the account. Only the primary account holder is legally obligated to make payments. This is a key advantage, as it allows credit building without incurring direct financial liability.
Yes, if the primary account holder misses payments or maintains high credit utilization, this negative activity will also be reported to your credit file, potentially lowering your score. It’s crucial to choose a primary account holder with excellent credit habits.
Some credit card issuers do not report authorized user activity to all credit bureaus. If this is the case, the strategy won’t be effective for building credit. Always verify the issuer’s policy before adding an authorized user to ensure the desired credit boost.
While there isn’t a federal minimum age, most credit card companies require authorized users to be at least 13 or 16 years old. Some may not have a specific age requirement at all, allowing even younger individuals to be added for credit building purposes.
Conclusion
The authorized user strategy in 2026 remains a highly effective and accessible method for boosting family credit scores. By carefully selecting the primary account, maintaining open communication, and understanding the nuances of credit reporting, families can leverage this approach to achieve significant financial improvements, potentially increasing scores by 20 points or more. This strategy not only provides an immediate credit uplift but also serves as a valuable tool for long-term financial education and independence, setting family members on a path toward greater financial stability and success.