Navigating Bank Overdraft Fees: Avoid Up to $35 Charges in 2026
Understanding and actively avoiding bank overdraft fees is crucial for financial well-being, as these charges can accumulate quickly, potentially costing consumers up to $35 per incident by 2026.
By: Rafaela on September 23, 2026
Understanding and actively avoiding bank overdraft fees is crucial for financial well-being, as these charges can accumulate quickly, potentially costing consumers up to $35 per incident by 2026.
Are you tired of unexpected charges eating into your hard-earned money? By 2026, bank overdraft fees could climb as high as $35 per incident, making it more critical than ever to master the art of navigating bank overdraft fees: strategies to avoid up to $35 charges in 2026. This guide will equip you with the knowledge and tools to protect your finances.
Understanding the Mechanics of Overdraft Fees
Overdraft fees occur when you spend more money than you have available in your checking account. While seemingly straightforward, the mechanics behind these charges can be complex, often leading to frustration and unexpected financial strain. Banks typically cover the transaction, but then levy a fee for doing so, essentially acting as a short-term, high-cost loan.
The rules and regulations surrounding overdrafts have evolved over time, with various reforms aimed at protecting consumers. However, banks still retain significant discretion in how they implement these policies, leading to a wide range of practices across institutions. Understanding your bank’s specific policies is the first step toward effective prevention.
What Triggers an Overdraft?
Several common scenarios can lead to an overdraft. Knowing these triggers can help you be more vigilant with your spending and account management.
Debit Card Transactions: Swiping your card for a purchase that exceeds your available balance.
ATM Withdrawals: Taking out more cash than you have in your account.
Checks and ACH Payments: When a check you’ve written or an automated bill payment clears for an amount greater than your current balance.
Recurring Payments: Subscriptions or memberships that automatically debit your account when funds are insufficient.
The Cost of Convenience: Why Overdraft Fees Persist
Despite public outcry and regulatory scrutiny, overdraft fees remain a significant revenue stream for banks. They argue that offering overdraft protection is a service, providing a safety net for customers who might otherwise face bounced checks or declined transactions. However, for many consumers, these fees feel predatory, especially when a small overdraft leads to a disproportionately high charge. The average fee, projected to reach up to $35 by 2026, highlights the steep price of not managing your account carefully.
Ultimately, understanding how and why overdrafts occur, and the substantial financial impact they can have, is foundational to developing robust strategies for avoidance. It’s not just about knowing your balance, but also understanding the intricate dance between your spending habits and your bank’s operational policies.
Proactive Account Management: Your First Line of Defense
Effective proactive account management is the cornerstone of avoiding overdraft fees. This involves regularly monitoring your balance, understanding your spending patterns, and utilizing the tools your bank provides to stay informed. It’s about being one step ahead of potential financial pitfalls.
Many people fall into the overdraft trap due to a lack of awareness about their real-time balance. The delay between a transaction and its appearance in your online banking statement can create a false sense of security. Always consider pending transactions and scheduled payments when assessing your available funds.
Leveraging Technology for Balance Tracking
Modern banking offers a plethora of technological solutions designed to help you keep tabs on your money. Embrace these tools to gain greater control over your finances.
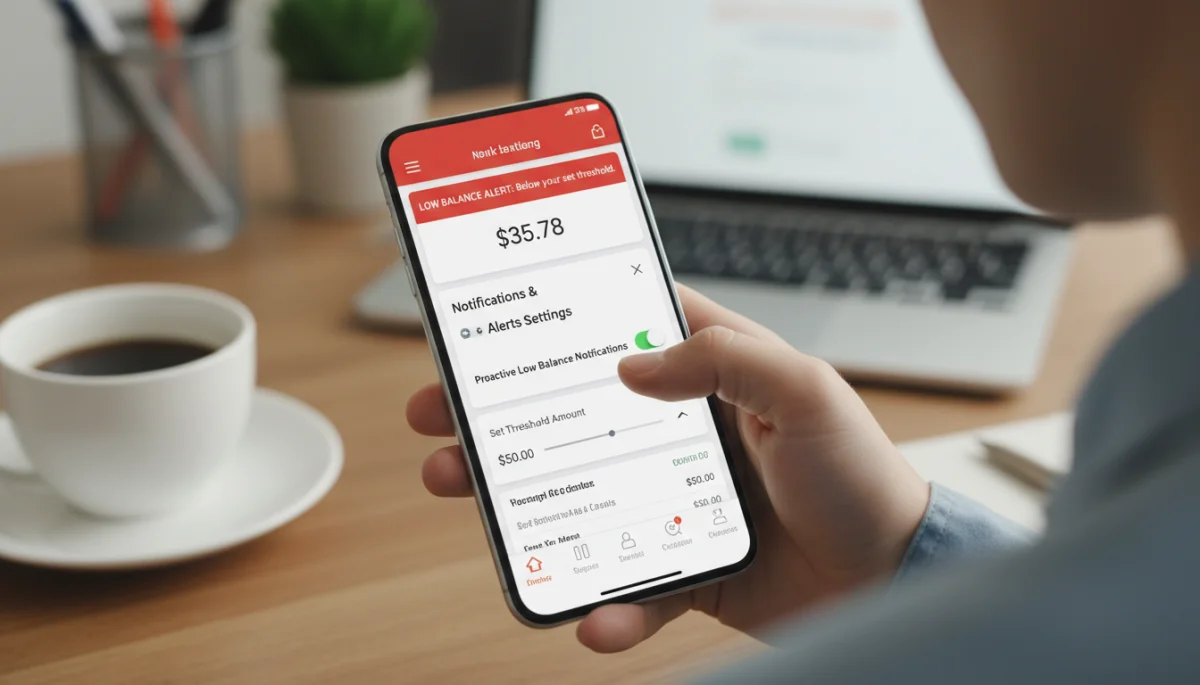
Mobile Banking Apps: Most banks offer robust mobile apps that provide instant access to your account balance, transaction history, and pending activities. Check it frequently.
Low Balance Alerts: Set up notifications via email or text message that warn you when your account balance drops below a predetermined threshold. This is a critical early warning system.
Transaction Alerts: Receive alerts for every transaction, allowing you to catch unauthorized activity or monitor your spending in real-time.
Budgeting and Spending Habits
Beyond technology, cultivating healthy budgeting and spending habits is paramount. A well-structured budget helps you allocate your funds wisely and prevents overspending.
Consider the ‘envelope system’ for categories where you tend to overspend, such as dining out or entertainment. Physically setting aside cash or mentally assigning limits can be highly effective. Review your monthly statements to identify spending patterns and areas where you can cut back or adjust your budget. This continuous feedback loop reinforces good financial behavior and drastically reduces the likelihood of an overdraft.
Strategic Banking Services to Prevent Overdrafts
Beyond personal vigilance, many banks offer services specifically designed to help customers avoid overdraft fees. These services can act as invaluable safeguards, providing an extra layer of protection when your balance runs low. It’s crucial to understand these options and select the ones that best fit your financial situation.
Not all banking services are created equal, and some may come with their own set of conditions or fees. Always read the fine print and discuss these options with a bank representative to ensure you fully comprehend their implications.
Opt-in for Overdraft Protection
Overdraft protection is a service that links your checking account to another account, such as a savings account, a credit card, or a line of credit. When your checking account runs low, funds are automatically transferred from the linked account to cover the transaction.
Savings Account Linkage: This is often the most cost-effective option, as transfers from your own savings account typically incur minimal or no fees. It essentially uses your own money to prevent an overdraft.
Credit Card/Line of Credit Linkage: While this prevents an overdraft fee, be aware that you will be charged interest on the amount borrowed from your credit card or line of credit. This option should be used cautiously.
Decline Overdraft Coverage for Debit Card and ATM Transactions
Under federal law, banks must ask you to opt-in for overdraft coverage for debit card and ATM transactions. If you do not opt-in, your transaction will simply be declined if you don’t have sufficient funds, rather than being approved and incurring a fee. This is a powerful tool for preventing accidental overdrafts.
While a declined transaction might be inconvenient, it’s far less costly than a $35 overdraft fee. This choice forces you to live within your means in real-time, acting as an immediate spending governor. Consider whether the convenience of an approved transaction is worth the potential fee.
Building a Financial Buffer: Emergency Funds and Savings
One of the most effective long-term strategies for avoiding overdraft fees, and indeed for overall financial stability, is to build a robust financial buffer. This buffer, typically in the form of an emergency fund or dedicated savings, acts as a safety net, ensuring you always have access to funds when unexpected expenses arise or your checking account runs lower than anticipated.
Many financial experts recommend having at least three to six months’ worth of living expenses saved in an easily accessible account. While this might seem like a daunting goal, even building a small buffer specifically for your checking account can make a significant difference in preventing overdrafts.
The Importance of an Emergency Fund
An emergency fund is designed to cover unforeseen costs, such as medical emergencies, car repairs, or sudden job loss. However, it can also serve as an excellent defense against overdrafts. If you accidentally overspend in your checking account, having a readily available emergency fund allows you to quickly transfer funds to cover the deficit without incurring a fee.
Start small if you need to. Even saving an extra $100-$200 specifically for this purpose can provide a crucial cushion against minor miscalculations in your checking account balance. Automate transfers from your checking account to your savings account each payday to make building this fund effortless.
Dedicated Savings for Known Expenses
Beyond a general emergency fund, consider creating dedicated savings for known, but infrequent, expenses. This could include annual insurance premiums, property taxes, or large purchases you anticipate making. By setting aside money for these items in advance, you prevent them from unexpectedly depleting your checking account and potentially causing an overdraft.
Using separate savings accounts for different goals can help you visualize your progress and prevent you from dipping into funds earmarked for specific purposes. This disciplined approach to saving not only prevents overdrafts but also contributes to greater overall financial security.
Negotiating and Appealing Overdraft Fees
Even with the best preventative measures, sometimes an overdraft fee can still occur. When it does, don’t despair; you may have options to get the fee waived or reduced. Many banks, particularly for long-standing customers or those with a good banking history, are willing to work with you.
The key to a successful negotiation or appeal is to act quickly, be polite, and clearly articulate your situation. Remember, banks want to retain good customers, and they often have some flexibility in their fee policies.
Steps to Appeal an Overdraft Fee
Follow these steps to maximize your chances of a successful appeal:
Contact Your Bank Immediately: As soon as you notice the fee, call your bank’s customer service or visit a branch. The sooner you address it, the better.
Be Polite and Explain Your Situation: Calmly explain what happened. If it was a genuine mistake, or if you’ve never had an overdraft before, highlight these points.
Request a Waiver: Directly ask if they can waive the fee as a one-time courtesy. Many banks offer one or two fee waivers per year for good customers.
Reference Your Banking Relationship: If you’ve been a loyal customer for years, mention it. Your history with the bank can be a powerful negotiating tool.
Understanding Bank Flexibility and Policies
While there’s no guarantee, many banks have internal policies that allow representatives to waive fees under certain circumstances. Some might offer to reverse the fee if you immediately deposit funds to cover the overdraft. Others might be more lenient if you set up overdraft protection on the spot.
If your initial attempt is unsuccessful, politely ask to speak with a supervisor. Sometimes, a higher-level representative has more authority to make exceptions. Remember, persistence, coupled with a respectful demeanor, can often yield positive results. Even if you can’t get the fee completely waived, you might be able to negotiate a reduction.
Long-Term Strategies for Financial Health and Fee Avoidance
Beyond immediate prevention and negotiation, adopting long-term strategies for overall financial health is the most robust defense against overdraft fees and other banking charges. This holistic approach ensures that your financial foundation is strong, making you less susceptible to the unexpected.
A financially healthy individual is one who understands their money, makes informed decisions, and continuously seeks to improve their financial literacy. This journey is ongoing and requires consistent effort, but the rewards are substantial.
Regular Financial Reviews
Make it a habit to conduct regular financial reviews. This means more than just checking your bank balance; it involves analyzing your income, expenses, savings, and investments. Use these reviews to:
Identify Spending Trends: Notice where your money is going and if there are any patterns that could lead to overdrafts.
Adjust Your Budget: Life changes, and so should your budget. Regularly update it to reflect your current financial situation and goals.
Monitor Account Activity: Look for any unusual transactions or fees that might indicate a problem.
Consider Alternative Banking Options
If your current bank frequently charges you overdraft fees despite your best efforts, it might be time to explore alternative banking options. Some financial institutions, especially online-only banks or credit unions, have significantly lower fees or even no overdraft fees at all.
Research banks that offer ‘second-chance checking accounts’ if you have a history of overdrafts, or those that focus on fee-free banking. Switching banks can be a hassle, but the long-term savings and peace of mind can be well worth the effort. By taking control of your financial habits and making informed banking choices, you can effectively navigate the landscape of bank overdraft fees and secure your financial future.
Key Strategy
Brief Description
Proactive Monitoring
Regularly check balances, set up alerts, and track transactions via mobile banking apps.
Overdraft Protection
Link accounts (e.g., savings, credit card) for automatic transfers to cover shortfalls.
Build Financial Buffer
Establish an emergency fund to cover unexpected expenses and small account deficits.
Negotiate Fees
Contact your bank immediately to request a waiver or reduction for accidental overdrafts.
Frequently Asked Questions About Overdraft Fees
What exactly is an overdraft fee?▼
An overdraft fee is a charge levied by your bank when you make a transaction that exceeds the available funds in your checking account. Instead of declining the transaction, the bank covers it, then charges you a fee for this service, which can be up to $35 by 2026.
How can I set up low balance alerts?▼
Most banks allow you to set up low balance alerts through their online banking portal or mobile app. You can typically choose the threshold at which you want to be notified and receive alerts via email or text message, helping you avoid accidental overspending.
Is overdraft protection always a good idea?▼
Overdraft protection can be beneficial, especially if linked to a savings account, as it prevents fees. However, if linked to a credit card or line of credit, you might incur interest charges, making it a more costly option. Evaluate the terms carefully before opting in.
Can I get an overdraft fee waived?▼
Yes, it’s often possible to get an overdraft fee waived, especially if it’s your first time or you have a good banking relationship. Contact your bank’s customer service immediately, politely explain the situation, and request a one-time courtesy waiver.
What are alternatives to traditional bank accounts to avoid fees?▼
Consider online-only banks or credit unions, as many offer accounts with no overdraft fees or significantly lower charges. Some financial technology companies also provide fee-free checking alternatives that can help you manage your money without unexpected costs.
Conclusion
Navigating bank overdraft fees: strategies to avoid up to $35 charges in 2026 is not just about saving money; it’s about gaining control over your financial destiny. By implementing proactive account management, leveraging strategic banking services, building a robust financial buffer, and knowing how to negotiate, you can effectively shield yourself from these costly charges. The financial landscape is constantly evolving, and staying informed and proactive is your best defense against unexpected fees. Take charge of your banking habits today to ensure a more secure and prosperous financial future.