As 2026 approaches, understanding and preparing for potential interest rate hikes is crucial for US homeowners; proactive strategies can safeguard your mortgage payments and financial well-being.
By: Rafaela on September 23, 2026
Proactive financial planning and exploring options like refinancing or payment adjustments are essential for US homeowners to effectively manage mortgage payments amidst anticipated 2026 interest rate increases.
The prospect of rising interest rates can be daunting, especially for homeowners. With 2026 on the horizon, many in the United States are wondering how potential rate hikes will impact their mortgage payments. Understanding these shifts and preparing for them now is not just smart, it’s essential for financial stability. This article will explore key strategies for navigating the 2026 interest rate hikes: 5 practical solutions for your mortgage payments in the US, offering actionable advice to help you stay ahead.
Understanding the Economic Landscape Leading to 2026
Before diving into solutions, it’s crucial to grasp why interest rates might increase. Economic indicators, inflation trends, and Federal Reserve policies all play significant roles in shaping the future of mortgage rates. By 2026, experts anticipate various economic pressures could lead to further adjustments in borrowing costs, directly affecting homeowners.
The Federal Reserve’s primary mandate includes maintaining price stability and maximizing employment. When inflation runs high, as it has in recent years, the Fed often resorts to raising the federal funds rate, which in turn influences other interest rates, including those for mortgages. This mechanism is a key factor in projecting future rate environments.
Inflationary Pressures and Fed Response
Inflation erodes purchasing power and can destabilize an economy. The Fed’s response typically involves tightening monetary policy. This tightening often manifests as:
Rate Hikes: Direct increases in the federal funds rate.
Quantitative Tightening: Reducing the Fed’s balance sheet by selling off assets, which pulls liquidity from the market.
Forward Guidance: Communicating future policy intentions to guide market expectations.
These actions are designed to cool down an overheating economy, but they inevitably impact borrowing costs for consumers and businesses alike. For homeowners, this means variable-rate mortgages could see higher monthly payments, and those looking to refinance might face less favorable terms.
Staying informed about these broader economic trends is the first step in preparing for 2026. Monitoring economic news and Federal Reserve announcements can provide valuable insights into potential rate movements, allowing you to react proactively rather than reactively.
Solution 1: Refinancing Your Mortgage to a Fixed Rate
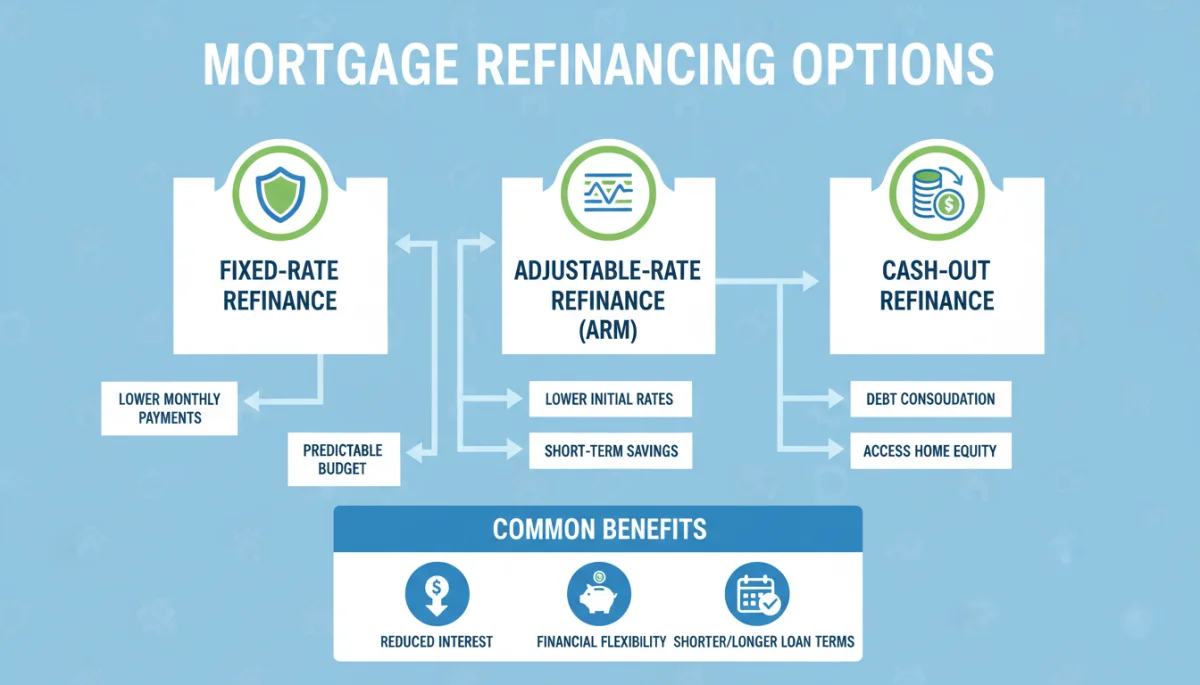
One of the most effective strategies for homeowners with adjustable-rate mortgages (ARMs) or those with higher fixed rates is to consider refinancing. A fixed-rate mortgage locks in your interest rate for the life of the loan, providing predictability and shielding you from future rate hikes. This stability can be invaluable, especially as 2026 approaches.
Refinancing involves taking out a new loan to pay off your existing mortgage. The primary goal for many is to secure a lower interest rate, reduce monthly payments, or switch from an ARM to a fixed-rate loan. Evaluating your current mortgage terms against prevailing rates is a critical first step.
Types of Refinancing Options
When considering refinancing, several options are available, each with its own advantages:
Rate-and-Term Refinance: This type of refinance aims to reduce your interest rate and/or change the loan term (e.g., from a 30-year to a 15-year mortgage). It doesn’t involve cashing out equity.
Cash-Out Refinance: With a cash-out refinance, you take out a new mortgage for more than you owe on your current home, converting a portion of your home equity into cash. While useful for home improvements or debt consolidation, it increases your loan amount.
FHA Streamline Refinance: For those with existing FHA loans, this option offers a simplified process with less paperwork, often without an appraisal.
It’s important to weigh the closing costs associated with refinancing against the potential long-term savings. Sometimes, even a small reduction in interest rate can lead to significant savings over the life of the loan, making the upfront costs worthwhile. Consulting with a mortgage professional can help you determine the best path forward based on your financial situation and market conditions.
Securing a fixed rate now can provide peace of mind and financial certainty against the backdrop of potential interest rate volatility in 2026. Don’t wait until rates have already climbed; explore your refinancing options proactively.
Solution 2: Making Additional Principal Payments
Another powerful strategy to mitigate the impact of rising interest rates is to make extra payments towards your mortgage principal. Even small, consistent additional payments can significantly reduce the total interest paid over the life of the loan and shorten your mortgage term. This strategy builds equity faster and lessens your overall financial burden.
When you make an extra principal payment, that money directly reduces the amount on which interest is calculated. This means you’ll pay less interest over time, which can be particularly beneficial if interest rates are expected to rise. Every dollar you put towards principal today saves you more in future interest.
Benefits of Accelerating Principal Payments
The advantages of paying down your mortgage faster extend beyond just saving on interest:
Reduced Loan Term: You pay off your mortgage sooner, freeing up cash flow in the long run.
Increased Equity: Building equity faster provides a financial cushion and more options for future financial planning.
Lower Total Interest Paid: This is the most direct financial benefit, saving you potentially thousands of dollars.
Consider setting up bi-weekly payments instead of monthly. This effectively adds one extra mortgage payment per year without feeling like a massive burden. For example, if your monthly payment is $1,500, paying $750 every two weeks results in 26 half-payments, totaling $19,500 annually, compared to $18,000 with 12 monthly payments. This small adjustment can shave years off your mortgage.
Review your budget to identify areas where you can cut back or reallocate funds to make these additional payments. Even an extra $50 or $100 per month can make a difference. This proactive approach can significantly strengthen your financial position ahead of any rate increases.
Solution 3: Exploring Loan Modification Programs
For homeowners facing financial hardship or anticipating difficulty with future mortgage payments due to rising rates, exploring loan modification programs can be a viable solution. These programs, often offered by lenders or government agencies, aim to change the terms of your existing mortgage to make it more affordable.
Loan modifications can involve several adjustments, such as reducing the interest rate, extending the loan term, or even deferring a portion of the principal. The goal is to create a sustainable payment plan that prevents foreclosure and helps homeowners stay in their homes. It’s not a one-size-fits-all solution, and eligibility often depends on your specific financial situation.
Common Types of Loan Modifications
Lenders might offer various forms of modification:
Interest Rate Reduction: Lowering your current interest rate, either temporarily or permanently.
Loan Term Extension: Stretching out the repayment period (e.g., from 25 years to 40 years) to reduce monthly payments.
Principal Forbearance: Placing a portion of the principal balance at the end of the loan, to be paid off when the home is sold or refinanced.
To qualify for a loan modification, you typically need to demonstrate a verifiable financial hardship and show that you can afford the modified payments. Contacting your mortgage servicer as soon as you anticipate issues is crucial. They can walk you through the available options and the application process. Don’t wait until you’re already behind on payments; early communication is key.
Government-sponsored programs, like those under the Federal Housing Administration (FHA) or the Department of Veterans Affairs (VA), also offer specific modification options for their respective loan types. Researching these can provide additional avenues for relief if you meet their criteria. A loan modification can be a lifeline for homeowners struggling to keep up with their mortgage, especially in an environment of increasing rates.
Solution 4: Building a Robust Emergency Fund
While not a direct mortgage payment solution, a strong emergency fund is an indispensable financial buffer against unexpected expenses, including potential increases in mortgage payments. Having readily available cash can prevent you from falling behind if interest rates rise or if other financial challenges emerge.
An emergency fund typically consists of three to six months’ worth of essential living expenses, stored in a separate, easily accessible savings account. This fund is meant for unforeseen circumstances like job loss, medical emergencies, or significant home repairs, but it can also absorb the shock of higher mortgage payments.
Why an Emergency Fund is Crucial
The importance of an emergency fund cannot be overstated, particularly when anticipating market volatility:
Financial Cushion: Provides a safety net during periods of financial strain.
Reduces Stress: Knowing you have reserves can alleviate anxiety about future economic changes.
Prevents Debt: Avoids resorting to high-interest credit cards or loans to cover shortfalls.
Start building or bolstering your emergency fund today. Even small, consistent contributions can accumulate over time. Automate savings transfers to make the process easier and more consistent. Prioritize this fund over discretionary spending until you reach your target amount. This financial discipline will pay dividends when unexpected costs or increased mortgage payments arise.
Think of your emergency fund as a proactive defense mechanism for your mortgage. It ensures that even if interest rates climb in 2026, you have the liquidity to manage the increased burden without jeopardizing your financial stability. It’s a foundational element of sound personal finance.
Solution 5: Budgeting and Expense Review
A comprehensive review of your household budget and expenses is a fundamental step in preparing for any financial challenge, including potential interest rate hikes in 2026. Understanding where your money goes allows you to identify areas for savings and reallocate funds to cover increased mortgage payments.
Start by tracking all your income and expenditures for at least a month. Categorize your spending into fixed costs (like mortgage, car payments) and variable costs (like groceries, entertainment). This detailed overview will reveal patterns and potential areas for adjustment.
Strategies for Effective Budgeting
Once you have a clear picture of your finances, implement these strategies:
Cut Discretionary Spending: Identify non-essential expenses that can be reduced or eliminated. This might include dining out less, canceling unused subscriptions, or finding cheaper alternatives for entertainment.
Negotiate Bills: Contact utility providers, insurance companies, and internet providers to see if you can negotiate lower rates or switch to more affordable plans.
Increase Income: Explore opportunities to boost your income, such as taking on a side hustle, selling unused items, or asking for a raise at work.
The goal is to create a surplus in your budget that can be directed towards your mortgage. Even small adjustments can free up significant funds over time. Use budgeting apps or spreadsheets to help you stay organized and track your progress. Regularly reviewing your budget ensures it remains aligned with your financial goals and current economic realities.
By proactively managing your expenses and optimizing your budget, you can create the financial flexibility needed to absorb higher mortgage payments without undue stress. This practical solution empowers you to take control of your financial future and navigate the challenges of rising interest rates effectively.
Key Strategy
Brief Description
Refinance to Fixed Rate
Lock in your interest rate to avoid future increases and gain payment predictability.
Extra Principal Payments
Reduce total interest paid and shorten loan term by accelerating principal repayment.
Emergency Fund
Build a financial buffer to absorb unexpected costs or higher mortgage payments.
Budget & Expense Review
Optimize spending and reallocate funds to create room for increased housing costs.
Frequently Asked Questions About 2026 Interest Rate Hikes
What factors typically drive interest rate hikes?▼
Interest rate hikes are primarily driven by inflation, economic growth, and Federal Reserve policy. When inflation is high, the Fed often raises rates to cool down the economy and stabilize prices, impacting mortgage costs.
How can refinancing protect my mortgage payments?▼
Refinancing to a fixed-rate mortgage locks in your interest rate, making your monthly payments predictable regardless of future market fluctuations. This shields you from the uncertainty of rising rates, especially with an adjustable-rate mortgage.
Is an emergency fund truly relevant for mortgage payment protection?▼
Absolutely. An emergency fund acts as a financial buffer. If interest rates increase your mortgage payments, or if other unexpected expenses arise, this fund prevents you from defaulting or falling into high-interest debt.
What are loan modification programs and who qualifies?▼
Loan modification programs alter existing mortgage terms to make payments more affordable for homeowners facing hardship. Eligibility typically requires demonstrating verifiable financial difficulty and the ability to afford the modified payments.
How much impact can extra principal payments have?▼
Even small, consistent extra principal payments can significantly reduce the total interest paid over the life of your loan and shorten your mortgage term. This strategy builds equity faster and provides a stronger financial position against rate hikes.
Conclusion
Preparing for potential interest rate hikes in 2026 is a proactive measure that can significantly safeguard your financial stability as a homeowner in the US. By understanding the economic forces at play and implementing practical solutions such as refinancing to a fixed rate, making additional principal payments, exploring loan modification programs, building a robust emergency fund, and meticulously reviewing your budget, you can effectively mitigate the impact of rising rates. Each of these strategies offers a pathway to greater financial security and peace of mind, ensuring your mortgage payments remain manageable even in a changing economic landscape. Take action today to protect your tomorrow.