Business Banking Solutions for Startups in 2026: Growth Accounts
Choosing the optimal business banking solution is crucial for startup success in 2026, impacting everything from cash flow management to future growth and financial stability.
By: Rafaela on September 23, 2026
Securing the right business banking solution in 2026 is paramount for startups, providing the financial infrastructure necessary for efficient operations and sustainable growth.
As a startup founder, understanding the evolving landscape of business banking solutions for startups in 2026 is not just beneficial, it’s essential. The right banking partner can significantly influence your financial health, operational efficiency, and overall trajectory towards growth. How do you navigate the myriad of options to find the perfect fit?
Understanding the Evolving Banking Landscape for Startups
The financial services industry is in constant flux, particularly for startups. What was considered cutting-edge just a few years ago might now be standard, or even obsolete. In 2026, startups face a dynamic environment where traditional banks compete with innovative fintechs, all vying to offer the best solutions tailored to nascent businesses.
This evolution is driven by technological advancements, changing customer expectations, and a growing recognition of the unique financial needs of startups. From seamless digital onboarding to integrated financial tools, the focus is on providing flexible, scalable, and user-friendly banking experiences that can keep pace with rapid growth.
The Rise of Digital-First Banking
Digital-first banks and fintech platforms have revolutionized how startups manage their finances. These entities often offer streamlined processes, lower fees, and advanced technological features that traditional banks are only now beginning to adopt. Their agile nature allows them to innovate quickly, introducing features specifically designed for the modern entrepreneurial journey.
Faster account opening processes.
Lower or no monthly maintenance fees.
Robust mobile banking applications.
Integration with popular accounting software.
The shift towards digital banking means startups can access their finances, make payments, and manage cash flow from anywhere, at any time, which is invaluable for businesses operating on tight schedules and often across different time zones. This flexibility supports the dynamic nature of startup operations.
Ultimately, understanding these shifts is the first step in making an informed decision about your startup’s financial future. The banking solution you choose today will lay the foundation for your financial operations tomorrow, making it a critical strategic choice.
Key Features to Look for in a Startup Business Account
When evaluating business banking solutions, startups need to prioritize features that support their unique growth phase. It’s not just about having a bank account; it’s about having a financial partner that understands and facilitates your journey from fledgling idea to established enterprise. The right features can save time, reduce costs, and provide crucial insights.
Consider the scale of your operations, your transaction volume, and your specific industry needs. A tech startup might prioritize different features than a retail business, for example. However, certain core functionalities remain universally beneficial for all startups.
Fee Structures and Transaction Limits
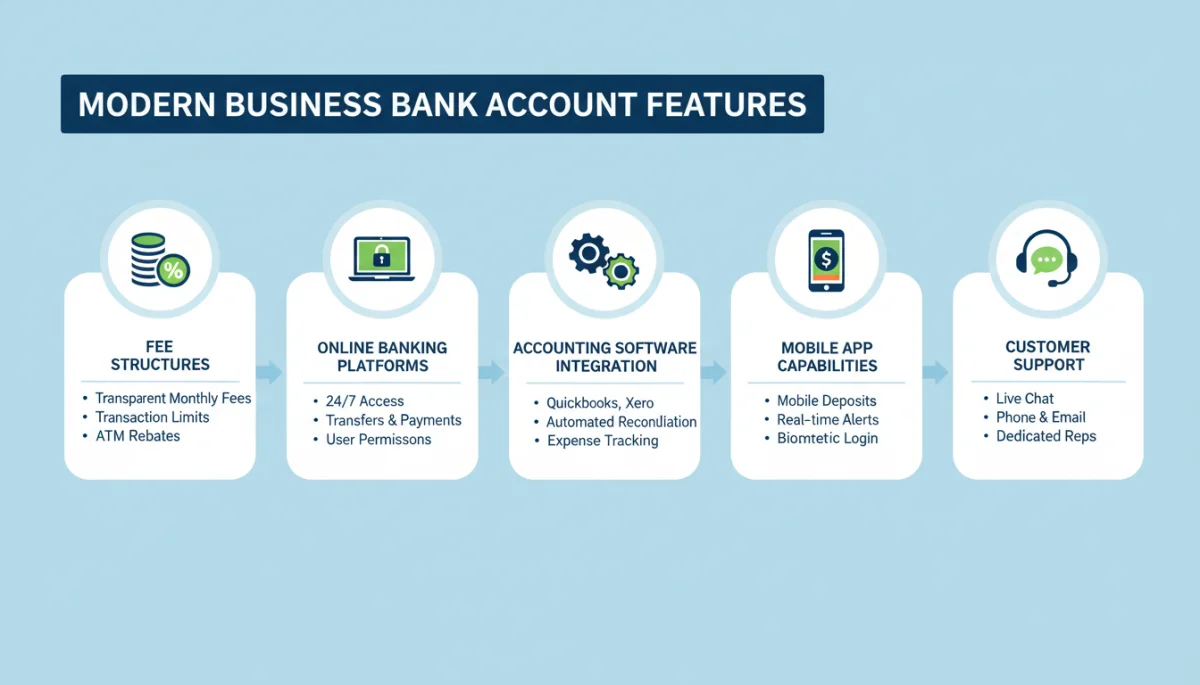
One of the most critical aspects to scrutinize is the fee structure. Startups often operate on lean budgets, so unexpected fees can quickly erode precious capital. Look for accounts with transparent fee schedules and, ideally, low or no monthly maintenance fees, especially during the initial growth phases.
Monthly service fees and waivers.
Transaction fees (per transaction, or after a certain limit).
ATM fees and foreign transaction fees.
Wire transfer costs (domestic and international).
Understanding these costs upfront can prevent unpleasant surprises down the line. Some banks offer introductory periods with waived fees, which can be a significant advantage for new businesses.
Integration with Business Tools and Software
In today’s interconnected business world, your banking solution should seamlessly integrate with your existing business tools. This includes accounting software, payment processors, and expense management platforms. Integration streamlines operations, reduces manual data entry, and minimizes errors, freeing up valuable time for core business activities.
Look for banks that offer APIs for developers or direct integrations with popular platforms like QuickBooks, Xero, Stripe, and PayPal. The ability to automate financial reporting and reconciliation can be a game-changer for lean startup teams.
Moreover, consider the availability of advanced features like virtual cards, expense tracking, and budgeting tools within the banking platform itself. These can provide a holistic view of your finances and help maintain tight control over spending.
Traditional Banks vs. Fintech Solutions for Startups
The choice between a traditional bank and a modern fintech solution is a pivotal decision for any startup. Both offer distinct advantages and disadvantages, and the best option depends largely on your specific needs, risk tolerance, and growth projections. It’s not a one-size-fits-all answer, and a careful comparison is warranted.
Traditional banks, often large and established institutions, offer a sense of security and a wide range of services, including physical branches. Fintech solutions, on the other hand, are typically digital-first, agile, and often more specialized in their offerings, leveraging technology to provide innovative experiences.
Advantages of Traditional Banks
Traditional banks bring decades, if not centuries, of experience to the table. Their established infrastructure and extensive branch networks can be reassuring for some founders, especially those who prefer in-person interactions or require complex financial services.
Established reputation and trust.
Extensive branch and ATM networks.
Broader range of financial products (loans, wealth management, etc.).
Dedicated business relationship managers.
For startups that anticipate needing large lines of credit, international banking services, or personalized financial advisory, a traditional bank might offer a more comprehensive suite of services. However, these often come with higher fees and slower customer service processes.
Benefits of Fintech and Neobanks
Fintech companies and neobanks are designed with the modern business in mind, often offering a more agile, cost-effective, and technologically advanced banking experience. They excel in areas where traditional banks often lag, such as user experience and integration capabilities.
These platforms typically prioritize digital interfaces, mobile accessibility, and seamless integration with other business software, which is highly appealing to tech-savvy startup founders.
Lower operating costs translate to fewer fees for customers.
Superior digital experience and mobile app functionality.
Faster account setup and transaction processing.
Specialized features for startups (e.g., virtual cards, spend management).
The choice ultimately hinges on balancing the perceived security and comprehensive offerings of traditional banks against the innovation, cost-effectiveness, and digital prowess of fintech solutions. Many startups find a hybrid approach, using a fintech for daily operations and a traditional bank for more complex needs, to be effective.
Navigating Compliance and Regulatory Requirements
For any business, especially a startup, understanding and adhering to compliance and regulatory requirements is non-negotiable. This is particularly true in the financial sector, where regulations are stringent and ever-evolving. Choosing a banking partner that helps you navigate this complex landscape effectively is crucial for long-term stability and avoiding costly penalties.
In 2026, the regulatory environment is becoming even more complex, with increased scrutiny on areas like anti-money laundering (AML), know your customer (KYC) protocols, and data privacy. Your chosen banking solution should have robust systems in place to ensure compliance, both for their operations and to assist yours.
Understanding KYC and AML for Startups
KYC (Know Your Customer) and AML (Anti-Money Laundering) are fundamental pillars of financial regulation. Banks are legally obligated to verify the identity of their customers and monitor transactions for suspicious activity. For startups, this means providing detailed documentation during account opening and maintaining transparency in all financial dealings.
A good banking partner will have a clear, efficient KYC process and provide tools or guidance to help your startup remain AML compliant. This includes understanding the source of funds, the nature of your business, and the ultimate beneficial owners.
Data Security and Privacy Concerns
In an increasingly digital world, data security and privacy are paramount. Startups handle sensitive financial and customer data, making it a prime target for cyber threats. Your banking solution must offer state-of-the-art security measures to protect your funds and information.
Multi-factor authentication (MFA).
Encryption protocols for data in transit and at rest.
Regular security audits and compliance with industry standards.
Clear data privacy policies in line with regulations like CCPA and GDPR (if applicable).
Always inquire about the bank’s security infrastructure and how they protect your data. A breach can be catastrophic for a startup’s reputation and financial health. Choosing a banking partner with a strong security track record provides peace of mind and builds trust with your customers and investors.
Scalability and Growth Potential of Banking Solutions
One of the most critical considerations for startups is scalability. Your business banking solution must be able to grow with you. What works for a bootstrapped operation with a few transactions a month might be wholly inadequate for a rapidly expanding company processing thousands of transactions and managing multiple payrolls. Planning for future growth from the outset saves significant headaches down the line.
As your startup evolves, your financial needs will become more complex. Your banking partner should be equipped to support this evolution, offering additional services and higher limits as required, without forcing a disruptive transition to a new provider.
Adapting to Increased Transaction Volume
As your business scales, so too will your transaction volume. A banking solution that imposes strict limits or exorbitant fees on transactions can quickly become a bottleneck. Look for accounts that offer tiered pricing, allowing you to upgrade to higher transaction limits as your business expands, or those with unlimited transaction options.
Consider solutions that provide efficient bulk payment options for payroll and vendor payments, as manual processing becomes unsustainable with growth. The ability to handle increased volume seamlessly is a hallmark of a scalable banking partner.
Access to Credit and Funding Options
Growth often requires capital. As your startup matures, you might need access to lines of credit, term loans, or other funding solutions. A banking partner that understands your business and has a track record of supporting growing companies can be invaluable.
Availability of business credit cards.
Options for small business loans or lines of credit.
Guidance on accessing venture debt or other alternative financing.
A clear path to upgrading account services as your needs expand.
Building a strong relationship with your bank early on can make it easier to secure financing when you need it most. They will have a better understanding of your financial history and future potential, making them more likely to support your funding requests.
Future Trends in Startup Banking for 2026 and Beyond
The financial technology landscape is dynamic, with new innovations constantly emerging. For startups planning for 2026 and beyond, it’s vital to consider how banking solutions will continue to evolve. Staying ahead of these trends can provide a competitive edge and ensure your financial infrastructure remains robust and future-proof.
The focus will increasingly be on personalization, automation, and embedded finance. Banks and fintechs will leverage AI and machine learning to offer more tailored services, predict financial needs, and integrate banking seamlessly into other business operations.
AI and Automation in Financial Management
Artificial intelligence (AI) and machine learning (ML) are set to play an even larger role in business banking. These technologies can automate routine tasks, provide predictive analytics, and offer personalized financial advice, helping startups make smarter decisions.
Automated expense categorization and reconciliation.
Predictive cash flow forecasting.
AI-powered fraud detection.
Personalized recommendations for financial products.
Imagine a banking platform that automatically flags unusual spending patterns, suggests optimal times for payments, or even identifies potential cost savings. These capabilities will become increasingly common, transforming how startups manage their finances.
Embedded Finance and BaaS (Banking as a Service)
Embedded finance, or Banking as a Service (BaaS), is a growing trend where financial services are integrated directly into non-financial platforms. This means your banking functionalities could be seamlessly built into your accounting software, e-commerce platform, or even your internal operational tools.
This integration aims to make financial transactions invisible and effortless, allowing businesses to focus on their core activities without constantly switching between different applications. For startups, this could mean greater efficiency and a more unified operational workflow.
By understanding these emerging trends, startups can choose banking solutions that are not only suitable for their current needs but also positioned to adapt and thrive in the future. The right partner will be one that invests in innovation and offers a clear roadmap for future-proof financial services.
Key Aspect
Description for Startups
Fee Structure
Look for low or no monthly fees and transparent transaction costs to preserve capital.
Digital Integration
Ensure seamless connectivity with accounting software and payment processors for efficiency.
Scalability
Choose solutions that can adapt and expand with your business’s increasing transaction volume and funding needs.
Security & Compliance
Verify robust security measures and adherence to KYC/AML regulations to protect your assets.
Frequently Asked Questions About Startup Banking
What is the primary difference between traditional banks and neobanks for startups?▼
Traditional banks offer a wide range of services, physical branches, and established trust, while neobanks are digital-first, agile, often have lower fees, and provide advanced tech integrations, catering specifically to modern, tech-savvy businesses.
How important are integration capabilities for a startup’s bank account?▼
Integration with accounting software and payment processors is crucial for startups. It streamlines financial management, reduces manual errors, and saves valuable time, allowing founders to focus on core business growth rather than administrative tasks.
What kind of fees should startups be most aware of?▼
Startups should pay close attention to monthly service fees, transaction fees (especially if exceeding a certain limit), ATM fees, and wire transfer costs. Transparent fee structures are essential to avoid unexpected expenses that can impact a lean budget.
Why is scalability a key factor when choosing a banking solution?▼
Scalability ensures your banking solution can adapt as your startup grows. An account that supports increasing transaction volumes, offers expanded services, and provides access to credit as needed prevents the need for disruptive bank changes later on.
What role will AI and automation play in future startup banking?▼
AI and automation will enhance financial management by automating tasks, providing predictive analytics for cash flow, and offering personalized financial advice. This will enable smarter decision-making and greater operational efficiency for startups.
Conclusion
Choosing the right business banking solution for your startup in 2026 is a strategic decision that extends far beyond simply opening an account. It involves a thorough evaluation of fee structures, technological integrations, scalability, security, and the ability of your chosen partner to support your growth trajectory. Whether you opt for a traditional institution or an innovative fintech, the key is to select a solution that aligns with your business model, simplifies financial management, and provides the necessary tools to navigate the dynamic market. By making an informed choice, you empower your startup with a robust financial foundation, paving the way for sustainable success and future expansion.