Bridge Loans 2026: Real Estate Investor’s Guide
Bridge loans in 2026 represent a vital short-term financing tool, empowering real estate investors to seize immediate opportunities and bridge gaps between property transactions.
The dynamic real estate market of 2026 demands agile financial strategies. For savvy investors,
bridge loans in 2026 are emerging as an indispensable tool, offering the speed and flexibility needed to capitalize on fleeting opportunities. This guide delves into how these short-term financing solutions can be your key to unlocking rapid real estate growth.
Understanding bridge loans in 2026
Bridge loans are essentially short-term, high-interest loans designed to provide quick capital for a specific period, typically from a few months to a couple of years. In the context of real estate, they act as a ‘bridge’ between a current financial situation and a future one, such as selling an old property to buy a new one, or securing a property before long-term financing is finalized. For 2026, their relevance is heightened by a market that continues to value speed and decisiveness.
These loans are particularly attractive to real estate investors who need to close a deal quickly, often bypassing the slower approval processes of conventional mortgages. They are secured by real estate, meaning the property itself serves as collateral, which can make them easier to obtain for those with strong assets, even if traditional credit profiles are less than perfect. The flexibility of terms and rapid disbursement are key characteristics that define their utility in today’s fast-paced investment landscape.
Key characteristics of bridge loans
- Speed of approval: Bridge loans can be approved and funded much faster than traditional loans, sometimes in a matter of days or weeks.
- Short repayment period: Typically ranging from 6 months to 2 years, aligning with short-term investment strategies.
- Higher interest rates: Due to their short-term nature and speed, bridge loans usually come with higher interest rates compared to conventional mortgages.
- Asset-based lending: Approval often relies more on the value of the collateral property than on the borrower’s credit score.
Understanding these core characteristics is crucial for any investor considering a bridge loan in 2026. The ability to act swiftly in competitive markets can often outweigh the cost of higher interest, especially when a lucrative opportunity is on the line. Investors must weigh the benefits of speed against the increased cost of capital, ensuring the potential returns justify the financing expense.
Ultimately, bridge loans serve a very specific purpose: to provide temporary liquidity. They are not intended as long-term financing solutions but rather as strategic tools to facilitate transitions or secure properties that would otherwise be out of reach due to time constraints. Their role in the 2026 real estate market is to enable investors to maintain momentum and capture value efficiently.
Why real estate investors leverage bridge loans in 2026
Real estate investors in 2026 face a dynamic market with both immense opportunities and significant challenges. Bridge loans have become a preferred financing option due to their ability to address several critical needs unique to property investment. They allow investors to act decisively, a trait that can make or break a deal in competitive environments. The ability to quickly secure funds means investors can submit stronger offers, often all-cash, which are highly attractive to sellers looking for a swift closing.
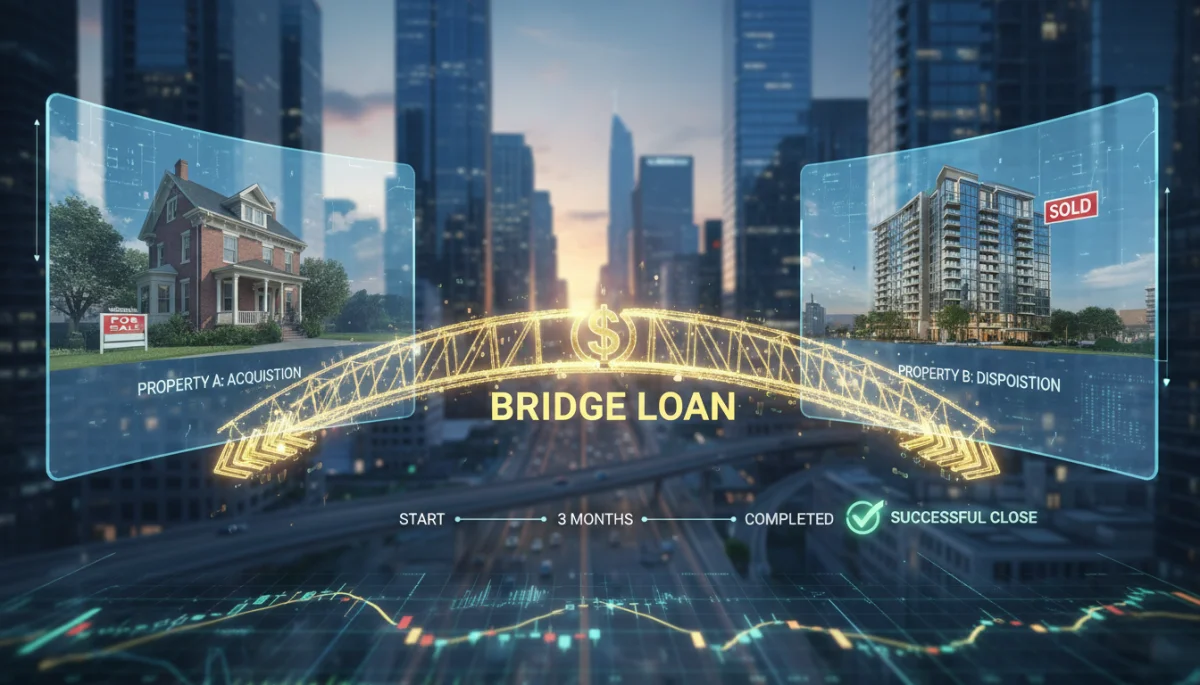
One primary use case is bridging the gap between selling an existing property and purchasing a new one. Rather than waiting for the sale of their current asset to finalize, investors can use a bridge loan to fund the down payment or even the entire purchase of a new property. This prevents the loss of a desirable property due to timing issues and ensures a smooth transition between investments. This strategy is particularly powerful in hot markets where properties are snatched up quickly.
Common scenarios for bridge loan utilization
- Quick property acquisition: Securing a property that requires immediate funding before long-term financing is arranged.
- Fix-and-flip projects: Providing capital for purchasing, renovating, and then reselling a property in a short timeframe.
- Avoiding contingent offers: Allowing investors to make a non-contingent offer on a new property before their current one sells.
- Commercial property transitions: Facilitating the purchase of new commercial real estate while waiting for an existing commercial asset to sell.
Beyond these scenarios, bridge loans also offer flexibility for investors dealing with distressed properties or those requiring significant renovation. The rapid access to capital can be crucial for funding repairs or improvements that increase a property’s value before it’s refinanced or sold. This strategic application allows investors to maximize their returns by transforming undervalued assets into profitable ventures. The adaptability of bridge loans makes them a versatile tool in an investor’s financial toolkit for 2026.
In essence, bridge loans empower real estate investors to overcome liquidity challenges and timing discrepancies, ensuring that valuable opportunities are not missed. They are a tactical financial instrument designed for strategic advantage in a fast-moving market, providing the necessary capital to keep investment pipelines flowing smoothly and efficiently.
Benefits of bridge loans for savvy investors
For the astute real estate investor navigating the 2026 market, the benefits of utilizing bridge loans extend far beyond mere convenience. These financing solutions offer distinct advantages that can significantly impact an investment’s success, particularly when timing and flexibility are paramount. The ability to move with speed and precision can differentiate a successful investor from one who misses out on prime opportunities.
One of the most compelling benefits is the speed of funding. Traditional financing can take weeks or even months to process, a timeline that often proves too long for competitive real estate deals. Bridge loans, however, can be approved and disbursed in a fraction of that time, sometimes within days. This rapid access to capital allows investors to act decisively, placing strong, non-contingent offers that are highly attractive to sellers looking for quick closings. This speed can be the deciding factor in securing a desirable property in a competitive market.
Strategic advantages of bridge financing
- Competitive advantage: Make all-cash or non-contingent offers, standing out to sellers.
- Flexibility in underwriting: Lenders often focus on the asset’s value rather than solely on the borrower’s credit history, offering more flexibility.
- Preservation of capital: Allows investors to deploy capital strategically without tying up all their liquid assets in one deal.
- Opportunity capture: Enables quick acquisition of undervalued properties or those requiring immediate attention before a conventional loan can be secured.
Furthermore, bridge loans provide a level of flexibility that traditional financing often lacks. The terms can often be tailored to the specific needs of the investor and the project, from interest-only payments to various repayment structures. This adaptability is invaluable for complex deals or those with uncertain timelines, allowing investors to manage cash flow more effectively and adjust strategies as market conditions evolve. Such bespoke arrangements can be crucial for maximizing profitability.
Another significant advantage is the potential for higher returns. By enabling investors to acquire properties quickly, especially those requiring rehabilitation or with time-sensitive pricing, bridge loans can facilitate projects that yield substantial profits. The short-term nature means the higher interest rates are paid for a limited period, and the increased value generated by the investment often far outweighs the financing cost. This makes bridge loans a powerful tool for value creation in real estate.
Potential risks and considerations for investors
While bridge loans offer compelling advantages for real estate investors in 2026, it’s crucial to approach them with a clear understanding of the associated risks and considerations. These are not ‘set it and forget it’ financial instruments; they require careful planning and a robust exit strategy. Overlooking potential pitfalls can quickly turn a strategic advantage into a financial burden.
The most prominent consideration is the higher cost of capital. Bridge loans typically come with significantly higher interest rates and fees compared to conventional mortgages. This is due to their short-term nature, rapid funding, and often, the higher perceived risk by lenders. Investors must meticulously calculate these costs into their project’s pro forma to ensure profitability isn’t eroded. A slight miscalculation or delay in the exit strategy can quickly escalate expenses, eating into potential returns.
Navigating bridge loan challenges
- Higher interest rates and fees: Can significantly impact profitability if not managed carefully.
- Strict repayment terms: Missing payments can lead to severe penalties, including foreclosure.
- Dependence on exit strategy: The success of a bridge loan hinges on the timely execution of a refinance or sale.
- Market volatility: Unexpected downturns can hinder the ability to sell or refinance the property as planned.
Another critical risk lies in the exit strategy. Bridge loans are inherently temporary, meaning investors must have a clear plan for how they will repay the loan before the term expires. This typically involves either selling the property or securing long-term financing (a ‘take-out’ loan). If the property doesn’t sell as quickly as anticipated, or if market conditions shift, making refinancing difficult, investors could face significant challenges, including the potential loss of the property through foreclosure.
Market volatility in 2026 also presents a substantial risk. Unforeseen economic shifts, interest rate changes, or localized market downturns could impact property values or the availability of long-term financing. Investors must build contingencies into their plans, such as having reserve funds or alternative exit strategies, to mitigate these external factors. A thorough due diligence process and a conservative valuation of the property are paramount to safeguarding against market uncertainties.
In summary, while bridge loans are powerful tools, they demand a sophisticated understanding of both the real estate market and financial planning. Investors must conduct comprehensive risk assessments, develop solid exit strategies, and maintain financial discipline to harness the benefits of bridge financing while minimizing its inherent dangers.
Structuring your bridge loan for success in 2026
Successfully utilizing a bridge loan in 2026 requires more than just securing funds; it demands meticulous structuring and strategic planning. A well-structured bridge loan aligns with your investment goals, mitigates risks, and paves the way for a smooth transition to your long-term financing or sale. This proactive approach ensures that the loan serves its intended purpose without becoming a burden.
The first step in structuring involves clearly defining your investment timeline and exit strategy. Since bridge loans are short-term, knowing precisely when and how you intend to repay the loan is paramount. Are you planning to sell the property? If so, what is your realistic timeline for renovation, marketing, and closing? Or are you aiming to refinance into a conventional mortgage? Understanding these details will help determine the appropriate loan term and repayment schedule, preventing costly extensions or penalties.
Key elements of effective bridge loan structuring
- Clear exit strategy: Define whether you’ll sell or refinance, with realistic timelines.
- Realistic valuation: Ensure the property’s after-repair value (ARV) supports the loan amount and projected profits.
- Contingency planning: Allocate funds for unexpected delays or market shifts.
- Lender selection: Choose a lender with experience in bridge loans and a reputation for transparency.
Negotiating favorable terms with your lender is another critical aspect. While bridge loans typically have higher interest rates, there can be room to negotiate on origination fees, interest rate spreads, or prepayment penalties. Investors should compare offers from multiple lenders, focusing not just on the headline interest rate but on the total cost of the loan, including all fees. A reputable lender will be transparent about all charges and willing to discuss terms that work for both parties.
Furthermore, building in a buffer for unexpected costs or delays is a wise move. Real estate projects rarely go exactly as planned, and having contingency funds can prevent a small setback from derailing your entire strategy. This might include extra capital to cover additional renovation costs, extended holding periods, or unexpected market fluctuations. A well-cushioned plan provides peace of mind and financial resilience.
By carefully structuring your bridge loan, you’re not just borrowing money; you’re creating a strategic financial pathway that supports your real estate objectives. This proactive approach to planning and negotiation is what truly maximizes the power of bridge financing in 2026.
Finding the right bridge loan lender in 2026
Identifying the appropriate bridge loan lender in 2026 is as crucial as understanding the loan product itself. The lending landscape is diverse, and not all lenders are created equal. A good lender will not only provide competitive terms but also offer expertise, flexibility, and a streamlined process, all of which are vital for real estate investors operating on tight timelines.
Start by researching lenders specializing in bridge loans for real estate. These are often private lenders, hard money lenders, or specialized divisions within larger financial institutions. Unlike traditional banks that might have more rigid criteria, these specialized lenders are typically more agile and experienced in evaluating asset-based loans. They understand the nuances of real estate investment and can often make quicker decisions based on the property’s potential.
Qualities of an ideal bridge loan lender
- Specialization: Lenders with proven experience in bridge loans for real estate.
- Reputation: Positive reviews and testimonials from other real estate investors.
- Transparency: Clear communication regarding all fees, interest rates, and terms.
- Flexibility: Willingness to work with unique deal structures and timelines.
- Speed: A track record of quick approvals and funding.
When evaluating potential lenders, pay close attention to their track record and reputation. Seek out reviews, testimonials, and referrals from other investors in your network. A lender with a strong reputation for reliability and fair dealings can save you significant headaches down the line. Transparency regarding all fees, interest rates, and potential penalties is non-negotiable; ensure every aspect of the loan agreement is clear before committing.
Furthermore, consider the lender’s flexibility. Can they accommodate a slightly longer loan term if unforeseen delays occur? Are they open to different repayment structures that align with your project’s cash flow? A lender who is willing to be a partner in your success, rather than just a financier, can provide invaluable support. This flexibility can be particularly important in the unpredictable nature of real estate development and investment.
Ultimately, the right bridge loan lender for 2026 is one who understands your specific needs, offers competitive and transparent terms, and can deliver funds efficiently. Taking the time to thoroughly vet potential partners will pay dividends in the long run, ensuring a smoother and more successful investment journey.
The future of bridge loans in the 2026 real estate market
As we look ahead to the real estate market in 2026, the role of bridge loans is poised to evolve, reflecting broader economic trends and technological advancements. Their fundamental utility as a short-term financing solution will remain, but the landscape in which they operate will likely see significant shifts. Investors must stay informed to continue leveraging these tools effectively.
One anticipated trend is the increasing integration of technology into the lending process. Digital platforms are likely to streamline applications, underwriting, and funding, making bridge loans even faster and more accessible. Artificial intelligence and big data analytics could enable lenders to assess risk more accurately and offer more tailored products, potentially leading to more competitive rates for well-qualified projects. This technological leap will undoubtedly enhance efficiency for both borrowers and lenders.
Emerging trends impacting bridge loans
- Digitalization of lending: Faster applications and approvals through AI and online platforms.
- Increased customization: More flexible loan products tailored to specific investor needs and project types.
- Sustainable investing focus: Potential for ‘green’ bridge loans for eco-friendly real estate projects.
- Regulatory adaptations: Evolving regulations may influence loan terms and accessibility.
Furthermore, market conditions in 2026, including potential interest rate fluctuations and shifts in property demand, will influence the attractiveness and terms of bridge loans. In a market with rising interest rates, the short-term nature of bridge loans might become even more appealing, allowing investors to secure properties and then refinance when rates are more favorable. Conversely, in a softening market, lenders might become more cautious, requiring stronger collateral or more conservative loan-to-value ratios.
The growing emphasis on sustainable and ESG (Environmental, Social, and Governance) investing could also lead to new types of bridge loan products. Lenders might offer preferential terms for projects that meet certain sustainability criteria, aligning with a broader industry push towards responsible development. Investors who incorporate these elements into their projects could find themselves with additional financing options and potentially lower costs.
In conclusion, while the core function of bridge loans will endure, their future in 2026 will be shaped by technological innovation, market dynamics, and evolving investment priorities. Real estate investors who remain adaptable and informed about these changes will be best positioned to maximize the strategic advantages that bridge loans offer.
| Key Aspect | Brief Description |
|---|---|
| Purpose | Short-term financing to bridge gaps between real estate transactions. |
| Key Benefit | Enables rapid property acquisition and competitive offers. |
| Main Risk | Higher costs and reliance on a solid exit strategy. |
| Future Trend | Increased digitalization and customized loan products. |
Frequently asked questions about bridge loans
Bridge loans are generally short-term, with repayment periods typically ranging from 6 months to 2 years. This short duration is designed to bridge the gap until a longer-term financing solution is secured or the property is sold, aligning with agile real estate investment cycles.
Yes, bridge loans usually carry higher interest rates compared to traditional mortgages. This is due to their short-term nature, faster funding process, and the higher risk often associated with them. Investors must factor these increased costs into their financial projections for profitability.
Bridge loans are primarily secured by real estate. The property being purchased, or another existing property owned by the borrower, serves as collateral. This asset-based lending approach allows for quicker approval processes and often less stringent credit requirements.
Absolutely. Bridge loans are an excellent financing option for fix-and-flip projects. They provide the quick capital needed to acquire and renovate a property, allowing investors to rapidly increase its value before selling it for a profit, all within the typical short timeframe of such ventures.
An exit strategy is the plan to repay the bridge loan, typically through selling the property or refinancing it with a conventional, long-term mortgage. A clear and realistic exit strategy is crucial for securing a bridge loan and managing its associated risks effectively, ensuring the loan serves its temporary purpose.
Conclusion
Bridge loans in 2026 stand as a powerful, albeit specialized, financing instrument for real estate investors. Their unparalleled speed and flexibility offer a distinct competitive edge in a market that rewards agility. While they come with higher costs and demand a robust exit strategy, when utilized judiciously, bridge loans can unlock significant opportunities, facilitating seamless transitions and enabling investors to capitalize on time-sensitive deals. For those prepared to navigate their intricacies, bridge loans are an essential tool for strategic growth in the evolving real estate landscape.