Effectively disputing banking errors is crucial for protecting your financial well-being. This guide provides a comprehensive, step-by-step approach for 2026, empowering you to navigate the process with confidence and secure your funds.
By: Rafaela on September 23, 2026
Effectively disputing banking errors is crucial for protecting your financial well-being. This guide provides a comprehensive, step-by-step approach for 2026, empowering you to navigate the process with confidence and secure your funds.
In an increasingly digital financial landscape, understanding how to dispute banking errors: a step-by-step guide for 2026 to protect your funds is more vital than ever. Even with advanced security measures, mistakes happen, and unauthorized transactions or incorrect charges can appear on your account. Knowing the precise steps to take can save you not only money but also significant stress and potential financial fallout.
Understanding Common Banking Errors in 2026
Before you can effectively dispute a banking error, it’s essential to recognize what constitutes one. Banking errors can manifest in various forms, from simple data entry mistakes to more complex issues like fraudulent activity. Being able to identify these discrepancies quickly is the first line of defense in protecting your financial health.
With the rapid evolution of financial technology, new types of errors can emerge, making vigilance key. From AI-driven transaction processing to real-time payment systems, the potential for glitches or misinterpretations of data can sometimes lead to unexpected charges or missing funds.
Types of Errors to Watch For
It’s not always obvious when an error has occurred. Sometimes, it might be a small charge you don’t recognize, or a recurring payment that appears to be incorrect. Staying proactive in monitoring your accounts is paramount.
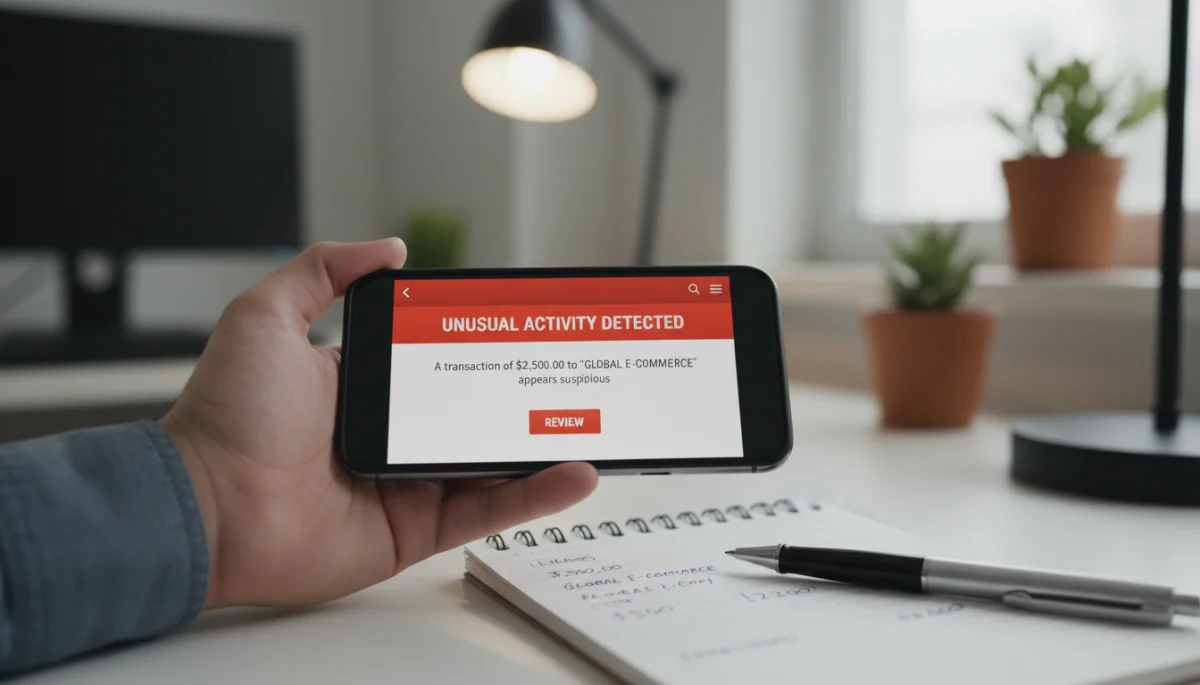
Unauthorized Transactions: Charges on your statement that you did not make or authorize. This often indicates fraud or identity theft.
Incorrect Amounts: A transaction you authorized appears with a different, usually higher, amount than expected. This could be a merchant error or a system glitch.
Duplicate Charges: The same transaction appearing twice on your statement. This is a common processing error.
Missing Deposits/Payments: Funds you deposited or payments you made not reflecting in your account balance. This can be particularly frustrating and requires immediate attention.
Regularly reviewing your bank statements, whether paper or digital, and setting up transaction alerts for your accounts can significantly reduce the time it takes to spot these issues. The sooner an error is identified, the easier it typically is to resolve.
Immediate Actions When You Spot an Error
Discovering a banking error can be alarming, but panic serves no purpose. Your immediate actions are critical in initiating the dispute process and mitigating any potential damage. Time is often of the essence, especially with certain types of errors, so acting swiftly and methodically is crucial.
The first step should always be to gather all relevant information and avoid making assumptions. A clear, documented approach will strengthen your case when communicating with your bank and other relevant parties.
Gathering Documentation and Evidence
Before contacting your bank, compile all pertinent details regarding the error. This preparation will make your conversation more productive and provide concrete evidence to support your claim.
Bank Statements: Highlight the specific transactions in question.
Receipts: If the error relates to a purchase, provide the original receipt.
Correspondence: Any emails, texts, or letters related to the transaction or account.
Dates and Times: Note down when the error occurred and when you first noticed it.
Having this information organized will not only save you time but also demonstrate your diligence to the bank, potentially expediting the resolution process. It’s like building a solid case before presenting it.
Contacting Your Bank Promptly
Once you have your documentation, contact your bank. Most banks have specific departments or procedures for handling disputes. Do not delay, as federal laws set time limits for disputing certain types of errors.
Use the bank’s official channels for disputes, which are usually outlined on their website or in your account agreement. While a quick phone call might seem easiest, ensure you follow up with a formal written notice if required. This creates a paper trail, which is invaluable.
Navigating the Formal Dispute Process
After your initial contact, your bank will guide you through their formal dispute process. This typically involves submitting a written claim and cooperating with their investigation. Understanding this process can help manage your expectations and ensure you fulfill all necessary requirements.
The bank’s investigation aims to verify your claim and determine the root cause of the error. This might involve reviewing transaction logs, contacting merchants, or even involving their fraud department if necessary.
Submitting a Written Dispute
Most financial institutions require a written dispute for certain types of errors, especially those protected by federal regulations like the Electronic Fund Transfer Act (EFTA) or the Fair Credit Billing Act (FCBA). A written dispute ensures your claim is formally recorded and initiates a timeline for the bank’s response.
Your written dispute should include all the details you gathered, such as your account number, the date and amount of the error, and a clear explanation of why you believe it’s an error. Keep a copy of everything you send, along with proof of mailing, such as a certified mail receipt.
Understanding Your Rights and Timelines
Federal laws provide consumers with specific protections when it comes to banking errors. For instance, under EFTA, you generally have 60 days from the date your statement was sent to notify your bank of an unauthorized electronic fund transfer. The bank then has 10 business days to investigate and must provisionally credit your account within that period if they cannot complete their investigation.
For credit card billing errors, the FCBA provides similar protections, also with a 60-day notification window. Familiarizing yourself with these regulations can empower you during the dispute process.
Escalating Your Complaint If Necessary
While most banking errors are resolved directly with the bank, there are instances where your initial attempts may not yield a satisfactory outcome. In such cases, knowing when and how to escalate your complaint is crucial for protecting your funds and ensuring your voice is heard.
Escalation doesn’t mean immediately jumping to external agencies. Often, there are internal steps within the bank itself that can lead to a resolution, especially if you feel your case wasn’t properly reviewed initially.
Internal Bank Escalation
If you’re not satisfied with the initial response from your bank, request to speak with a supervisor or manager. Clearly and calmly reiterate your case, providing all documentation again if necessary. Many banks have dedicated customer advocacy or complaint resolution departments that can offer a fresh perspective on your situation.
Sometimes, simply moving up the chain of command within the bank can lead to a quicker and more favorable resolution. Persistence, coupled with a polite but firm approach, can be very effective.
External Regulatory Bodies
If internal escalation fails, several external regulatory bodies can assist. These agencies oversee financial institutions and are designed to protect consumers. Filing a complaint with them can prompt a more thorough review of your case.
Consumer Financial Protection Bureau (CFPB): This federal agency protects consumers in the financial marketplace. They handle complaints about banks, credit unions, and other financial companies.
Office of the Comptroller of the Currency (OCC): For national banks and federal savings associations, the OCC investigates consumer complaints and ensures banks comply with federal laws.
Federal Deposit Insurance Corporation (FDIC): The FDIC handles complaints against state-chartered banks that are not members of the Federal Reserve System.
Each of these bodies has an online complaint portal, making the process relatively straightforward. Providing them with all your documentation and a detailed account of your dispute will help them process your complaint efficiently.
Preventative Measures for 2026
While knowing how to dispute banking errors is essential, preventing them in the first place is even better. In 2026, with advanced financial technologies, there are numerous proactive steps you can take to minimize the risk of errors and enhance your financial security.
These measures range from simple account monitoring habits to leveraging the latest security features offered by your financial institutions. A proactive approach is always more effective than a reactive one when it comes to safeguarding your money.
Leveraging Technology for Security
Modern banking offers a suite of tools designed to protect your accounts. Make sure you are utilizing them to their full potential. These features are often easy to set up and can provide an early warning system against potential errors or fraud.
Transaction Alerts: Set up email or text alerts for all transactions, especially for amounts over a certain threshold, international transactions, or ATM withdrawals.
Two-Factor Authentication (2FA): Always enable 2FA for your online banking access. This adds an extra layer of security, making it harder for unauthorized individuals to access your accounts.
Biometric Security: Use fingerprint or facial recognition for banking apps when available.
Regularly updating your passwords and using strong, unique combinations for your financial accounts is also a fundamental security practice that cannot be overstated. Consider using a reputable password manager.
Regular Account Monitoring and Reconciliation
The most effective preventative measure remains consistent vigilance. Make it a habit to regularly review your financial statements and reconcile your accounts. This means comparing your records with the bank’s records to ensure everything matches up.
Don’t just glance at your balance; scrutinize each transaction. Even small, unfamiliar charges can be indicators of larger issues like data breaches or identity theft. Catching these early can prevent significant financial losses.
The Role of Digital Wallets and Payment Apps
The proliferation of digital wallets and payment apps has transformed how we conduct transactions, offering convenience but also introducing new considerations when it comes to banking errors. In 2026, these platforms are integral to many people’s financial lives, making it crucial to understand their role in the dispute process.
While these apps often have their own dispute mechanisms, they are also linked to your primary bank account or credit card, meaning errors can originate from either end. A comprehensive approach involves understanding the interplay between these different financial tools.
Disputing Errors in Digital Wallets
If an error occurs within a digital wallet like Apple Pay, Google Pay, or a payment app like Venmo or PayPal, your first step should be to use the app’s internal dispute resolution system. These platforms usually have specific procedures for reporting unauthorized transactions or incorrect charges.
Document everything, just as you would with a bank error. Screenshots of the transaction, communication with the merchant, and any relevant app notifications can be valuable evidence. Many digital wallets also offer transaction history that can be exported for your records.
Connecting Digital Wallet Disputes to Your Bank
Even if you initiate a dispute through a digital wallet, it’s often wise to also notify your primary bank or credit card company, especially if the funds were drawn directly from your account or credit line. This creates an additional layer of protection and ensures all relevant financial institutions are aware of the issue.
The specific steps might vary depending on the app and your bank, but generally, you’ll want to inform your bank that you’ve initiated a dispute through a third-party payment service and provide them with any case numbers or reference IDs you receive. This coordinated approach maximizes your chances of a swift and successful resolution.
Key Point
Brief Description
Identify Errors Promptly
Regularly review statements for unauthorized, incorrect, or duplicate transactions.
Document Everything
Gather all statements, receipts, and communication before contacting your bank.
Understand Your Rights
Familiarize yourself with federal laws like EFTA and FCBA for dispute timelines.
Leverage Security Tools
Utilize transaction alerts, 2FA, and biometric security to prevent future errors.
Frequently Asked Questions About Banking Errors
How quickly do I need to report a banking error?▼
It is crucial to report banking errors as soon as you discover them. For electronic fund transfers, federal law generally gives you 60 days from the statement date to notify your bank. Prompt action increases your chances of a full recovery and minimizes potential liabilities.
What documentation is essential for a dispute?▼
Key documentation includes your bank statements highlighting the error, receipts for legitimate transactions, and any correspondence with merchants. A detailed log of dates, times, and amounts related to the discrepancy will significantly strengthen your case with the bank.
What if my bank doesn’t resolve the issue?▼
If your bank doesn’t resolve the issue to your satisfaction, you can escalate the complaint. First, try speaking with a supervisor within the bank. If that fails, consider filing a complaint with external regulatory bodies like the Consumer Financial Protection Bureau (CFPB) or the FDIC.
Can digital wallet errors be disputed through my bank?▼
While digital wallets like PayPal or Venmo have their own dispute processes, it’s advisable to also notify your primary bank or credit card company if the funds were drawn from their accounts. This ensures comprehensive coverage and a coordinated resolution effort.
What proactive steps can I take to prevent banking errors?▼
To prevent banking errors, regularly monitor your accounts, set up transaction alerts, and enable two-factor authentication (2FA). Always use strong, unique passwords and consider biometric security features offered by your banking apps for enhanced protection.
Conclusion
Navigating the complexities of banking errors can seem daunting, but armed with the right knowledge and a clear, step-by-step approach, you can effectively protect your funds in 2026 and beyond. From prompt identification to meticulous documentation and understanding your consumer rights, each action plays a crucial role in securing your financial well-being. By staying vigilant, leveraging available technology, and knowing when to escalate a complaint, you empower yourself to resolve discrepancies efficiently and maintain confidence in your financial transactions. Remember, your financial security is paramount, and being proactive is your best defense against unexpected banking challenges.