Improve Payment History in 90 Days: Credit Boost 2026
Discover how to significantly improve your payment history in just 90 days, laying the groundwork for a stronger credit score and enhanced financial well-being by 2026. This guide provides actionable strategies for managing your payments effectively.
2026 Guide to Understanding Your Credit Report: Key Sections
This guide provides an essential overview of your 2026 credit report, detailing its key sections and explaining what information to scrutinize for accuracy and financial well-being. Understand how to interpret your report and protect your credit.
Debt Consolidation Loans 2026: Rates & Action
Debt consolidation loans in 2026 offer a strategic path to simplify finances, potentially lowering monthly payments and interest rates, with current offerings typically ranging from 7.5% to 18.2% based on creditworthiness and market conditions.
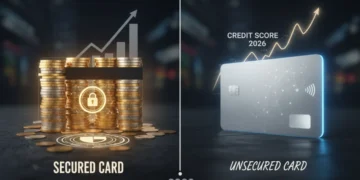
Secured vs. Unsecured Credit Cards: 500-600 Score Guide 2026
For individuals with a 500-600 credit score in 2026, understanding the differences between secured and unsecured credit cards is crucial for effective credit building, with secured cards often providing a more accessible entry point to establishing a positive credit history.
Debt Settlement 2026: Negotiate a 40% Reduction
This guide provides a comprehensive look at debt settlement in 2026, offering insights into its suitability and practical steps for negotiating a significant reduction, potentially up to 40%, on your unsecured debts.
Federal Lending Regulations 2026: Personal Loan Impact
New federal lending regulations in 2026 are set to significantly reshape the personal loan landscape, affecting eligibility, interest rates, and repayment terms for borrowers across the United States.
Understanding Your Credit Utilization Ratio This Quarter
Effectively managing your credit utilization ratio is crucial for a strong credit score, directly impacting your financial health and future borrowing opportunities, making it a key metric to monitor.
FICO 10 T Updates: Optimize Your Credit Profile for 2026
Understanding and adapting to the latest FICO 10 T updates in early 2026 is crucial for optimizing your credit profile, ensuring better loan terms, and maintaining robust financial health in an evolving credit landscape.
Building Business Credit from Scratch in 2026: 4 Steps
Establishing business credit from the ground up in 2026 is crucial for new entrepreneurs. This guide outlines the first four fundamental steps to build a strong financial profile, ensuring future growth and access to essential funding.
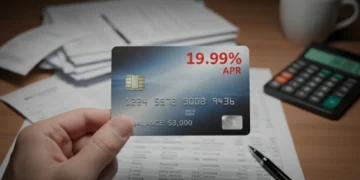
Credit Card Balance: 19.99% APR on $3,000 Costs Analyzed
Understanding the real financial impact of a credit card balance is crucial; carrying a $3,000 balance at a 19.99% APR can lead to significant hidden costs that extend beyond the principal amount, affecting long-term financial health.